Author: Deepak Mishra

Mexico Combined Heat and Power Market Size to Hit USD 655.9 Million in 2034 | Grow CAGR by 4.79%

Mexico Combined Heat and Power Market Size to Hit USD 655.9 Million in 2034 | Grow CAGR by 4.79%

IMARC Group has recently released a report titled “Mexico Combined Heat and Power Market Report by Fuel Type, Application, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

Mexico Combined Heat and Power Market Size and Forecast 2026–2034

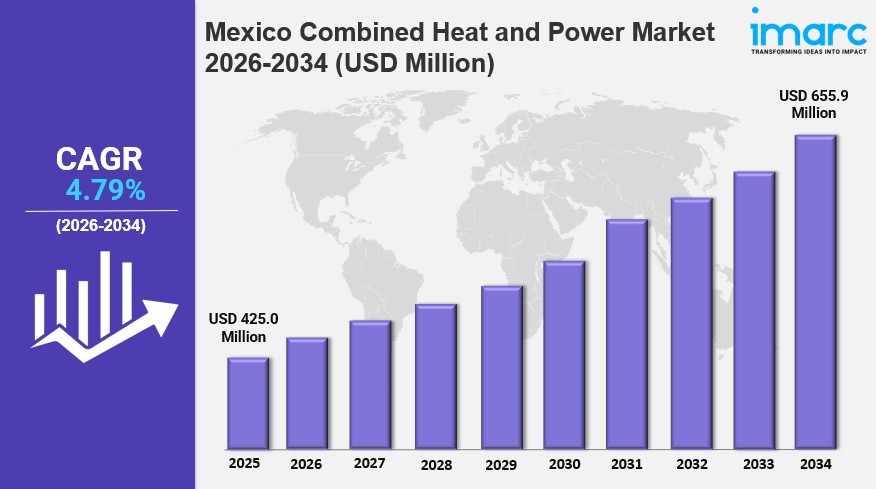
The Mexico combined heat and power market size reached USD 425.0 Million in 2025 and is projected to reach USD 655.9 Million by 2034, exhibiting a CAGR of 4.79% during 2026–2034. Increasing demand for efficient energy, availability of abundant natural gas resources, supportive government policies, and rapid industrialization are among the key factors accelerating market growth.

In 2026, the Mexico combined heat and power market growth is being fueled by aging infrastructure, high electricity costs, and the ongoing need for energy security. Growing integration of CHP systems with renewable energy sources and continued technological advancements are further strengthening adoption of combined heat and power solutions across industrial, commercial, and residential applications nationwide.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 425.0 Million
  • Projected Size (2034): USD 655.9 Million
  • Growth Rate: CAGR of 4.79%

Explore Opportunities in the Mexico Combined Heat and Power Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-combined-heat-power-market/requestsample

Mexico Combined Heat and Power Market Growth: Key Trends and Market Insights

Rising demand for secure and reliable energy solutions continues to be a key factor driving market growth, as industries and businesses increasingly focus on reducing operational costs while ensuring compliance with green energy certifications. CHP systems generate electricity and useful thermal energy from the same fuel source, offering a considerable boost to market growth, while also enabling the consistent power supply that industrial operations require to improve operational efficiency.

Mexico’s abundant natural gas resources significantly contribute to CHP market growth, as natural gas remains a key fuel for CHP systems due to its efficiency and lower environmental impact compared to other fossil fuels. The country’s extensive natural gas reserves provide a stable, cost-effective fuel source for CHP installations, reducing dependency on imported fuels and enhancing energy security, while also lowering operational costs across manufacturing, commercial, and residential applications. Ongoing government efforts to expand natural gas pipelines and distribution networks further support CHP adoption.

Government incentives and policies continue to play a crucial role in driving CHP adoption in Mexico, as the government has implemented tax benefits, subsidies, and grants for businesses investing in CHP technology, aligned with broader energy efficiency and carbon emission reduction goals. In September 2024, ContourGlobal completed the refinancing of a 518 MW portfolio of highly efficient natural gas-fired CHP cogeneration plants in Mexico, securing USD 525 Million in senior secured debt with Allianz Capital Partners as the sole institutional investor, reflecting continued investor confidence in the country’s CHP infrastructure.

Speak to An Analyst: https://www.imarcgroup.com/request?type=report&id=24627&flag=C

Mexico Combined Heat and Power Market Segmentation Analysis

The Mexico combined heat and power market is segmented by fuel type, application, and region, offering a comprehensive view of energy source preferences, end-use demand, and regional dynamics across the country.

Breakup by Fuel Type

  • Natural Gas: The leading fuel type, favored for its efficiency, lower environmental impact, and Mexico’s abundant domestic reserves that support stable, cost-effective CHP installations.
  • Coal: Continues to serve select industrial applications, though its share is gradually declining amid growing environmental and regulatory pressures.
  • Oil: Used in specific CHP installations where natural gas infrastructure access remains limited.
  • Others: Includes additional fuel sources such as biomass and renewable inputs supporting diversified CHP energy generation.

Breakup by Application

  • Industrial and Utilities: The leading application segment, driven by manufacturing, chemical, and processing industries seeking reliable, cost-effective power and thermal energy for continuous operations.
  • Commercial: Includes hotels, hospitals, and commercial complexes adopting CHP systems to reduce energy costs and improve reliability.
  • Residential: A smaller but growing segment as awareness of energy efficiency and cost savings expands among residential developments.

Breakup by Region

  • Northern States: Benefits from proximity to natural gas infrastructure and a strong industrial and manufacturing base driving CHP adoption.
  • Central States: The country’s primary economic hub, hosting significant industrial and commercial CHP installations.
  • Southern States: Growing industrial investment and infrastructure development are gradually expanding CHP adoption in the region.

Key Challenges and Growth Opportunities in the Mexico Combined Heat and Power Market

The Mexico combined heat and power market faces several challenges that could affect its growth, including high upfront capital costs for CHP installation, aging energy infrastructure that requires substantial investment to support modern systems, and the technical complexity of integrating CHP systems with renewable energy sources. Additionally, fluctuating natural gas prices and evolving regulatory requirements can create uncertainty for long-term investment planning.

Despite these challenges, the market offers significant growth opportunities driven by continued government support for energy efficiency initiatives, rising electricity costs that make CHP systems increasingly cost-competitive, and growing integration with renewable energy infrastructure. The expansion of natural gas pipeline networks and rising industrial investment in energy self-sufficiency are expected to accelerate market development. Companies investing in IoT-based predictive maintenance and renewable-integrated CHP solutions will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The Mexico combined heat and power market features a competitive structure comprising established global energy technology providers and specialized CHP system operators. Companies are focusing on strategic refinancing, portfolio expansion, and technological innovation to strengthen their positioning and capitalize on Mexico’s growing demand for reliable, efficient energy solutions.

Market participants are investing in high-efficiency natural gas-fired cogeneration technology and securing institutional capital to expand and optimize their CHP portfolios. Strategic initiatives such as major refinancing transactions and portfolio-level investments are enabling companies to strengthen their financial positioning and support continued expansion of CHP infrastructure across Mexico’s industrial and commercial sectors.

Key Players in the Mexico Combined Heat and Power Market

  • ContourGlobal: Completed the refinancing of a 518 MW portfolio of natural gas-fired CHP cogeneration plants in Mexico, securing USD 525 Million in senior secured debt with Allianz Capital Partners.
  • Mitsubishi Hitachi Power Systems, Ltd.: A global provider of CHP technology and power generation equipment supporting industrial cogeneration installations across Mexico.
  • Siemens Energy AG: A leading global energy technology company offering CHP turbines and cogeneration solutions serving industrial and utility customers in Mexico.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Yogurt Market Size, Share, Trends & Growth Report 2034

Mexico Yogurt Market Size, Share, Trends & Growth Report 2034

IMARC Group has recently released a new research study titled “Mexico Yogurt Market Size, Share, Trends and Forecast by Product Type, Flavor, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Yogurt Market Size & Share 2026-2034

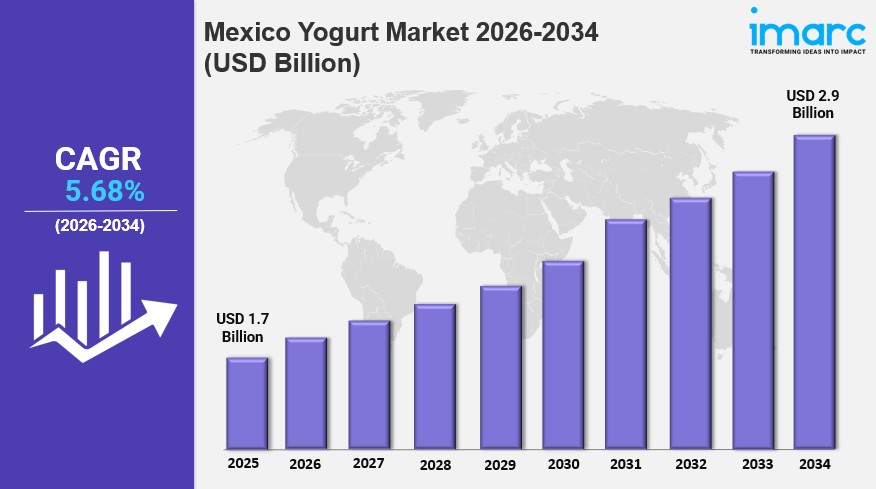
The Mexico yogurt market size reached USD 1.7 Billion in 2025 and is projected to reach USD 2.9 Billion by 2034, expanding at a CAGR of 5.68% during 2026-2034. In 2026, the market continues to gain momentum, driven by increasing demand for healthy, functional, and organic options across Mexico’s diversifying dairy landscape.

Growth in 2026 is further supported by the rising popularity of flavored and drinkable yogurts, particularly among younger consumers, while clean-label preferences continue to boost adoption of organic and preservative-free products. These dynamics are expected to strengthen the Mexico yogurt market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 1.7 Billion
  • Projected Market Size (2034): USD 2.9 Billion
  • Growth Rate: CAGR of 5.68% (2026-2034)

Explore Opportunities in the Mexico Yogurt Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-yogurt-market/requestsample

Key Growth Drivers and Trends in the Mexico Yogurt Market

Growth in the Mexico yogurt market is being driven by rising demand for healthy and functional foods, as Mexican consumers become increasingly health-conscious and look for products offering added health benefits. Yogurts with added probiotics, high protein content, and low sugar levels are gaining popularity, with probiotic variants appealing to consumers seeking digestive health benefits, high-protein options embraced by fitness enthusiasts, and low-sugar versions attracting those looking to reduce sugar intake without sacrificing taste.

One of the leading Mexico yogurt market trends is the rapid expansion of flavored and drinkable yogurt segments, particularly among younger and urban consumers seeking convenience and diverse taste experiences. Flavored yogurts in fruity and dessert-inspired varieties are attracting consumers looking for both taste and health benefits, while drinkable formats are seeing significant growth for on-the-go consumption, with their portability making them especially popular among millennials and Gen Z as brands continue innovating with new flavors, textures, and packaging.

Another key factor supporting Mexico yogurt market growth is the rising preference for organic and natural yogurt products among increasingly health-conscious consumers. These yogurts, free from artificial additives, preservatives, and chemicals, cater to growing demand for clean-label products, with organic options made from milk produced without synthetic pesticides or fertilizers particularly attractive to consumers seeking environmentally friendly and sustainable choices, further reflected in LALA’s November 2024 launch of LALA Gold, a high-protein yogurt line targeting health-conscious consumers.

Speak to An Analyst: https://www.imarcgroup.com/request?type=report&id=32945&flag=C

Mexico Yogurt Industry Segmentation Insights

Breakup by Product Type:

  • Set Yogurt: Represents a traditional format widely consumed across Mexican households.
  • Greek Yogurt: Benefits from rising demand for high-protein, thick-textured yogurt options.
  • Yogurt Drinks: Gaining rapid popularity for on-the-go consumption among younger consumers.
  • Frozen Yogurt: Serves the dessert and treat segment with a lighter, yogurt-based alternative.
  • Others: Includes additional yogurt formats catering to diverse consumer preferences.

Breakup by Flavor:

  • Strawberry Blend: A popular fruity option appealing to a broad consumer base.
  • Vanilla: Remains a classic, widely favored flavor choice.
  • Plain: Serves consumers seeking a versatile, unsweetened base for various uses.
  • Strawberry: Continues to be a top-selling fruit flavor across the market.
  • Peach: Offers a popular alternative fruit flavor option.
  • Others: Includes additional flavor varieties catering to diverse taste preferences.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Provides broad retail access and extensive product variety for everyday yogurt purchases.
  • Convenience Stores: Serves quick, on-the-go purchase occasions.
  • Specialty Stores: Offers curated selections, including organic and premium yogurt options.
  • Online Stores: Growing steadily alongside expanding e-commerce grocery adoption.
  • Others: Includes additional retail formats supporting yogurt distribution.

Breakup by Region:

  • Northern Mexico: Benefits from higher income levels and strong demand for premium and functional yogurt products.
  • Central Mexico: Holds a significant share supported by dense urban population and extensive retail infrastructure.
  • Southern Mexico: An emerging region with growing yogurt consumption as retail networks expand.
  • Others: Comprises smaller regional markets experiencing gradual growth in yogurt demand.

Key Challenges and Growth Opportunities in the Mexico Yogurt Market

The Mexico yogurt market faces challenges including rising raw material costs, particularly for milk and other dairy inputs, along with intense competition among domestic and international brands. Maintaining product freshness and cold-chain logistics across diverse retail channels also requires sustained investment, particularly as demand for premium and specialty yogurt formats continues to grow.

Despite these challenges, the market offers considerable growth opportunities driven by rising demand for functional, high-protein, and probiotic yogurt products, along with growing consumer preference for organic and clean-label options. Continued innovation in flavored and drinkable formats, along with expanding e-commerce distribution, is expected to create substantial opportunities for long-term growth in the Mexico yogurt market.

Competitive Landscape

The Mexico yogurt market is competitive, comprising domestic dairy producers and international brands focused on product innovation, functional formulation, and expanding distribution networks. Companies are investing in high-protein, probiotic, and organic product lines to differentiate their offerings, while pursuing strategic partnerships and marketing initiatives to strengthen brand loyalty and capture the growing base of health-conscious Mexican consumers.

Recent Developments in the Mexico Yogurt Market

  • November 2024: LALA, a Mexican dairy brand, announced the launch of LALA Gold, a high-protein yogurt aimed at health-conscious consumers, available in drinkable (25g protein, 6g fiber) and spoonable (20g protein) formats with no added sugar across five flavors.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Calibration Services Market Size to Hit USD 115.3 Million by 2034: Trends & Forecast

Mexico Calibration Services Market Size to Hit USD 115.3 Million by 2034: Trends & Forecast

IMARC Group has recently released a new research study titled “ Mexico Calibration Services Market Size, Share, Trends and Forecast by Service Type, Calibration Type, End-Use Industry, and Region, 2026-2034″, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Calibration Services Market Size & Share 2026-2034

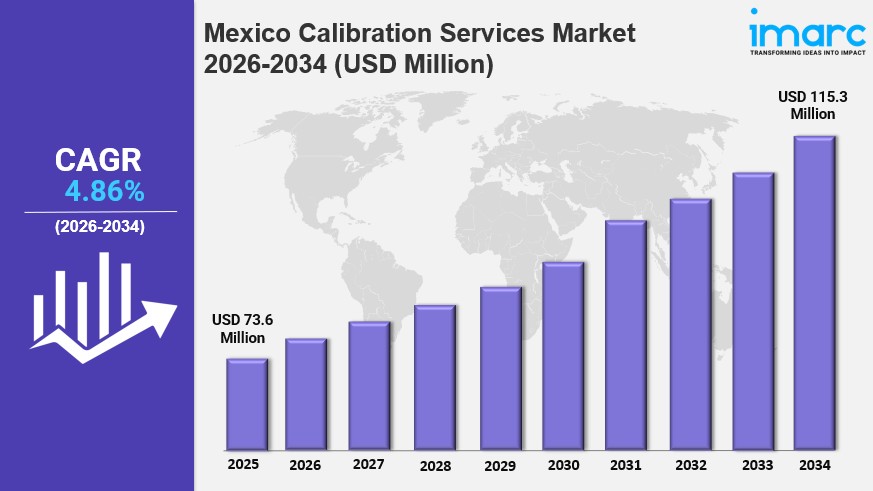
The Mexico calibration services market size reached USD 73.6 Million in 2025 and is projected to reach USD 115.3 Million by 2034, expanding at a CAGR of 4.86% during 2026-2034. In 2026, the market continues to gain momentum, driven by increasing demand for calibration services across manufacturing and industrial sectors, alongside the growth of accredited calibration laboratories and continued technological advancements.

Growth in 2026 is further reinforced by the expansion of industries such as automotive, aerospace, pharmaceuticals, and electronics, which continue to require accurate measurement and testing instruments. These dynamics are expected to strengthen the Mexico calibration services market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 73.6 Million
  • Projected Market Size (2034): USD 115.3 Million
  • Growth Rate: CAGR of 4.86% (2026-2034)

Explore Opportunities in the Mexico Calibration Services Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-calibration-services-market/requestsample

Key Growth Drivers and Trends in the Mexico Calibration Services Market

Growth in the Mexico calibration services market is being driven by the rising call for accuracy and quality control in manufacturing and industrial service sectors, as industries like automotive, aerospace, pharmaceuticals, and electronics grow and require accurate measurement and testing instruments. In July 2024, SGS expanded its Mexico labs with new testing solutions for automotive, furniture, and toys, including BIFMA, ASTM F963, and upcoming VOC testing for the automotive sector, reflecting the market’s response to strict regulations and international quality standards such as ISO/IEC 17025.

One of the leading Mexico calibration services market trends is the growth of accredited calibration laboratories, as businesses increasingly opt for ISO/IEC 17025 accreditation to validate technical competence and reliability. In December 2024, UL Solutions expanded its Mexico lab to enhance testing for consumer tech, automotive, and cable products, becoming a certified Volkswagen de Mexico partner for automotive component testing, highlighting the growing appeal of accredited laboratories to businesses in the health, automotive, and aerospace sectors.

Another key factor supporting Mexico calibration services market growth is the proliferation of advanced calibration technologies, including automated calibration systems, wireless calibration tools, and digital documentation solutions that are improving efficiency, reducing human errors, and enhancing traceability. The integration of IoT and artificial intelligence into calibration processes is enabling real-time monitoring and predictive maintenance, while remote and on-site calibration services continue gaining traction as businesses seek flexible, cost-effective solutions to minimize equipment downtime.

Mexico Calibration Services Industry Segmentation Insights

Breakup by Service Type:

  • In-House: Reflects organizations maintaining internal calibration capabilities to support ongoing operational and compliance needs.
  • OEMs: Represents calibration services provided directly by original equipment manufacturers for their own instruments and systems.
  • Third-Party Service: Benefits from rising demand for independent, accredited calibration providers ensuring compliance with international standards.

Breakup by Calibration Type:

  • Electrical: Supports calibration of electrical measurement instruments critical to manufacturing and industrial operations.
  • Mechanical: Covers calibration of mechanical measurement tools and equipment across diverse industrial applications.
  • Thermodynamic: Addresses calibration needs for temperature and thermal measurement instruments.
  • Physical/Dimensional: Supports precision measurement calibration critical to manufacturing quality control.
  • Others: Includes additional specialized calibration types serving niche industrial needs.

Breakup by End-Use Industry:

  • Electronics Manufacturing: A leading end-use segment driven by the need for precision measurement in electronics production.
  • Communication: Relies on calibration services to ensure accuracy and reliability of telecommunications equipment.
  • Aerospace and Defense: Depends on stringent calibration standards to meet safety and regulatory requirements.
  • Automotive: Benefits from growing calibration demand tied to Mexico’s expanding vehicle manufacturing base.
  • Others: Includes additional industries relying on calibration services to support quality and compliance.

Breakup by Region:

  • Northern Mexico: Benefits from a strong manufacturing and industrial base driving calibration services demand.
  • Central Mexico: Holds a significant share supported by dense industrial infrastructure and multinational manufacturing operations.
  • Southern Mexico: An emerging region with growing industrial development supporting calibration services adoption.
  • Others: Comprises smaller regional markets experiencing gradual growth in calibration services demand.

Key Challenges and Growth Opportunities in the Mexico Calibration Services Market

The Mexico calibration services market faces challenges including the need for continuous investment in advanced calibration technologies and accredited laboratory infrastructure to meet evolving international standards. Ensuring a sufficient supply of skilled metrology professionals also remains an important consideration as demand for precision calibration services continues to grow.

Despite these challenges, the market offers considerable growth opportunities driven by expanding manufacturing and industrial sectors, rising adoption of Industry 4.0 technologies, and growing demand from foreign multinationals requiring accredited certified calibration services to comply with global supply chain standards. Continued investment in metrology laboratories, on-site calibration solutions, and digital calibration technology is expected to create substantial opportunities for long-term growth in the Mexico calibration services market.

Competitive Landscape

The Mexico calibration services market is competitive, with established testing and certification companies and specialized calibration providers focusing on laboratory accreditation, technological innovation, and strategic partnerships to strengthen their market position. Companies are increasingly expanding local laboratory capacity and forming certification partnerships with major manufacturers to meet growing demand for accredited, high-precision calibration services across the automotive, electronics, and aerospace sectors.

Recent Developments in the Mexico Calibration Services Market

  • February 2025: IndySoft, a leader in calibration and asset management software, partnered with ADS Mexico to expand its presence in the growing Mexican market, enhancing local expertise and ensuring seamless implementation, customer support, and training.
  • December 2024: UL Solutions expanded its Mexico lab to enhance testing for consumer tech, automotive, and cable products, becoming a certified Volkswagen de Mexico partner for automotive component testing.
  • July 2024: SGS expanded its Mexico labs with new testing solutions for automotive, furniture, and toys, including BIFMA, ASTM F963, and upcoming VOC testing for the automotive sector.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Whiskey Market Size Worth USD 27.23 Billion by 2034 | CAGR: 4.32%: IMARC Group

United States Whiskey Market Size Worth USD 27.23 Billion by 2034 | CAGR: 4.32%: IMARC Group

IMARC Group has recently released a new research study titled “United States Whiskey Market Size, Share, Trends and Forecast by Product Type, Quality, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Whiskey Market Size & Forecast 2026-2034

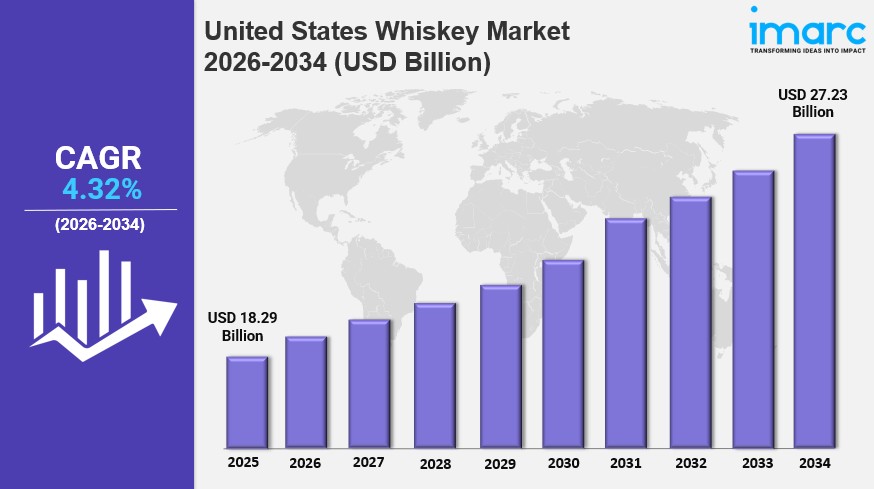
The United States whiskey market size reached USD 18.29 Billion in 2025 and is projected to reach USD 27.23 Billion by 2034, expanding at a CAGR of 4.32% during 2026-2034. In 2026, the market continues to be shaped by evolving consumer tastes, rising disposable incomes, and a broader cultural shift toward premiumization and authentic craft experiences, with growing enthusiasm for artisanal, small-batch, and heritage-rich expressions reshaping purchasing behavior across demographic groups.

Growth in 2026 is further supported by whiskey’s deepening integration into cocktail culture, along with expanding retail and digital channels that are broadening consumer access nationwide. Continued investment in barrel finishing, cask experimentation, and limited-edition releases, combined with a thriving whiskey tourism ecosystem, is expected to strengthen the United States whiskey market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 18.29 Billion
  • Projected Market Size (2034): USD 27.23 Billion
  • Growth Rate: CAGR of 4.32% (2026-2034)
  • Leading Product Type (2025): American Whiskey, holding a 55.2% share
  • Leading Quality Tier (2025): Premium, holding a 42.5% share
  • Leading Distribution Channel (2025): Off-Trade, holding a 68.3% share
  • Leading Region (2025): South, holding a 28.6% share

Get Insights on the United States Whiskey Market: Access the IMARC Sample Report: https://www.imarcgroup.com/united-states-whiskey-market/requestsample

Key Growth Drivers and Trends in the United States Whiskey Market

Growth in the United States whiskey market is being driven by rising premiumization as consumers increasingly prioritize quality, authenticity, and distinctive flavor experiences over volume. Demand for small-batch, single-barrel, and age-stated expressions has grown considerably, with buyers willing to pay more for brands that demonstrate transparency in production and sourcing, fostering a cultural shift toward connoisseurship and deeper brand loyalty.

One of the leading United States whiskey market trends is the expanding role of whiskey within cocktail culture and mixology, as bartenders experiment with rye, bourbon, and Tennessee whiskey styles to create layered flavor profiles. In August 2025, Jack Daniel’s launched Tennessee Blackberry nationwide, blending Old No. 7 Tennessee Whiskey with blackberries to target mixology and casual cocktail consumers, reflecting the category’s broader push toward flavor innovation and lifestyle-driven consumption.

Another key factor supporting United States whiskey market growth is ongoing innovation in barrel finishing and cask experimentation. Distilleries are increasingly maturing whiskey in non-traditional casks such as port, sherry, rum, and wine barrels to introduce fruit-forward, spiced, or botanical flavor profiles. In October 2025, Angel’s Envy released its first age-stated 10-year bourbon finished in port wine barrels nationwide, illustrating how cask experimentation is helping brands differentiate on crowded retail shelves and attract both collectors and new whiskey enthusiasts.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=10458&flag=C

United States Whiskey Industry Segmentation Insights

Breakup by Product Type:

  • American Whiskey: Leads the market with a 55.2% share in 2025, driven by bourbon’s deep cultural roots, heritage identity, and strict regulated production standards.
  • Irish Whiskey: Valued for its smooth, triple-distilled character, appealing to consumers seeking lighter, easy-drinking expressions.
  • Scotch Whiskey: A premium category recognized for regional distillation heritage and strong appeal among connoisseurs and gifting occasions.
  • Canadian Whiskey: Known for smooth, versatile blends favored in both neat consumption and cocktails.
  • Others: Includes additional domestic and international whiskey styles gaining traction with U.S. consumers.

Breakup by Quality:

  • Premium: Leads with a 42.5% share in 2025, striking a balance between elevated drinking experiences and accessible price positioning.
  • High-End Premium: Appeals to consumers seeking refined taste profiles and stronger brand credentials.
  • Super Premium: Represents the top tier of the market, favored by collectors and connoisseurs for rare, aged expressions.

Breakup by Distribution Channel:

Off-Trade

  • Supermarkets and Hypermarkets: Offer extensive whiskey selections, competitive pricing, and convenient shopping for everyday consumers.
  • Discount Stores: Attract price-conscious buyers through value-oriented whiskey brands and frequent promotional offers.
  • Online Stores: Growing rapidly with convenient home delivery, premium product availability, and expanding e-commerce adoption.
  • Others: Includes convenience stores, specialty liquor retailers, and warehouse clubs serving diverse consumer preferences.

On-Trade

  • Restaurants and Bars: Drive premium whiskey consumption through cocktails, tastings, and curated dining experiences.
  • Liquor Stores: Provide premium, imported, and craft whiskey brands with expert recommendations and wider product assortments.
  • Others: Includes hotels, lounges, clubs, casinos, and entertainment venues offering premium whiskey experiences.

Breakup by Region:

  • South: Holds the largest share at 28.6% in 2025, anchored by Kentucky and Tennessee’s status as the historic heartland of American bourbon and Tennessee whiskey production.
  • Northeast: Benefits from strong retail infrastructure and a mature spirits consumer base.
  • Midwest: Shows steady demand supported by an expanding craft distillery scene.
  • West: Driven by growing interest in premium and craft whiskey among urban consumers.

Key Challenges and Growth Opportunities in the United States Whiskey Market

The United States whiskey market faces challenges including regulatory complexity across federal and state alcohol control laws, three-tier distribution mandates, and evolving trade policies that weigh disproportionately on smaller craft producers. Inventory oversupply from rapid distillery capacity expansion during peak demand years has also created downward pricing pressure, while international trade barriers and tariff volatility continue to create revenue uncertainty for distilleries pursuing global distribution.

Despite these challenges, the market offers significant growth opportunities driven by deepening premiumization, expanding craft distillery innovation, and rising consumer enthusiasm for experiential consumption. Growth in e-commerce and direct-to-consumer channels, illustrated by Frey Ranch Distillery’s February 2026 launch of its ‘Harvest the Savings’ subscription service, alongside a strengthening whiskey gifting culture, is expected to open substantial new revenue streams and support long-term expansion across the United States whiskey market.

Competitive Landscape

The United States whiskey market features a highly competitive landscape shaped by large multinational spirits corporations, established regional distilleries, and a rapidly growing craft producer ecosystem. Established players leverage extensive distribution networks and strong brand equity, while craft distilleries compete through artisanal differentiation and localized consumer engagement. Competition is particularly intense within premium and super-premium tiers, where innovation in aging techniques and limited-edition releases drives meaningful brand distinction, and growing e-commerce penetration is enabling smaller producers to build direct-to-consumer relationships.

Recent Developments in the United States Whiskey Market

  • March 2026: Evan Williams, produced by Heaven Hill Distillery, launched its first-ever blackberry-flavored whiskey, blending classic straight bourbon with fresh blackberry, available nationwide at $14.99 and targeting sipping and cocktail occasions.
  • October 2025: Angel’s Envy released its first age-stated 10-year bourbon finished in port wine barrels nationwide, highlighting cask experimentation to create richer, wine-influenced flavor profiles.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Application Security Market Size to Reach USD 440.3 Million by 2034

Mexico Application Security Market Size to Reach USD 440.3 Million by 2034

IMARC Group has recently released a new research study titled “ Mexico Application Security Market Size, Share, Trends and Forecast by Component, Type, Testing Type, Deployment Mode, Organization Size, Industry Vertical, and Region, 2026-2034″, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

Mexico Application Security Market Size & Forecast 2026-2034

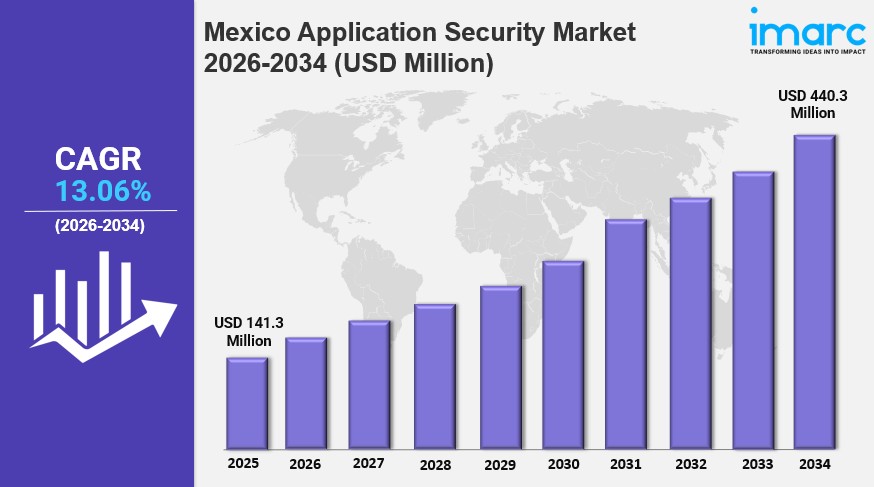
The Mexico application security market is experiencing rapid growth, driven by the expansion of cloud-native platforms, mobile-first strategies, and remote work adoption across the country. The Mexico application security market size reached USD 141.3 Million in 2025 and is expected to grow to USD 440.3 Million by 2034, exhibiting a CAGR of 13.06% during 2026–2034. The market’s expansion is supported by agile-integrated security practices, DevSecOps collaboration, region-specific compliance mandates, and the growing adoption of AI-based anomaly detection and managed security services.

In 2026, Mexico’s accelerating digitization across government services, financial institutions, and consumer-facing industries continues to transform how applications are built and deployed. Cloud-native development, driven by demand for scalable and responsive digital platforms, has expanded the attack surface, prompting organizations to invest further in application security to protect distributed environments, APIs, and third-party components. Moreover, rising sophistication of application-layer cyberattacks, growing use of web application firewalls, software composition analysis, and real-time protection tools, along with increasing cybersecurity training and ethical hacking initiatives, are enhancing innovation within the application security ecosystem. The continued expansion of secure access protocols and national data protection policies is expected to further support the Mexico application security market throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 141.3 Million
  • Projected Market Size (2034): USD 440.3 Million
  • Growth Rate: CAGR of 13.06% (2026–2034)

Explore Growth Opportunities in the Mexico Application Security Market: Grab IMARC Sample Report for evaluation: https://www.imarcgroup.com/mexico-application-security-market/requestsample

Key Trends Driving Growth in the Mexico Application Security Market

The Mexico application security market growth is being driven by the expansion of digital services and cloud-native development across government, financial, and consumer-facing industries. As mobile-first strategies become prevalent across sectors such as fintech, retail, and logistics, securing applications from the initial development stage has become a central requirement, further intensified by the rise in remote work. Developers and security teams across Mexico are increasingly implementing real-time threat modeling, secure coding practices, and automated vulnerability scans as integral parts of build processes and deployment automation.

One of the leading trends in the Mexico application security market is the rise in cybercrime and increased sectoral vulnerability, particularly in banking, healthcare, and education. Attacks exploiting application-layer vulnerabilities such as injection flaws, broken authentication, and insecure configurations have become more frequent and sophisticated, intensifying investments in Web Application Firewalls (WAFs), Runtime Application Self-Protection (RASP), and Software Composition Analysis (SCA).

Another significant factor supporting market growth is the localization of cybersecurity operations within Mexico. For instance, in March 2024, Eviden, an Atos Group company, launched its 17th global Security Operations Center (SOC) in Monterrey, Mexico, leveraging its AIsaac Cyber Mesh AI platform to deliver 24/7/365 threat detection, incident analysis, and proactive threat containment with sovereign data localization options, reflecting the evolving trends shaping the Mexico application security market.

Speak to An Analyst: https://www.imarcgroup.com/request?type=report&id=33474&flag=C

Mexico Application Security Industry Segmentation Insights

Breakup by Component:

  • Solution
  • Services

The report provides a comprehensive market segmentation and detailed analysis based on component, covering solutions and services, reflecting the growing demand for both software-based security tools and professional support services across Mexican enterprises.

Breakup by Type:

  • Web Application Security
  • Mobile Application Security

The report provides a comprehensive market segmentation and detailed analysis based on type, including web application security and mobile application security, driven by the rapid expansion of mobile-first strategies across fintech, retail, and logistics sectors.

Breakup by Testing Type:

  • Static Application Security Testing (SAST)
  • Dynamic Application Security Testing (DAST)
  • Interactive Application Security Testing (IAST)
  • Runtime Application Self-Protection (RASP)

The report provides a comprehensive market segmentation and detailed analysis based on testing type, including SAST, DAST, IAST, and RASP, which are increasingly deployed to defend applications in real time amid the extensive use of open-source components and third-party libraries.

Breakup by Deployment Mode:

  • On-premises
  • Cloud-based

The report provides a comprehensive market segmentation and detailed analysis based on deployment mode, covering on-premises and cloud-based solutions, with cloud-based deployment gaining momentum as organizations adopt scalable, distributed digital platforms.

Breakup by Organization Size:

  • Large Enterprises
  • Small and Medium-sized Enterprises

The report provides a comprehensive market segmentation and detailed analysis based on organization size, including large enterprises and small and medium-sized enterprises, with mid-sized firms increasingly seeking cost-effective, locally supported, and compliant application security solutions.

Breakup by Industry Vertical:

  • BFSI
  • Healthcare
  • IT and Telecom
  • Manufacturing
  • Government and Public Sector
  • Retail and E-Commerce
  • Others

The report provides a comprehensive market segmentation and detailed analysis based on industry vertical, including BFSI, healthcare, IT and telecom, manufacturing, government and public sector, retail and e-commerce, and others, with BFSI and healthcare facing heightened application-layer security demands amid rising cyberattack sophistication.

Breakup by Region:

  • Northern Mexico
  • Central Mexico
  • Southern Mexico
  • Others

The report provides a comprehensive market segmentation and detailed analysis based on region, covering Northern Mexico, Central Mexico, Southern Mexico, and other regional markets, capturing the geographic distribution of digital transformation and cybersecurity investment across the country.

Key Challenges and Growth Opportunities in the Mexico Application Security Market

The Mexico application security market faces several challenges despite its strong growth potential. The rising sophistication of application-layer cyberattacks, a persistent gap between rapid technology adoption and qualified cybersecurity talent, and the complexity of securing distributed cloud environments and third-party components create ongoing obstacles for organizations. Additionally, evolving national data protection policies and cross-border data exchange regulations require continuous adaptation of compliance strategies.

At the same time, significant growth opportunities continue to emerge across the market. The growing focus on region-specific threat intelligence and local compliance mandates, expanding cybersecurity education and ethical hacking initiatives, rising adoption of AI-based anomaly detection and behavioral analytics, and increasing integration of application security with physical and operational security platforms are expected to accelerate innovation and support sustained market expansion over the forecast period.

Competitive Landscape

The competitive landscape of the Mexico application security market is characterized by the presence of global cybersecurity firms, managed security service providers, and specialized application security vendors. Market participants are focusing on localizing cybersecurity operations, expanding managed detection and response capabilities, and building AI-powered threat intelligence platforms to strengthen their market presence. Investments in security operations centers, sovereign data localization, and carbon-neutral service offerings continue to drive competition and support long-term market growth.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Pharmacy Market Size, Growth, Latest Trends and Forecast 2026-2034

United States Pharmacy Market Size, Growth, Latest Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “United States Pharmacy Market Report by Product Type (Prescription, OTC), Pharmacy Type (Hospital Pharmacy, Retail Pharmacy, ePharmacy, and Others), Ownership (Independent, Chain), and Region 2026-2034”, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

United States Pharmacy Market Size and Growth Forecast (2026-2034)

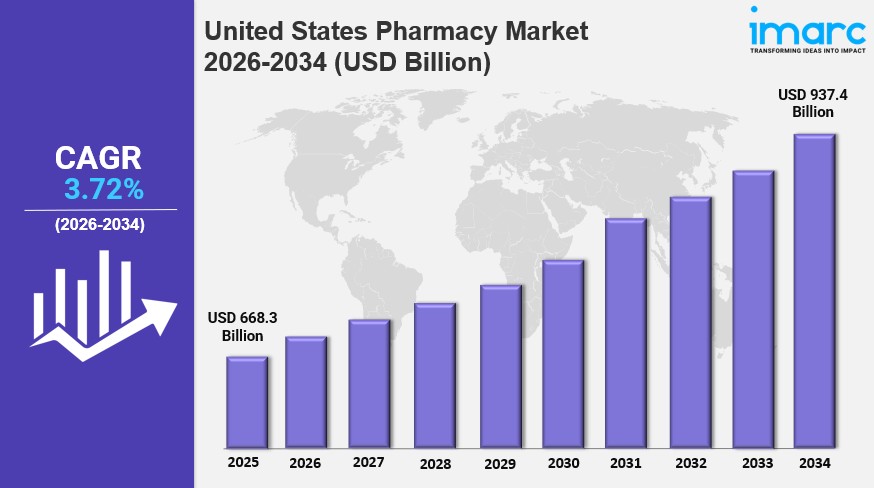
The United States pharmacy market size reached USD 668.3 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 937.4 Billion by 2034, exhibiting a growth rate (CAGR) of 3.72% during 2026-2034. The market is being driven by the increasing incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions, which is leading to higher demand for medications across the country.

The United States pharmacy market growth is also supported by a growing and aging population, rising healthcare awareness, and continuous advancements in pharmaceutical sciences and drug development. As the elderly population expands, demand for a broader range of medications and healthcare services is increasing correspondingly. The expanding role of e-commerce and digital health solutions, including online pharmacies and telehealth platforms, is further improving convenient access to pharmaceutical products. As pharmacists take on a more patient-centered role in immunizations, chronic disease management, and medication counseling, continued innovation in specialty pharmacy services and digital prescription fulfillment is expected to sustain long-term market growth throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 668.3 Billion
  • Projected Size (2034): USD 937.4 Billion
  • Growth Rate: CAGR of 3.72%

Analyze the United States Pharmacy Market: Download the IMARC Sample Report for Insights: https://www.imarcgroup.com/united-states-pharmacy-market/requestsample

United States Pharmacy Market Trends and Growth Drivers

The United States pharmacy market growth is being driven by the increasing prevalence of chronic diseases, a rapidly aging population, and rising demand for prescription medications and healthcare services. Growing healthcare expenditure, expanded access to health insurance, and the increasing adoption of preventive care are encouraging consumers to rely on retail, hospital, and online pharmacies for convenient access to medicines and wellness products. In addition, the growing use of specialty drugs and biologics is contributing to sustained market expansion.

One of the leading United States pharmacy market trends is the rapid digital transformation of pharmacy services through e-prescriptions, telepharmacy, and online prescription fulfillment. Pharmacies are integrating artificial intelligence, automated dispensing systems, and digital health platforms to improve operational efficiency, enhance medication adherence, and provide personalized patient care. The expansion of home delivery services and mobile pharmacy applications is also improving convenience and accessibility for consumers.

Another significant United States pharmacy market trends is the growing emphasis on value-added healthcare services beyond traditional medication dispensing. Pharmacies are expanding their offerings to include immunizations, chronic disease management, health screenings, medication therapy management, and personalized wellness programs. Continued investments in digital infrastructure, automation, and patient-centric care models, along with strategic partnerships between pharmacies and healthcare providers, are expected to support long-term United States pharmacy market growth throughout the forecast period.

United States Pharmacy Market Segmentation Analysis

Breakup by Product Type:

  • Prescription
  • OTC

The report offers a comprehensive segmentation and analysis of the market based on product type, including prescription and OTC (over-the-counter) medications.

Breakup by Pharmacy Type:

  • Hospital Pharmacy
  • Retail Pharmacy
  • ePharmacy
  • Others

The report also presents a detailed segmentation and analysis of the market based on pharmacy type, covering hospital pharmacy, retail pharmacy, ePharmacy, and other pharmacy formats.

Breakup by Ownership:

  • Independent
  • Chain

The report further provides a comprehensive segmentation and analysis of the market based on ownership, including independent and chain pharmacies.

Breakup by Regional:

  • Northeast
  • Midwest
  • South
  • West

The report also delivers a comprehensive analysis of the key regional markets, including the Northeast, Midwest, South, and West regions.

Competitive Landscape

The United States pharmacy market is highly competitive, dominated by a mix of large chain pharmacy operators, big-box and grocery retailers, and fast-growing online pharmacy providers. Competition centers on expanding clinical services, improving digital engagement, and building integrated healthcare offerings that combine prescription fulfillment with in-store clinics and telehealth partnerships. Companies are investing in omnichannel capabilities, prescription delivery, and specialty pharmacy services to differentiate their offerings and strengthen customer retention across an increasingly consolidated retail pharmacy landscape.

Key Players

  • CVS Health Corporation — Operates one of the largest retail pharmacy networks in the U.S., integrating pharmacy services with MinuteClinic and its broader healthcare business.
  • Walgreens — A major retail pharmacy chain that recently transitioned to private ownership and continues to operate a large national store footprint.
  • Walmart Inc. — Leverages its extensive big-box store network and competitive pricing to operate a fast-growing in-store pharmacy business.
  • Costco Wholesale Corporation — Offers pharmacy services through its membership warehouse club format, emphasizing competitive drug pricing.
  • Amazon.com, Inc. (Amazon Pharmacy) — Provides online prescription fulfillment and delivery through its Amazon Pharmacy platform.
  • Albertsons Companies, Inc. — Operates in-store pharmacies across its grocery banners, serving customers alongside everyday retail shopping.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Water Purifier Market Size Hits USD 10.81 Billion by 2034

United States Water Purifier Market Size Hits USD 10.81 Billion by 2034

IMARC Group has recently released a new research study titled “United States Water Purifier Market Size, Share, Trends and Forecast by Technology Type, Distribution Channel, End User, and Region 2026-2034”, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

United States Water Purifier Market Overview 2026

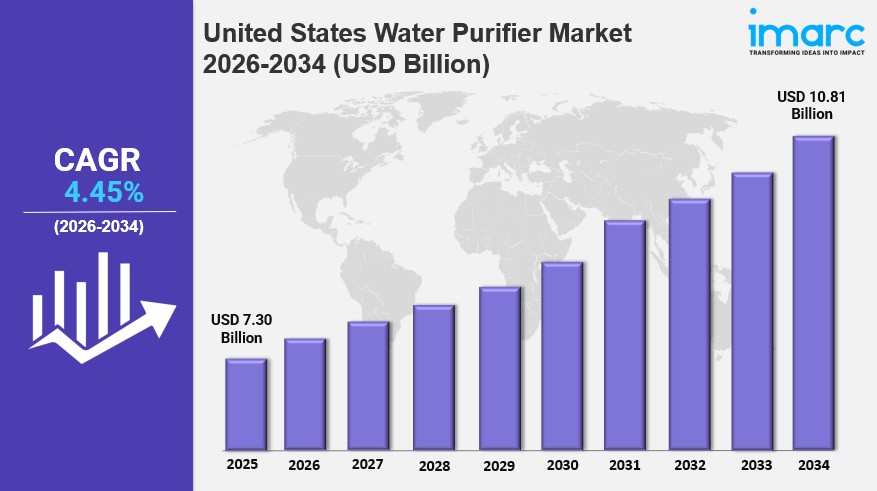
The United States water purifier market size reached USD 7.30 Billion in 2025. Looking ahead, IMARC Group projects the market to grow to USD 10.81 Billion by 2034, registering a CAGR of 4.45% during 2026–2034. Market growth is primarily driven by increasing health awareness among consumers, greater awareness about waterborne contaminants, and rising concerns over municipal water quality and toxic substances in tap water. In addition, environmental sustainability priorities and reduced reliance on single-use plastic bottles are strengthening the United States water purifier market share while accelerating adoption across different consumer segments.

In 2026, the United States water purifier market is experiencing significant transformation as manufacturers adapt to changing consumer expectations and technological advancements. Businesses are increasingly implementing smart, IoT-connected purification systems that let users monitor water quality and filter life in real time via smartphone apps. The growing popularity of reverse osmosis technology, expanding e-commerce penetration, and rising regulatory scrutiny on emerging contaminants such as PFAS is fueling United States water purifier market demand. Moreover, the integration of AI-enabled monitoring, multi-stage filtration technologies, and eco-friendly product design is improving water quality outcomes, sustainability, and customer satisfaction, supporting the market’s long-term growth.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 7.30 Billion
  • Projected Size (2034): USD 10.81 Billion
  • Growth Rate: CAGR of 4.45%

Explore Opportunities in the United States Water Purifier Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-water-purifier-market/requestsample

United States Water Purifier Market Trends and Growth Opportunities

The water purifier industry in the United States is undergoing significant transformation, driven by changing consumer behavior and rapid technological advancements. One of the key United States water purifier market trends is the rising adoption of smart water purification systems equipped with digital monitoring capabilities and mobile application connectivity. In December 2025, Culligan International announced a strategic partnership with AmeriWater to deliver advanced water purification solutions, including systems with remote monitoring and analytics, to healthcare and commercial users in North America, reflecting how major purification brands are expanding connected and data-driven offerings beyond residential applications.

The growing preference for eco-friendly filtration solutions continues to create new opportunities for manufacturers across the country. Environmental consciousness is reshaping purchasing decisions as consumers seek sustainable alternatives to bottled water consumption, with water purifiers increasingly marketed as solutions that reduce plastic waste and carbon footprint. At the same time, demand for comprehensive water treatment solutions is spurring innovation in multi-stage purification systems; in July 2025, U.S.-based Multipure launched its Aquapremier system featuring advanced Nanomesh™ filtration certified to reduce PFAS, pharmaceuticals, microplastics, bacteria, and viruses.

The United States water purifier market growth is also supported by increasing government investment in effective water treatment systems, stringent regulatory standards, and rising health and wellness lifestyle trends. In April 2024, the U.S. Environmental Protection Agency finalized the first-ever National Primary Drinking Water Regulation for multiple per- and polyfluoroalkyl substances (PFAS), setting legally enforceable limits on contaminants. Furthermore, investments in artificial intelligence, connected home appliances, and energy-efficient filtration technologies are expected to unlock new revenue streams, improve operational efficiency, and create long-term growth opportunities for the market during the forecast period.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2552&flag=C

United States Water Purifier Market Detailed Segment Analysis

Breakup by Technology Type:

  • RO Purifiers: Leads the market at 44% in 2025, driven by superior filtration efficiency in removing dissolved solids, heavy metals, and microorganisms.
  • Gravity Purifiers: Simple, low-maintenance systems commonly used for basic household water purification needs.
  • UV Purifiers: Uses ultraviolet light technology to eliminate bacteria and viruses without altering water taste or composition.
  • Sediment Filter: Removes suspended particles and sediments to improve water clarity and protect downstream filtration components.
  • Water Softener: Reduces mineral hardness to prevent scale buildup and protect household appliances and plumbing.
  • Others: Includes emerging and hybrid filtration technologies serving specialized purification needs.

Breakup by Distribution Channel:

  • Retail Stores: Leads the market at 61% in 2025, owing to consumers’ strong preference for in-person product evaluation and immediate purchase availability.
  • Direct Sales: Enables personalized consultations and installation services through direct manufacturer or dealer engagement.
  • Online: Growing channel offering convenience, broader product selection, and expanding e-commerce penetration.

Breakup by End User:

  • Household: Largest segment at 65% in 2025, propelled by increasing residential demand for safe drinking water and growing family health consciousness.
  • Commercial: Includes offices, restaurants, and hospitality businesses requiring reliable water purification solutions.
  • Industrial: Covers manufacturing and processing facilities requiring specialized water treatment for operational use.

Breakup by Region:

  • Northeast: Mature market driven by high population density and aging housing infrastructure with outdated plumbing systems.
  • Midwest: Steady demand supported by suburban growth and increasing awareness of water quality issues.
  • South: Dominates the market at 30% in 2025, attributed to higher population density, elevated water quality awareness, and growing suburban development.
  • West: Growing region driven by health-conscious consumers and strong adoption of smart, connected purification technologies.

Competitive Landscape

The United States water purifier market exhibits a moderately consolidated competitive structure with established multinational corporations commanding significant market presence alongside specialized domestic manufacturers serving niche segments. Market participants employ diverse competitive strategies including continuous product innovation, strategic brand positioning, comprehensive distribution network development, and service excellence to capture and retain market share effectively.

The competitive environment encourages technological advancement as manufacturers invest substantially in research and development initiatives to introduce differentiated features addressing evolving consumer preferences. Strategic acquisitions have emerged as prominent growth mechanisms enabling companies to expand product portfolios and geographic reach while accessing complementary technologies and distribution capabilities, supporting the continued growth of the United States water purifier market.

Recent Market Developments

In September 2025, Chinese water tech company Viomi Technology launched its MASTER M1 AI alkaline mineral water purifier on Amazon U.S., featuring AI-enabled real-time water quality and filter monitoring, a 9-stage RO system, and mineral enhancement, with filters lasting up to four years. In December 2024, Ideal Living unveiled the Wi-Fi and app-compatible AquaTru Carafe Smart, a connected water purifier allowing users to monitor water quality and filter life in real time.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201971-6302

United States Pharmacy Market Size to Hit USD 937.4 Billion by 2034 | Growth at 3.72% CAGR

United States Pharmacy Market Size to Hit USD 937.4 Billion by 2034 | Growth at 3.72% CAGR

IMARC Group has recently released a new research study titled “United States Pharmacy Market Report by Product Type, Pharmacy Type, Ownership, and Region, 2026-2034”, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

United States Pharmacy Market Size and Share 2026-2034

The United States pharmacy market size was valued at USD 668.3 Billion in 2025 and is projected to reach USD 937.4 Billion by 2034, expanding at a CAGR of 3.72% during 2026-2034. The market is experiencing steady growth driven by the rising incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions, which is fueling higher demand for medications across the country. Continued advancements in pharmaceutical sciences and expanding healthcare access are further reinforcing the market’s upward trajectory.

The United States pharmacy market share is shaped by the growing role of pharmacists in patient-centered care, including medication counseling, immunizations, and chronic disease management. Retail and chain pharmacies continue to dominate distribution, while ePharmacy platforms are rapidly gaining ground as consumers increasingly favor convenient, digitally enabled access to prescription and over-the-counter products. Rising healthcare awareness, an aging population, and expanding insurance coverage are creating sustained opportunities across hospital, retail, and online pharmacy channels nationwide.

Key Market Statistics at a Glance

  • Base Year:2025
  • Historical Years:2020–2025
  • Forecast Period:2026–2034
  • Market Size (2025):USD 668.3 Billion
  • Projected Size (2034):USD 937.4 Billion
  • Growth Rate:CAGR of 3.72%

Get Insights on the United States Pharmacy Market: Access the IMARC Sample Report: https://www.imarcgroup.com/united-states-pharmacy-market/requestsample

Key Trends Driving Growth in the United States Pharmacy Market

The United States pharmacy market growth is being fueled by a growing population and rising healthcare awareness, which are increasing overall demand for pharmaceutical products. As the population expands, medication needs rise correspondingly, placing sustained upward pressure on the pharmacy industry. Continuous advancements in medical research and drug development are also driving innovation, as pharmaceutical companies introduce novel therapies and treatment options for a wide range of conditions.

Another major factor supporting United States pharmacy market trends is the country’s aging demographic, as older adults typically require a higher volume of prescription medications and ongoing healthcare services. This demographic shift, combined with the rising prevalence of chronic diseases driven by lifestyle and environmental factors, is significantly amplifying demand for diverse pharmaceutical interventions and reinforcing long-term United States pharmacy market growth.

Additionally, the expanding role of e-commerce and digital health solutions is reshaping how consumers access pharmaceutical products and services. Online pharmacies and telehealth platforms are gaining strong traction, offering a convenient and efficient way for patients to fulfill prescriptions and manage their healthcare needs, a trend that is expected to continue shaping United States pharmacy market trends throughout the forecast period.

United States Pharmacy Industry Segmentation Insights

Breakup by Product Type:

  • Prescription: Includes medications that require a licensed healthcare provider’s authorization, representing a significant share of overall pharmacy sales due to rising chronic disease treatment needs.
  • OTC: Covers over-the-counter medications and health products that consumers can purchase without a prescription, supported by growing self-care and preventive health trends.

Breakup by Pharmacy Type

  • Hospital Pharmacy: Operates within hospital settings to dispense medications to inpatients and outpatients, playing a critical role in acute and specialty care.
  • Retail Pharmacy: Encompasses community-based and chain drugstores that serve as the primary point of access for prescription and OTC medications for most consumers.
  • ePharmacy: Refers to online platforms offering prescription and OTC medication delivery, gaining rapid traction due to convenience and expanding digital health adoption.
  • Others: Includes other pharmacy formats such as mail-order and specialty pharmacies catering to specific patient and treatment needs.

Breakup by Ownership

  • Independent: Comprises single-location, privately owned pharmacies that often provide personalized service and community-focused care.
  • Chain: Includes multi-location pharmacy businesses operating under a common brand, benefiting from scale, purchasing power, and broader geographic reach.

Breakup by Region

  • Northeast: A key regional market supported by dense healthcare infrastructure and strong insurance coverage.
  • Midwest: A major contributor to national pharmacy demand, driven by widespread retail pharmacy networks and steady chronic disease prevalence.
  • South: The largest regional market, benefiting from a large population base and expanding healthcare access.
  • West: A dynamic region shaped by strong digital health adoption and growing ePharmacy penetration.

Major Challenges and Future Opportunities in the United States Pharmacy Market

The United States pharmacy market faces several challenges, including rising prescription drug costs, complex reimbursement structures, and increasing regulatory scrutiny around drug pricing and dispensing practices. Workforce shortages among licensed pharmacists and growing competition from large retail and online pharmacy chains are also creating operational pressures for smaller, independent pharmacy businesses.

Despite these challenges, the United States pharmacy market offers considerable growth opportunities driven by expanding digital health adoption, growing demand for personalized medicine, and the continued development of specialty drugs. Increasing investment in telehealth-integrated pharmacy services, medication therapy management, and immunization programs is expected to further strengthen the market and support long-term growth for pharmacy providers across the country.

Competitive Landscape

The United States pharmacy market is highly competitive, with hospital, retail, and online pharmacy providers continuously expanding their service offerings to strengthen patient engagement. Leading players are investing in digital health integration, medication management programs, and expanded immunization and wellness services. Market structure, competitive positioning, and strategic initiatives among key players are shaping the industry’s evolving landscape as providers work to improve access, affordability, and patient outcomes.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Air Freight Market Size to Hit USD 91.81 Billion in 2034 | Grow CAGR by 4.08%

United States Air Freight Market Size to Hit USD 91.81 Billion in 2034 | Grow CAGR by 4.08%

IMARC Group has recently released a new research study titled “United States Air Freight Market Size, Share, Trends and Forecast by Service, Destination, End User, and Region, 2026-2034,” offers a detailed United States air freight market forecast covering market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

United States Air Freight Market Size, Growth, and Forecast (2026-2034)

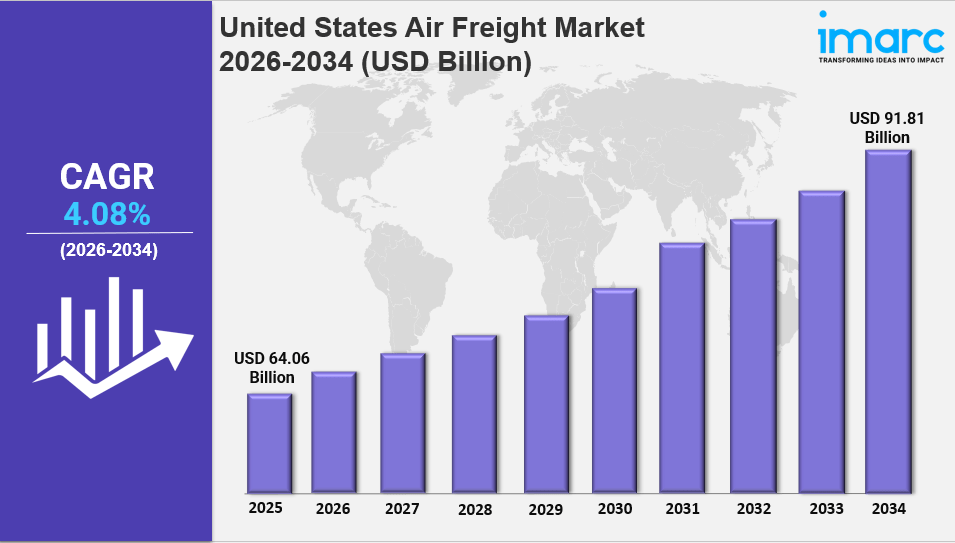
The United States air freight market size was valued at USD 64.06 Billion in 2025 and is projected to reach USD 91.81 Billion by 2034, growing at a CAGR of 4.08% during 2026-2034. The market is driven by the growing application in the pharmaceutical and medical sectors, and wide availability of fast-shipping solutions.

The rising adoption of artificial intelligence (AI) and the internet of things (IoT), coupled with growing investments by retail giants in dedicated air cargo services to meet delivery promises, represent other major growth-inducing factors driving the United States air freight market share.

Consumers now expect shorter delivery times, prompting retailers to prioritize air freight services. For instance, in June 2024, Nippon Express began a new airfreight service from Cincinnati/Northern Kentucky International Airport to Chubu Centrair International Airport in Japan to meet regional demand. Supply chain disruptions, such as ocean freight delays and port congestion, have further led businesses to shift toward air transport to maintain inventory flow and meet customer demands efficiently.

Explore Growth Opportunities in the United States Air Freight Market – Grab Your Sample Report for Evaluation: https://www.imarcgroup.com/united-states-air-freight-market/requestsample

Key Trends Driving the United States Air Freight Market

  • E-commerce expansion: The explosive growth of e-commerce is a major driver, as consumers increasingly expect fast, often next-day, delivery, prompting retail giants and marketplaces to invest heavily in dedicated air cargo services, exemplified by ECU Worldwide’s June 2024 partnership with ShipBob to offer integrated air and ocean freight services.
  • Supply chain disruptions and demand for speed: Congestion at major seaports, labor shortages, and geopolitical tensions have made ocean freight less reliable, prompting companies to increasingly use air freight to bypass bottlenecks and maintain inventory flow for critical, high-margin products.
  • Transportation of high-value and time-sensitive goods: Sectors such as electronics, pharmaceuticals, aerospace, and automotive manufacturing depend heavily on air cargo for quick, safe delivery, with air freight’s temperature-controlled environments and rigorous tracking systems proving indispensable.
  • Growing investment in logistics infrastructure: Substantial investments in airport cargo facilities and automation technologies have improved air freight capacity, tracking, and handling efficiency, making air transport more attractive to shippers.
  • Expansion of dedicated air cargo carriers: Amazon officially launched Amazon Air Cargo in October 2024, expanding its air logistics beyond parcel delivery and opening its fleet to freight forwarders and businesses, challenging established carriers such as FedEx and UPS.
  • Shifting trade policies and strategic alliances: Evolving tariffs and trade agreements are influencing logistics strategies, often favoring air freight to mitigate regulatory risk, as seen in Atlantis Transportation Services/ACI Air Cargo’s April 2024 strategic alliance with AGI.

United States Air Freight Market Report Segmentation:

The United States Air Freight Market report provides a detailed segmentation analysis to help businesses identify key growth segments and evolving industry trends. The market is categorized based on service, destination, end user, and region.

Service Insights:

  • Freight: Stands as the largest service segment, holding around 39.8% of the market in 2025, driven by its crucial role in transporting high-value, time-sensitive, and large-volume goods across industries such as electronics, pharmaceuticals, automotive, and aerospace.
  • Express: Caters to businesses requiring the fastest possible delivery for urgent, time-critical shipments.
  • Mail: Supports postal and parcel delivery services requiring reliable air transportation networks.
  • Others: Includes additional specialized air cargo service categories supporting diverse shipping needs.

Destination Insights:

  • Domestic: Leads the market with around 62.5% share, supported by the country’s well-established infrastructure, high demand for fast delivery within its borders, and the proximity of major airports enabling cost-effective, reliable logistics.
  • International: Continues to grow, supported by global trade demand and expanding air cargo connectivity between the U.S. and key international markets.

End User Insights:

  • Commercial: Leads the market with around 67.8% share in 2025, as commercial airlines offer established, reliable networks and infrastructure enabling efficient, time-sensitive shipments while benefiting from economies of scale on existing passenger flight routes.
  • Private: Serves specialized and dedicated air cargo needs for businesses requiring tailored logistics solutions.

Regional Insights:

  • Northeast: Benefits from a high concentration of major airports like JFK and Newark, facilitating swift air freight movement, with strong demand driven by pharmaceuticals, technology, and manufacturing industries.
  • Midwest: Driven by manufacturing hubs and distribution centers, with major airports like Chicago O’Hare and Detroit Metropolitan serving as critical air freight hubs connecting the region to global markets.
  • South: A key hub supported by a rapidly growing e-commerce sector, particularly in Texas and Florida, with major logistics hubs like Dallas/Fort Worth and Miami International Airport facilitating goods movement.
  • West: Central to the market due to proximity to Asia and the Pacific Rim, with strong e-commerce demand and an extensive airport network including San Francisco and Los Angeles International supporting both domestic and international shipments.

Competitive Landscape:

The air freight market for the United States is highly competitive, with numerous major players dominating the sector. Key carriers like FedEx, UPS, and DHL Express offer comprehensive global air freight services, with extensive networks and infrastructure to support fast deliveries. Integrated air cargo services provided by traditional airlines such as American Airlines, Delta, and United Airlines also contribute significantly to the market. These companies compete on speed, reliability, cost-efficiency, and technological advancements in tracking and automation. Emerging players and logistics companies, including Amazon Air, are increasingly expanding their air cargo capabilities to capture market share, while third-party logistics providers such as XPO Logistics offer end-to-end solutions. The market research report provides a comprehensive analysis of market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the market.

United States Air Freight Market Recent News and Developments:

  • CEVA Logistics launches trans-Pacific air cargo charter service: In March 2025, CEVA Logistics started a new trans-Pacific air cargo charter service with three weekly flights between Wuxi, China and Chicago, Illinois, offering more dependable air capacity while providing sustainable aviation fuel options through its CEVA FORPLANET suite.
  • Qantas Freight launches new U.S. booking website: In November 2024, Qantas Freight launched a new United States website allowing U.S.-based freight forwarders to search and book cargo capacity online across Qantas and Jetstar services in the U.S., Australia, and New Zealand.
  • Amazon launches Amazon Air Cargo: In October 2024, Amazon officially launched Amazon Air Cargo, opening its fleet of over 100 aircraft and 250 daily flights to freight forwarders and businesses, challenging established carriers FedEx and UPS.
  • CMA CGM AIR CARGO launches first transpacific service: In August 2024, CMA CGM AIR CARGO launched its first transpacific service connecting Hong Kong to Chicago, marking a key step in its North American expansion with additional aircraft deliveries planned to boost capacity.
  • P. Moller-Maersk opens Miami air freight gateway: In May 2024, A.P. Moller-Maersk launched a full-service air freight gateway in Miami to enhance connectivity between the U.S., Asia, and Latin America, strengthening its global air freight network.

Challenges Impacting the United States Air Freight Market

High operational costs associated with fuel, infrastructure, and technology investments continue to pressure margins across the air freight industry.

Capacity constraints at major airports and cargo facilities can create bottlenecks during periods of peak demand, particularly around major shopping seasons.

Evolving trade policies, tariffs, and regulatory requirements add complexity for carriers and shippers navigating cross-border shipments.

Investment Opportunities in the United States Air Freight Market

The United States air freight market offers compelling investment opportunities supported by its steady 4.08% CAGR through 2034. Dedicated e-commerce air cargo services represent a high-growth opportunity as retailers continue to prioritize fast, reliable delivery.

AI and IoT-enabled logistics infrastructure presents an expanding investment category, as carriers seek to improve tracking, automation, and operational efficiency across their networks.

Pharmaceutical and high-value goods logistics offer attractive returns as specialized, temperature-controlled air cargo services continue to see rising demand across time-sensitive industries.

United States Air Freight Market Forecast and Outlook (2026-2034)

The United States air freight market forecast remains favorable, supported by continued e-commerce growth, rising demand for high-value and time-sensitive goods transportation, and ongoing investment in logistics infrastructure and automation. The market is projected to grow from USD 64.06 Billion in 2025 to USD 91.81 Billion by 2034 at a CAGR of 4.08%.

As dedicated cargo carriers, AI-enabled logistics, and expanding international connectivity continue to strengthen the sector, the United States air freight market is expected to sustain steady growth momentum through 2034.

Frequently Asked Questions (FAQs): United States Air Freight Market

  1. What is the current size of the US air freight market?

The United States air freight market was valued at USD 64.06 Billion in 2025.

  1. What is the projected growth rate of the US air freight market?

The market is projected to exhibit a CAGR of 4.08% during 2026-2034, reaching USD 91.81 Billion by 2034.

  1. What are the main drivers fueling the growth of air freight in the US?

Key drivers include booming e-commerce demand, rising need for rapid transportation of high-value goods, supply chain disruptions favoring faster shipping options, advancements in logistics infrastructure, and evolving trade policies and tariffs influencing shipment patterns.

  1. How is the market segmented by service?

The market is segmented by service into freight, express, mail, and others, with freight leading at around 39.8% share in 2025.

  1. How is the market segmented by destination?

The market is segmented by destination into domestic and international, with domestic leading at around 62.5% share.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201971-6302

United States Cybersecurity Market Size to Hit USD 180.4 Billion by 2034

United States Cybersecurity Market Size to Hit USD 180.4 Billion by 2034

IMARC Group has recently released a new research study titled “United States Cybersecurity Market Report by Component (Solutions, Services), Deployment Type (Cloud Based, On-Premises), User Type (Large Enterprises, Small and Medium Enterprises), Industry Vertical (IT and Telecom, Retail, BFSI, Healthcare, Defense/Government, Manufacturing, Energy, and Others), and Region 2026-2034”, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

United States Cybersecurity Market Size and Growth Forecast (2026–2034)

The United States cybersecurity market size reached USD 91.6 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 180.4 Billion by 2034, exhibiting a growth rate (CAGR) of 7.60% during 2026–2034. The market is being driven by the increasing frequency and sophistication of cyberattacks, growing adoption of cloud computing, and rising investments in digital transformation across industries. Organizations are strengthening their cybersecurity infrastructure to protect sensitive data, ensure regulatory compliance, and safeguard critical business operations. The expanding use of artificial intelligence, Internet of Things (IoT), and remote work environments is further accelerating demand for advanced security solutions.

The United States cybersecurity market growth is also supported by increasing government initiatives, stricter data privacy regulations, and rising enterprise spending on zero-trust architecture, endpoint protection, and cloud security platforms. Businesses across sectors such as banking, healthcare, manufacturing, retail, and government are prioritizing proactive threat detection, security analytics, and managed security services to mitigate evolving cyber risks. As digital ecosystems continue to expand and cyber threats become more complex, continuous innovation in AI-powered threat intelligence, identity and access management, and automated security solutions is expected to sustain long-term market growth throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year:2025
  • Historical Years:2020–2025
  • Forecast Period:2026–2034
  • Market Size (2025):USD 91.6 Billion
  • Projected Size (2034):USD 180.4 Billion
  • Growth Rate:CAGR of 7.60%

Analyze the United States Cybersecurity Market: Download the IMARC Sample Report for Insights: https://www.imarcgroup.com/united-states-cybersecurity-market/requestsample

United States Cybersecurity Market Trends and Growth Drivers

The United States cybersecurity market growth is being driven by the rising frequency and sophistication of cyberattacks targeting enterprises, government agencies, and critical infrastructure. Organizations are increasing investments in advanced security technologies to protect sensitive data, digital assets, and cloud environments from ransomware, phishing, and data breaches. The widespread adoption of remote and hybrid work models has further expanded the attack surface, encouraging businesses to strengthen endpoint security, identity management, and network protection strategies.

One of the leading United States cybersecurity market trends is the growing adoption of artificial intelligence (AI), machine learning, and automation to enhance threat detection and incident response. AI-powered security platforms enable organizations to identify anomalies, predict potential threats, and respond to cyber incidents in real time. In addition, the increasing implementation of zero-trust security frameworks, cloud-native security solutions, and managed detection and response (MDR) services is transforming cybersecurity operations across industries such as banking, healthcare, retail, manufacturing, and government.

Another significant factor supporting United States cybersecurity market growth is the expansion of regulatory compliance requirements and increased investment in digital transformation initiatives. Businesses are prioritizing secure cloud migration, Internet of Things (IoT) protection, and cybersecurity risk management to comply with evolving data privacy regulations and maintain customer trust. Meanwhile, United States cybersecurity market trends indicate growing demand for security orchestration, extended detection and response (XDR), and identity and access management (IAM) solutions, which are expected to create substantial growth opportunities as organizations continue to modernize their digital infrastructure.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=9660&flag=C

United States Cybersecurity Market Segmentation Analysis

Breakup by Component:

  • Solutions
    • Identity and Access Management (IAM)
    • Infrastructure Security
    • Governance, Risk and Compliance
    • Unified Vulnerability Management Service Offering
    • Data Security and Privacy Service Offering
    • Others
  • Services
    • Professional Services
    •  Managed Services

The report offers a comprehensive segmentation and analysis of the market based on its components. It categorizes the market into solutions including identity and access management (IAM), infrastructure security, governance, risk and compliance, unified vulnerability management, and data security and privacy offerings and services, which comprise professional services and managed services.

Breakup by Deployment Type:

  • Cloud Based
  • On-Premises

The report also presents a detailed segmentation and analysis of the market based on deployment type, covering both cloud-based and on-premises solutions.

Breakup by User Type:

  • Large Enterprises
  • Small and Medium Enterprises

The report further provides a comprehensive segmentation and analysis of the market based on user type, including large enterprises and small and medium enterprises (SMEs).

Breakup by Industry Vertical:

  • IT and Telecom
  • Retail
  • BFSI
  • Healthcare
  • Defense/Government
  • Manufacturing
  • Energy
  • Others

The report also includes a comprehensive segmentation and analysis of the market based on industry verticals, covering IT and telecom, retail, BFSI, healthcare, defense/government, manufacturing, energy, and other sectors.

Breakup by Regional:

  • Northeast
  • Midwest
  • South
  • West

The report further delivers a comprehensive analysis of the key regional markets, including the Northeast, Midwest, South, and West regions.

Competitive Landscape of the United States Cybersecurity Market

The United States cybersecurity market is highly competitive, with leading global companies focusing on innovation, strategic acquisitions, and AI-driven security solutions to strengthen their market position. Vendors are investing heavily in cloud security, endpoint protection, zero-trust architecture, identity and access management, and threat intelligence platforms to address evolving cyber risks. The market is also witnessing increased partnerships between cybersecurity firms, cloud providers, and government agencies to enhance digital resilience and deliver comprehensive security solutions across enterprise and public-sector environments.

Key Players

  • Palo Alto Networks – Provides AI-powered network, cloud, and endpoint security solutions with a strong focus on zero-trust cybersecurity.
  • CrowdStrike Holdings, Inc. – Specializes in cloud-native endpoint protection, threat intelligence, and real-time cyberattack detection using AI.
  • Cisco Systems, Inc. – Delivers integrated cybersecurity solutions including secure networking, identity protection, and cloud security for enterprises.
  • Fortinet, Inc. – Offers comprehensive cybersecurity platforms featuring firewalls, secure networking, endpoint security, and advanced threat prevention.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201971-6302