Author: Deepak Mishra

United States Fertilizer Market Size, Share, Demand & Growth Report 2026-2034

United States Fertilizer Market Size, Share, Demand & Growth Report 2026-2034

IMARC Group has recently released a new research study titled “United States Fertilizer Market Size, Share, Trends and Forecast by Product Type, Product, Product Form, Crop Type, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Fertilizer Market Size & Share 2026-2034

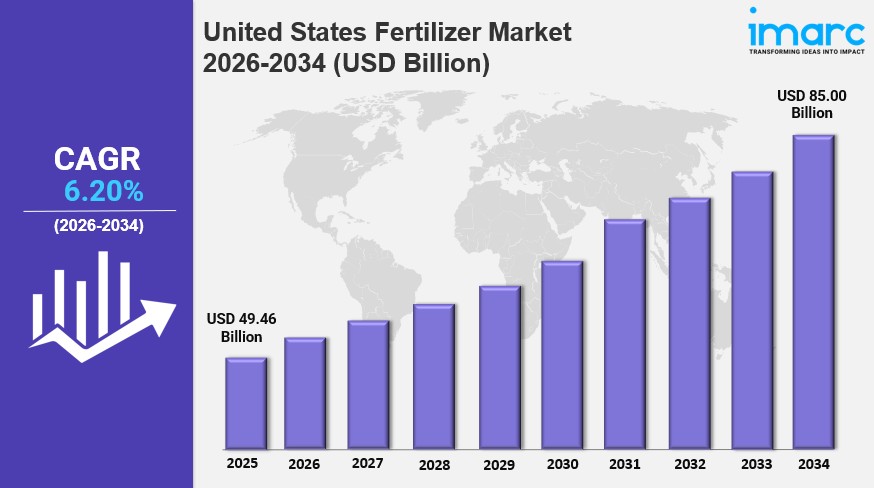
The United States fertilizer market size was valued at USD 49.46 Billion in 2025 and is projected to reach USD 85.00 Billion by 2034, growing at a CAGR of 6.20% during 2026-2034. The market is driven by expanding agricultural production demands, increasing adoption of precision farming techniques, and the growing need for enhanced crop yields across diverse farming operations.

Chemical fertilizer dominates the market with a share of 83% in 2025, straight fertilizers lead the product segment at 57%, dry form represents the largest segment at 68%, grains and cereals dominate crop type at 40%, and the South leads regionally with a 30% share, collectively shaping the United States fertilizer market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 49.46 Billion
  • Projected Market Size (2034): USD 85.00 Billion
  • Growth Rate: CAGR of 6.20% (2026-2034)

Explore Opportunities in the United States Fertilizer Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-fertilizer-market/requestsample

Key Growth Drivers and Trends in the United States Fertilizer Market

Growth in the United States fertilizer market is being driven by expanding agricultural production requirements, as escalating global demand for food products necessitates continuous enhancement of agricultural productivity, positioning fertilizers as essential inputs for achieving targeted yield improvements. In December 2024, the USDA invested $116 Million through the Fertilizer Production Expansion Program to expand eight domestic fertilizer facilities, boosting supply, lowering costs for farmers, and creating rural jobs.

One of the leading United States fertilizer market trends is growing adoption of precision agriculture technologies, as farmers increasingly leverage variable rate application systems, GPS-guided equipment, and soil sensing technologies to optimize nutrient delivery based on field-specific requirements. In June 2025, U.S. Sugar partnered with Everglades Equipment to implement John Deere’s GPS-guided fertilizer applicators and other precision tools across its 255,000-acre operation to improve efficiency and reduce input waste. As of December 2024, approximately 68% of large U.S. crop farms utilize precision agriculture technologies, including yield monitors and soil maps.

Another key factor supporting United States fertilizer market growth is increasing preference for slow-release and controlled-release fertilizers, as these advanced products deliver nutrients gradually over extended periods, aligning nutrient availability with plant uptake patterns. In May 2024, ICL Group began shipments of controlled-release fertilizers featuring biodegradable coating technology, enhancing nutrient use efficiency while addressing sustainability concerns in agricultural nutrient delivery, alongside rising adoption of enhanced efficiency fertilizers incorporating nitrification and urease inhibitors.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=19951&flag=C

United States Fertilizer Industry Segmentation Insights

Breakup by Product Type:

  • Chemical Fertilizer: Dominates the market with a share of 83% in 2025, driven by its ability to provide specific nutrients, economical nature, and established track record in delivering measurable yield improvements across major commodity crops.
  • Biofertilizers: Represents a growing segment supported by sustainability trends and organic farming expansion.

Breakup by Product:

  • Straight Fertilizers: Leads the market with a share of 57% in 2025, encompassing nitrogenous, phosphatic, potash, secondary macronutrient, and micronutrient fertilizers, owing to targeted nutrient delivery capabilities addressing specific soil deficiencies.
  • Complex Fertilizers: Covers multi-nutrient formulations supporting comprehensive crop nutrition requirements.

Breakup by Product Form:

  • Dry: Represents the largest segment with a market share of 68% in 2025, driven by improved storage stability and compatibility with traditional application equipment.
  • Liquid: Supports precision application methods and fertigation systems across specialized farming operations.

Breakup by Crop Type:

  • Grains and Cereals: Dominates the market with a share of 40% in 2025, owing to large-scale production of corn, wheat, and soybean consuming enormous amounts of fertilizers.
  • Pulses and Oilseeds: Represents a significant crop category requiring targeted nutrient management programs.
  • Fruits and Vegetables: Supports specialty crop production requiring customized fertilizer formulations.
  • Flowers and Ornamentals: Covers fertilizer demand across ornamental horticulture applications.
  • Others: Includes additional crop categories supporting broader agricultural fertilizer demand.

Breakup by Region:

  • South: Leads the market with a share of 30% in 2025, driven by varied agricultural practices and year-round growing seasons that favor multiple harvests.
  • Midwest: Represents a major region supported by large-scale corn, wheat, and soybean production across the Great Plains.
  • West: Supports specialty crop and fruit and vegetable cultivation requiring diverse fertilizer formulations.
  • Northeast: Reflects steady demand across diversified regional agricultural operations.

Key Challenges and Growth Opportunities in the United States Fertilizer Market

The United States fertilizer market faces challenges including volatility in raw material pricing, as natural gas prices significantly influence nitrogen fertilizer production economics while phosphate and potash costs depend on mining and processing expenses, environmental regulations addressing water quality and greenhouse gas emissions, and expansion of organic farming reducing demand for chemical fertilizers among transitioning operations.

Despite these challenges, the market offers considerable growth opportunities driven by continued precision agriculture adoption, growing interest in specialty and enhanced efficiency fertilizers, and rising investment in research and development for innovative fertilizer technologies. Regional agricultural diversification and expansion of specialty crop cultivation are expected to create substantial opportunities for long-term growth in the United States fertilizer market.

Competitive Landscape

The United States fertilizer market exhibits a consolidated competitive landscape, with established manufacturers competing across product segments through distribution network expansion, product innovation, and strategic partnerships with agricultural cooperatives. Key players include CF Industries Holdings, Inc., Haifa Group, ICL Group Ltd., Koch Industries Inc., Nutrien Ltd., Sociedad Química y Minera de Chile SA, The Andersons Inc., The Mosaic Company, Wilbur-Ellis Company LLC, and Yara International ASA. In 2025, Nutrien’s North American operations achieved a 94% ammonia operating rate, with nitrogen sales of 10.7 to 11.0 Million Tonnes and potash sales of 14.0 to 14.5 Million Tonnes.

Recent Developments in the United States Fertilizer Market

  • August 2024: Itafos, a North American fertilizer multinational, announced expansion in Brazil, opening a new office in Luís Eduardo Magalhães, Bahia, aiming to increase regional sales from 20% to 30% by 2025 and strengthen farmer relationships.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Pharmacy Market Size, Demands, Growth Analysis, Industry Report 2026-2034

United States Pharmacy Market Size, Demands, Growth Analysis, Industry Report 2026-2034

IMARC Group has recently released a new research study titled “United States Pharmacy Market Report by Product Type (Prescription, OTC), Pharmacy Type (Hospital Pharmacy, Retail Pharmacy, ePharmacy, and Others), Ownership (Independent, Chain), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Pharmacy Market Size & Share 2026-2034

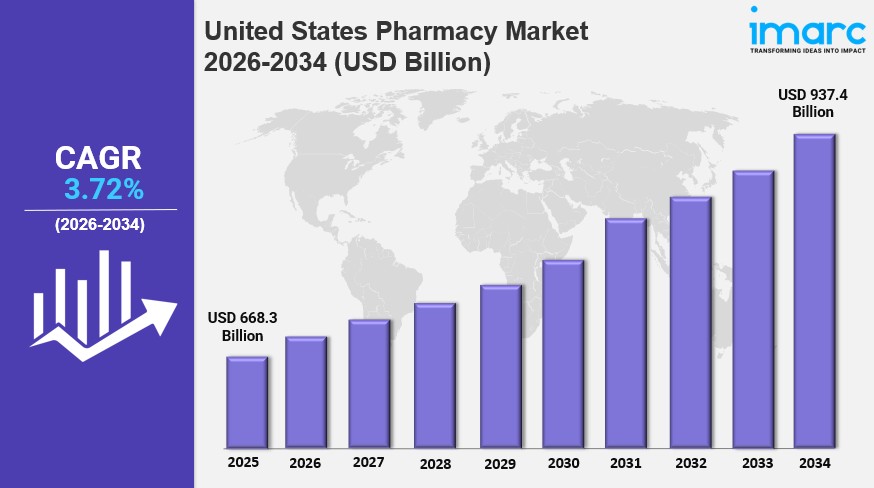
The United States pharmacy market size reached USD 668.3 Billion in 2025 and is projected to reach USD 937.4 Billion by 2034, expanding at a CAGR of 3.72% during 2026-2034. The increasing incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions, which leads to higher demand for medications, continues to drive the market.

Growth in 2026 is further supported by increasing regional population and rising healthcare awareness, alongside advancements in medical research and technology driving development of innovative drugs and therapies. The expanding role of e-commerce and digital health solutions is expected to strengthen the United States pharmacy market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 668.3 Billion
  • Projected Market Size (2034): USD 937.4 Billion
  • Growth Rate: CAGR of 3.72% (2026-2034)

Explore Opportunities in the United States Pharmacy Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-pharmacy-market/requestsample

Key Growth Drivers and Trends in the United States Pharmacy Market

Growth in the United States pharmacy market is being driven by increasing regional population and a rise in healthcare awareness, which have significantly propelled demand for pharmaceutical products. As the population grows, so does the need for medications, creating sustained upward pressure on the pharmacy market, while advancements in medical research and technology continue to serve as catalysts driving the development of innovative drugs and therapies.

One of the leading United States pharmacy market trends is the impact of the country’s aging demographic, as the elderly typically require a higher volume of medications and healthcare services. This demographic shift contributes substantially to the expanding pharmacy market, compounded by the rising prevalence of chronic diseases fueled by lifestyle changes and environmental factors, which underscores the growing importance of pharmaceutical interventions and amplifies demand for a diverse range of medications.

Another key factor supporting United States pharmacy market growth is the expanding role of e-commerce and digital health solutions, which is facilitating more convenient access to pharmaceutical products and services. Online pharmacies and telehealth platforms are gaining traction, offering consumers a seamless and efficient way to fulfill their healthcare needs, reflecting the pharmacy sector’s ongoing evolution beyond traditional dispensing roles toward patient-centered care, immunizations, and chronic disease management.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21066&flag=C

United States Pharmacy Industry Segmentation Insights

Breakup by Product Type:

  • Prescription: Represents a core segment driven by rising chronic disease prevalence and growing demand for physician-directed medication therapy.
  • OTC: Benefits from growing consumer preference for self-directed health management and accessible over-the-counter treatment options.

Breakup by Pharmacy Type:

  • Hospital Pharmacy: Serves inpatient and outpatient medication needs within clinical care settings, supporting comprehensive patient treatment plans.
  • Retail Pharmacy: Represents a widely accessible channel for prescription and OTC medications, supported by extensive chain and independent store networks.
  • ePharmacy: Growing rapidly, driven by expanding e-commerce adoption and consumer demand for convenient, digitally enabled medication access.
  • Others: Includes additional pharmacy formats serving specialized dispensing and patient care needs.

Breakup by Ownership:

  • Independent: Reflects locally owned pharmacies offering personalized patient care and community-based service.
  • Chain: Represents large-scale pharmacy networks benefiting from broad geographic reach and operational scale.

Breakup by Region:

  • Northeast: Benefits from dense population centers and strong healthcare infrastructure supporting pharmacy service demand.
  • Midwest: Supported by an aging population and expanding chronic disease management needs across the region.
  • South: Experiencing rising demand driven by population growth and expanding healthcare access initiatives.
  • West: Anchored by strong adoption of digital health solutions and growing telehealth-enabled pharmacy services.

Key Challenges and Growth Opportunities in the United States Pharmacy Market

The United States pharmacy market faces challenges including rising prescription drug costs, complex insurance reimbursement structures, and the need for continued investment in digital infrastructure to support evolving e-pharmacy and telehealth models. Ensuring medication access and affordability across diverse patient populations also remains an ongoing consideration for the industry.

Despite these challenges, the market offers considerable growth opportunities driven by expanding digital health adoption, growing demand for personalized medicine and specialty drug development, and continued expansion of retail pharmacy chains. Rising chronic disease prevalence and an aging population are expected to create substantial opportunities for long-term growth in the United States pharmacy market.

Competitive Landscape

The United States pharmacy market is highly competitive, comprising large chain pharmacy operators, independent community pharmacies, hospital-based dispensing systems, and a growing base of digital-first ePharmacy providers. Companies are focusing on expanding digital health integration, personalized patient care services, and specialty drug offerings to strengthen their market position and meet evolving consumer expectations around convenience and accessibility.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Construction Robots Market Size to Hit USD 8,485.1 Million by 2034: Trends & Forecast

Mexico Construction Robots Market Size to Hit USD 8,485.1 Million by 2034: Trends & Forecast

IMARC Group has recently released a new research study titled “Mexico Construction Robots Market Size, Share, Trends and Forecast by Function, Type, End Use, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Construction Robots Market Size & Share 2026-2034

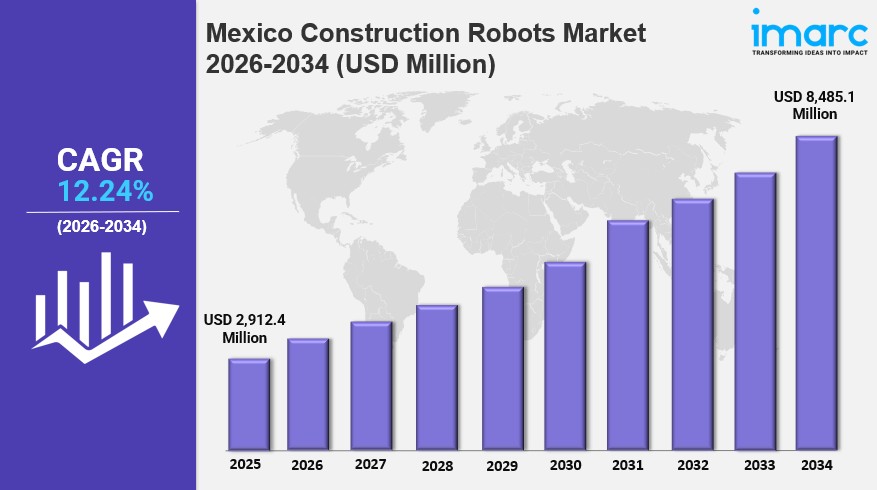
The Mexico construction robots market size reached USD 2,912.4 Million in 2025 and is projected to reach USD 8,485.1 Million by 2034, expanding at a CAGR of 12.24% during 2026-2034. In 2026, the market continues to gain strong momentum, propelled by labor shortages and rising labor costs that are prompting construction firms to adopt automation for greater efficiency.

Growth in 2026 is further reinforced by ongoing advancements in robotics technology enhancing operational precision and safety, alongside rising demand for scalable solutions supporting large-scale infrastructure projects. These dynamics are expected to strengthen the Mexico construction robots market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 2,912.4 Million
  • Projected Market Size (2034): USD 8,485.1 Million
  • Growth Rate: CAGR of 12.24% (2026-2034)

Explore Opportunities in the Mexico Construction Robots Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-construction-robots-market/requestsample

Key Growth Drivers and Trends in the Mexico Construction Robots Market

Growth in the Mexico construction robots market is being driven by mounting labor shortages and rising labor costs, as the country’s construction sector grapples with a shrinking skilled workforce. Building companies are increasingly implementing productivity enhancements that reduce dependence on human labor, with construction robots delivering cost-efficient outcomes by executing repetitive, dangerous, and physically intense tasks with greater efficiency, running operating schedules without breaks to shorten project timelines and help firms meet deadlines and budget constraints amid growing urban infrastructure demand.

One of the leading Mexico construction robots market trends is the rising demand for improved safety and operational efficiency, particularly given how often construction in Mexico involves physically demanding or hazardous tasks. Automation reduces the need for workers in risky areas, lowering the chances of workplace injuries, while robots increase operational efficiency by maintaining consistent performance without fatigue or human error, executing tasks such as bricklaying, demolition, and concrete printing faster and with higher precision to help contractors meet tight deadlines and comply with safety regulations.

Another key factor supporting Mexico construction robots market growth is significant infrastructure development backed by government investment. In March 2025, Mexico’s National Water Commission (Conagua) revealed a historic investment of 122.6 billion pesos, more than 5.6 billion euros, for 2025-2030 as part of the National Water Plan, directed toward 17 strategic water infrastructure projects in areas with the highest water demand and flood risk. These initiatives demand faster, safer, and more cost-efficient construction methods, with public-private partnerships and international investment further encouraging adoption of smart construction technologies across roads, bridges, and housing projects.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32764&flag=C

Mexico Construction Robots Industry Segmentation Insights

Breakup by Function:

  • Demolition: Utilizes robotic systems to safely and efficiently dismantle structures in hazardous environments.
  • Bricklaying: Employs automation to accelerate wall construction with consistent precision.
  • 3D Printing: Enables rapid, precise construction of building components and structures.
  • Concrete Structural Erection: Supports efficient placement and assembly of structural concrete elements.
  • Finishing Work: Automates detailed tasks such as painting, plastering, and surface finishing.
  • Doors and Windows Installation: Streamlines precise fitting and installation of building fixtures.
  • Others: Includes additional robotic applications supporting diverse construction tasks.

Breakup by Type:

  • Traditional Robot: Represents established robotic systems used across various construction automation tasks.
  • Robotic Arm: Offers precise, programmable movement suited for repetitive and detail-oriented construction tasks.
  • Exoskeleton: Enhances worker strength and endurance, reducing physical strain during demanding construction activities.

Breakup by End Use:

  • Industrial: Represents a leading end-use segment driven by large-scale industrial construction and infrastructure projects.
  • Commercial: Benefits from growing adoption of automation in commercial building construction.
  • Residential: Reflects rising interest in robotic solutions to address housing construction demand.

Breakup by Region:

  • Northern Mexico: Benefits from a strong industrial base and proximity to U.S. trade routes supporting construction automation investment.
  • Central Mexico: Holds a significant share supported by dense urban population and large-scale infrastructure projects.
  • Southern Mexico: An emerging region with growing infrastructure investment supporting construction robotics adoption.
  • Others: Comprises smaller regional markets experiencing gradual growth in construction robotics demand.

Key Challenges and Growth Opportunities in the Mexico Construction Robots Market

The Mexico construction robots market faces challenges including high upfront capital costs for robotic systems and integration infrastructure, along with the need for specialized technical training to operate and maintain advanced construction robotics. Ensuring compatibility between robotic systems and traditional construction workflows can also pose adoption hurdles, particularly among smaller contractors.

Despite these challenges, the market offers considerable growth opportunities driven by continued government investment in infrastructure development, rising labor shortages accelerating automation adoption, and growing demand for improved safety and operational efficiency on construction sites. Expanding public-private partnerships and international investment in smart construction technologies are expected to create substantial opportunities for long-term growth in the Mexico construction robots market.

Competitive Landscape

The Mexico construction robots market is evolving, with domestic and international robotics manufacturers focusing on technological innovation, strategic partnerships, and expanding product portfolios to strengthen their market position. Companies are investing in advanced robotic systems tailored to specific construction functions, while forming collaborations with construction firms and government agencies to accelerate adoption of automation across Mexico’s growing infrastructure and building sectors.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Digital OOH Advertising Market Size, Demands, Growth Analysis, Industry Report 2026-2034

United States Digital OOH Advertising Market Size, Demands, Growth Analysis, Industry Report 2026-2034

IMARC Group has recently released a new research study titled “United States Digital OOH Advertising Market Size, Share, Trends and Forecast by Format Type, Application, End Use Industry, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Digital OOH Advertising Market Size & Share 2026-2034

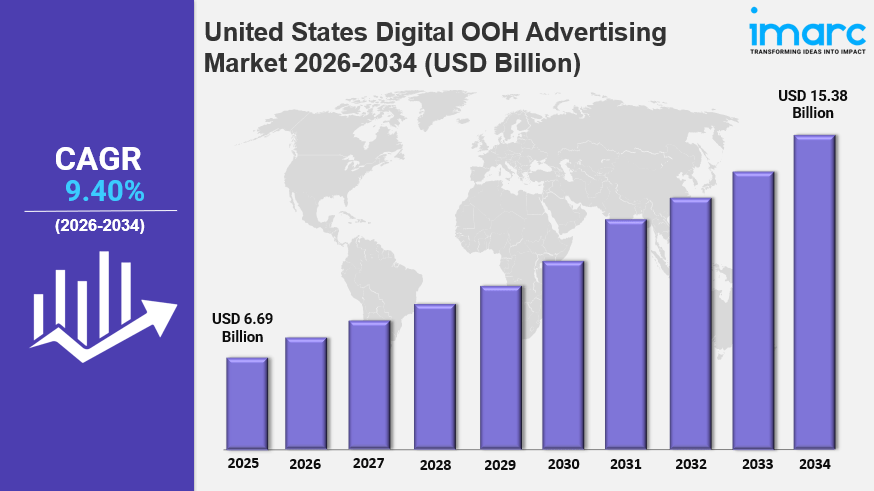
The United States digital OOH advertising market grew from USD 6.69 Billion in 2025 to USD 7.32 Billion in 2026 and is projected to reach USD 15.38 Billion by 2034, growing at a CAGR of 9.40% during 2026-2034. The rapid adoption of programmatic digital OOH enabling data-driven audience targeting, urban smart city infrastructure investment accelerating digital screen deployment, brands shifting advertising budgets from traditional to measurable digital formats, and AI-powered creative optimization improving DOOH campaign performance are the primary growth catalysts.

The South leads regionally with a 34.1% market share in 2025, driven by the region’s large highway corridor digital OOH inventory across Texas, Florida, Georgia, and North Carolina, strong retail and quick-service restaurant advertiser demand, and growing smart city digital infrastructure investment. Digital billboards command the dominant 41.6% format share, reflecting the primacy of large-format roadside digital displays, while outdoor placements account for 68.7% of the application segment, strengthening the United States digital OOH advertising market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 6.69 Billion
  • Market Size (2026): USD 7.32 Billion
  • Projected Market Size (2034): USD 15.38 Billion
  • Growth Rate: CAGR of 9.40% (2026-2034)

Explore Opportunities in the United States Digital OOH Advertising Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-digital-ooh-advertising-market/requestsample

Key Growth Drivers and Trends in the United States Digital OOH Advertising Market

Growth in the United States digital OOH advertising market is being driven by the rapid maturation of programmatic digital OOH, which has fundamentally transformed the format from a traditional mass-reach media buy into a data-addressable, real-time-optimized advertising channel. Programmatic platforms enable brands to purchase digital OOH impressions based on audience demographic data, location context, weather conditions, and proximity to retail locations, with major demand-side platforms including The Trade Desk and Google DV360 now integrating digital OOH inventory alongside digital media for unified cross-channel campaign execution.

One of the leading United States digital OOH advertising market trends is the integration of digital OOH into retail media networks, representing the most transformative structural development in indoor digital advertising. Walmart’s digital screen network, Target’s Roundel in-store advertising network, and Amazon Fresh’s grocery digital screens are each creating closed-loop advertising ecosystems that combine first-party purchase data with physical screen placement at the point of purchase, attracting CPG advertiser budgets previously allocated to shopper marketing and driving above-market growth rates for this emerging category.

Another key factor supporting United States digital OOH advertising market growth is AI-powered dynamic creative optimization, enabling advertisers to deploy multiple contextually relevant creative executions that automatically adjust based on real-time data inputs including weather, time of day, local events, and audience demographics. Examples such as temperature-responsive creative serving hot coffee messages in cold weather and cold beverage messages in warm weather are creating new premium campaign formats that command higher CPMs than static creative, while urban smart city infrastructure investment continues deploying digital screens across bus shelters, kiosks, and wayfinding systems as part of connected city initiatives.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2875&flag=C

United States Digital OOH Advertising Industry Segmentation Insights

Breakup by Format Type:

  • Digital Billboards: Leads with a 41.6% share in 2025, generating the highest CPM rates, widest reach per face, and most compelling visual impact of any OOH format, sustained by ongoing conversion of static billboard faces to digital across every US market.
  • Video Advertising: Holds a 33.8% share in 2025, encompassing full-motion video screens in premium locations including Times Square, sports stadiums, shopping centers, and major transit hubs, delivering creative impact comparable to television commercials.
  • Ambient Advertising: Accounts for 15.2% share in 2025, covering street furniture including digital bus shelters, urban kiosks, and city panel networks.
  • Others: Includes additional digital OOH format types supporting diverse advertising placements.

Breakup by Application:

  • Outdoor: Dominates with a 68.7% share in 2025, anchored by roadside digital billboard advertising and transit displays as the core revenue base for major US operators, supported by the scale of the highway system and daily vehicle traffic.
  • Indoor: Holds a 31.3% share in 2025 and is growing at above-market rates, encompassing retail digital screen networks, sports and entertainment venue boards, office building lobby screens, healthcare facility displays, and restaurant digital menu boards.

Breakup by End Use Industry:

  • Retail: Represents a leading end-use industry, driven by expanding retail media network investment and point-of-purchase digital advertising integration.
  • Recreation: Benefits from digital OOH placements across entertainment venues, sports arenas, and leisure destinations.
  • Banking: Utilizes digital OOH advertising to reach consumers across urban and transit environments.
  • Transportation: Supports premium transit advertising inventory across airports, subway stations, and commuter rail platforms.
  • Education: Uses digital OOH placements to reach target demographics across relevant geographic markets.
  • Others: Includes additional end-use industries adopting digital OOH advertising solutions.

Breakup by Region:

  • South: Leads with a 34.1% share in 2025, driven by the largest US population base, highest highway vehicle miles travelled, and concentration of retail, QSR, and entertainment advertiser categories across Texas, Florida, Georgia, and North Carolina.
  • West: Holds a 26.5% share in 2025, driven by California’s large advertising market, premium inventory in Los Angeles and San Francisco, and concentration of technology company advertisers.
  • Midwest: Represents a 22.4% share in 2025, supported by strong highway corridor inventory, major sports venue digital screen networks, and growing programmatic adoption by regional retailers.
  • Northeast: Accounts for a 17.0% share in 2025, anchored by the highest-value inventory concentration including Times Square New York and premium transit advertising in the New York City subway.

Key Challenges and Growth Opportunities in the United States Digital OOH Advertising Market

The United States digital OOH advertising market faces challenges including the high capital cost of digital screen deployment, with a single large-format digital billboard conversion costing between USD 200,000 and 500,000, alongside complex federal, state, and local regulatory constraints including the Highway Beautification Act and municipal zoning ordinances limiting new digital screen construction. Ad fatigue and clutter in high-density urban markets, along with the absence of standardized digital OOH impression and attribution measurement, also pose ongoing considerations for the industry.

Despite these challenges, the market offers considerable growth opportunities driven by the explosive growth of retail media network digital OOH integration, AI-powered contextual and dynamic creative optimization commanding premium CPMs, and continued programmatic ecosystem maturation expanding the advertiser base to digital-native performance marketers. Emerging formats such as EV charging station digital screen networks offering high-dwell-time, captive audiences are expected to create substantial opportunities for long-term growth in the United States digital OOH advertising market.

Competitive Landscape

The United States digital OOH advertising market exhibits moderate concentration, with top US-focused operators collectively controlling approximately 65-70% of total US OOH revenues. Lamar Advertising Company holds market leadership through one of the largest digital OOH inventories by screen count and strong highway corridor dominance, while OUTFRONT Media Inc. maintains strong transit advertising leadership through its MTA New York partnership. JCDecaux SE competes through premium US airport and transit location inventory and smart city digital infrastructure partnerships, while Broadsign International Holding Company leads through its Broadsign Connect programmatic software platform powering thousands of screens across multiple media owner networks.

Recent Developments in the United States Digital OOH Advertising Market

  • February 2026: JCDecaux SE launched the world’s first global programmatic digital OOH media solution, expanding beyond airports into street, transport, and retail environments, enabling real-time campaign activation across more than 30,000 digital screens in over 35 markets through a single access point.
  • May 2025: Lamar Advertising Company entered a year-long partnership with the Imagination Library, donating digital billboard space across the U.S. to promote childhood literacy and increase awareness of the free book-gifting program, aiming to expand enrollment and support early reading development nationwide.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
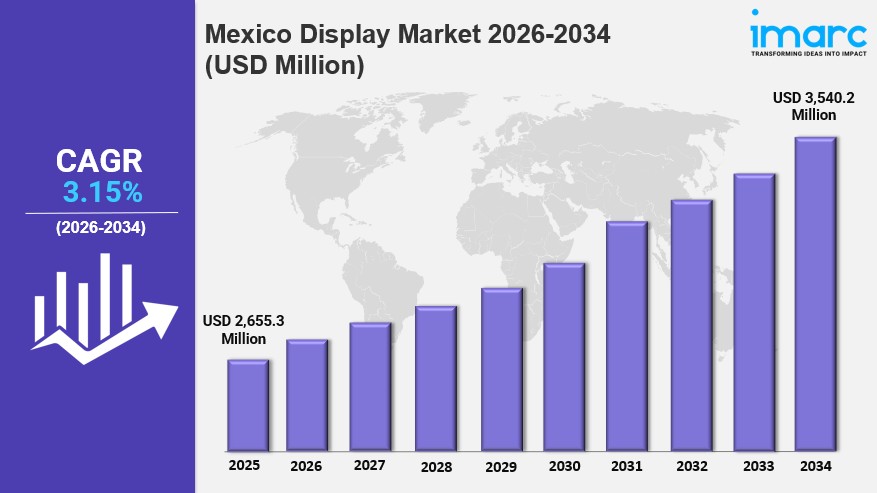
Mexico Display Market Size to Hit USD 3,540.2 Million by 2034

Mexico Display Market Size to Hit USD 3,540.2 Million by 2034

IMARC Group has recently released a new research study titled “Mexico Display Market Size, Share, Trends and Forecast by Display Type, Technology, Application, Industry Vertical, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Display Market Size & Share 2026-2034

The Mexico display market size reached USD 2,655.3 Million in 2025 and is projected to reach USD 3,540.2 Million by 2034, expanding at a CAGR of 3.15% during 2026-2034. In 2026, the market continues to gain momentum, driven by expanding digitization across industries, rising demand for visual communication, and growing investment in innovative infrastructure supporting the widespread implementation of display technology in retail, transportation, educational, and government environments.

Growth in 2026 is further supported by increasing adoption of interactive and touchscreen displays, ongoing advancements in LED and OLED technologies, and the rapid expansion of digital signage across urban commercial hubs. As institutions and businesses continue modernizing their visual communication infrastructure, these dynamics are expected to strengthen the Mexico display market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 2,655.3 Million
  • Projected Market Size (2034): USD 3,540.2 Million
  • Growth Rate: CAGR of 3.15% (2026-2034)

Explore Opportunities in the Mexico Display Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-display-market/requestsample

Key Growth Drivers and Trends in the Mexico Display Market

Growth in the Mexico display market is being driven by the rising demand for interactive and touchscreen displays, as sectors such as retail, education, and transportation increasingly embrace these technologies to engage users and provide real-time access to information. Digital kiosks and smartboards are progressively replacing conventional whiteboards in educational institutions, while retail spaces are adopting touchscreen kiosks to enable more personalized shopping experiences. In May 2024, BYD introduced the Shark hybrid-electric pickup in Mexico featuring advanced in-vehicle display systems, underscoring the country’s growing role as a hub for automotive display innovation.

One of the leading Mexico display market trends is the rapid adoption of LED and OLED technologies across applications, owing to their high resolution, power efficiency, and design flexibility. In May 2024, Dahua Technology unveiled advanced 3D video screens and immersive LED displays at Expo Seguridad México 2024, reshaping indoor and outdoor advertising and entertainment through cutting-edge visual technology. Flexible OLED displays are also opening new opportunities for curved shapes and compact devices, further expanding the range of applications across industries.

Another key factor supporting Mexico display market growth is the expansion of digital signage across urban commercial hubs. Digital billboards, video walls, and intelligent signage systems are increasingly replacing static printed formats, offering greater flexibility, real-time content refreshment, and customization. Growing use of digital signage in airports, train stations, and bus terminals is enhancing wayfinding and passenger communication, while retail and hospitality sectors are leveraging these solutions to create immersive brand experiences and communicate promotions to customers.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32448&flag=C

Mexico Display Industry Segmentation Insights

Breakup by Display Type:

  • Flat Panel Display: Widely used across consumer electronics and commercial applications, offering reliable performance and broad compatibility.
  • Flexible Panel Display: Enables curved and bendable form factors, supporting innovative device designs and wearable applications.
  • Transparent Panel Display: Used in specialized retail and architectural applications for immersive visual presentations.

Breakup by Technology:

  • OLED: Valued for vibrant colors, high contrast ratios, and flexibility in design across premium devices.
  • Quantum Dot: Delivers enhanced color accuracy and brightness for high-end television and display applications.
  • LED: Widely adopted for its efficiency, brightness, and suitability for large-format displays and signage.
  • LCD: A cost-effective and established technology used extensively across consumer and commercial displays.
  • E-Paper: Offers low power consumption and readability, suited for e-readers and select signage applications.
  • Others: Includes emerging and niche display technologies serving specialized use cases.

Breakup by Application:

  • Smartphone and Tablet: A major application segment driven by continuous consumer electronics innovation and upgrade cycles.
  • Smart Wearable: Growing with rising adoption of fitness trackers and smartwatches requiring compact, efficient displays.
  • Television and Digital Signage: Benefiting from expanding digital signage deployment and demand for large-format visual content.
  • PC and Laptop: Supported by steady demand for computing devices across personal and enterprise use.
  • Vehicle Display: Expanding rapidly with the rise of advanced in-vehicle infotainment and digital dashboard systems.
  • Others: Includes additional applications across emerging consumer and industrial devices.

Breakup by Industry Vertical:

  • BFSI: Utilizes displays for digital banking terminals and customer service interfaces.
  • Retail: Adopts displays for digital signage, touchscreen kiosks, and personalized shopping experiences.
  • Healthcare: Relies on displays for diagnostic imaging, patient monitoring, and information systems.
  • Consumer Electronics: A major driver of display demand across smartphones, televisions, and wearable devices.
  • Military and Defense: Uses ruggedized displays for command systems and specialized operational equipment.
  • Automotive: Growing rapidly with rising adoption of digital dashboards and in-vehicle display systems.
  • Others: Includes additional sectors adopting display technology for operational and communication needs.

Breakup by Region:

  • Northern Mexico: Benefits from strong manufacturing infrastructure and proximity to key automotive and electronics production hubs.
  • Central Mexico: Holds a significant share supported by dense urban population and expanding retail and commercial infrastructure.
  • Southern Mexico: An emerging region with growing adoption of digital signage and display technologies.
  • Others: Comprises smaller regional markets experiencing gradual growth in display technology adoption.

Key Challenges and Growth Opportunities in the Mexico Display Market

The Mexico display market faces challenges including high costs associated with advanced display technologies, dependence on imported components and raw materials, and the need for continuous innovation to keep pace with rapidly evolving consumer expectations. Infrastructure investment requirements for large-scale digital signage deployment can also pose hurdles for smaller businesses and public institutions seeking to modernize their visual communication systems.

Despite these challenges, the market offers significant growth opportunities driven by expanding digitization across retail, transportation, education, and government sectors, along with rising consumer demand for interactive and immersive visual experiences. Continued advancements in LED, OLED, and flexible display technologies, coupled with growing investment in smart infrastructure and automotive display innovation, are expected to create substantial opportunities for long-term growth in the Mexico display market.

Competitive Landscape

The Mexico display market is highly competitive, with domestic and international players focusing on technological innovation, product differentiation, and expanding distribution networks. Companies are investing in advanced display technologies, strategic partnerships, and localized marketing to strengthen their presence and meet the growing demand for high-performance, visually engaging display solutions across consumer, commercial, and industrial applications.

Recent Developments in the Mexico Display Market

  • April 2024: SRYLED showcased its advanced LED screens, including P2.6 GOB, fine-pitch, and glasses-free 3D displays, at Sound Check Xpo 2024, attracting large crowds and reflecting Mexico’s growing appetite for innovative LED display technology.
  • May 2024: Dahua Technology launched advanced 3D video screens and immersive LED displays at Expo Seguridad México 2024, transforming indoor and outdoor advertising and entertainment through cutting-edge visual technology.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
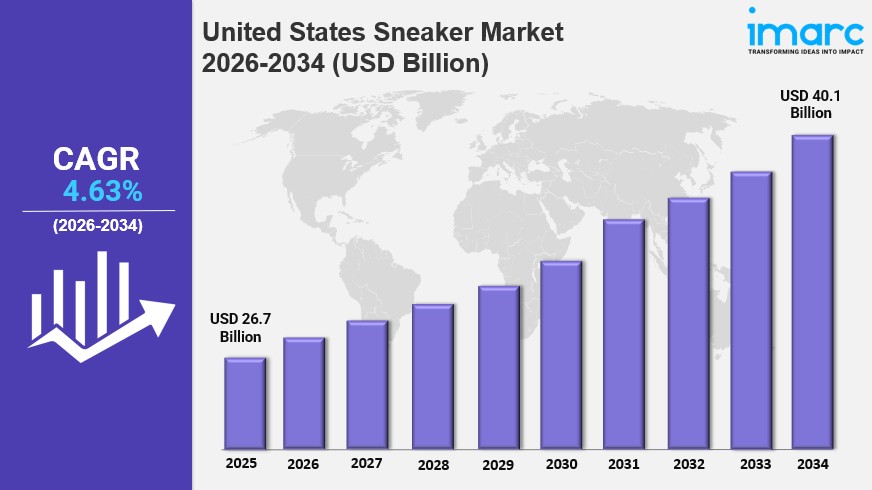
United States Sneaker Market 2026: Size, Trends, Growth, Latest Insights and Forecast to 2034

United States Sneaker Market 2026: Size, Trends, Growth, Latest Insights and Forecast to 2034

IMARC Group has recently released a new research study titled “United States Sneaker Market Size, Share, Trends, and Forecast by Product Type, Category, Price Point, Distribution Channel, End User, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Sneaker Market Size & Share 2026-2034

The United States sneaker market size was valued at USD 26.7 Billion in 2025 and is projected to reach USD 40.1 Billion by 2034, expanding at a CAGR of 4.63% during 2026-2034. The market is driven by shifting fashion trends, increased health consciousness, and a growing preference for casual and athleisure wear.

Collaborations between brands, celebrities, and athletes continue to fuel demand, while rising e-commerce adoption and sneaker culture among youth further support the competitive United States sneaker market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 26.7 Billion
  • Projected Market Size (2034): USD 40.1 Billion
  • Growth Rate: CAGR of 4.63% (2026-2034)

Explore Opportunities in the United States Sneaker Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-sneaker-market/requestsample

Key Growth Drivers and Trends in the United States Sneaker Market

Growth in the United States sneaker market is being driven by the rise of athleisure and changing workplace norms, as more individuals embrace health-conscious lifestyles and demand for comfortable yet stylish footwear continues to grow. The athleisure trend reached USD 95.2 Billion in 2024 and is expected to grow at a CAGR of 7.26% from 2025 to 2033, while the casualization of workplace attire has normalized sneakers in office settings, expanding their utility beyond sports.

One of the leading United States sneaker market trends is celebrity collaborations and exclusive launches, as high-profile brand partnerships generate hype, drive demand, and build brand loyalty through limited-edition releases. In June 2025, NBA star Devin Booker unveiled the ‘Iridescent’ colorway of his Nike Book 1 sneakers, with an official launch in July 2025, tapping into pop culture and reinforcing sneaker culture through exclusivity and resale value.

Another key factor supporting United States sneaker market growth is innovation, sustainability, and digital reach, as brands adopt sustainable materials and ethical manufacturing practices to cater to eco-aware buyers. In March 2025, Gabriela Hearst’s luxury ‘Ohio’ sneakers incorporated water-based glue, leather from certified tanneries, 30% recycled rubber soles, and Global Recycled Standard-approved polyester stitching, while e-commerce platforms and social media continue to simplify purchasing and foster regional sneaker communities.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20404&flag=C

United States Sneaker Industry Segmentation Insights

Breakup by Product Type:

  • Low-Top Sneakers: Expected to capture the largest share due to unmatched versatility, lightweight design, and year-round appeal across casual and athletic use.
  • Mid-Top Sneakers: Strikes a balance between flexibility and ankle support, popular among active lifestyle consumers, particularly in transitional seasons.
  • High-Top Sneakers: Maintains strong market share driven by basketball culture, streetwear, and retro fashion trends such as Air Jordans.

Breakup by Category:

  • Branded: Anticipated to hold the largest share due to strong consumer trust, global recognition, and consistent brand innovation from Nike, Adidas, and New Balance.
  • Private Label: Gaining substantial traction through competitive pricing, improved quality, and exclusive retailer availability.

Breakup by Price Point:

  • Luxury: Expected to capture significant share as consumers, particularly millennials and Gen Z, view sneakers as status symbols and invest in designer collaborations.
  • Economic: Projected to hold a strong share due to rising price sensitivity and widespread demand for affordable, functional footwear.

Breakup by Distribution Channel:

  • Specialty Stores: Expected to dominate due to focused product offerings, expert staff, and tailored customer experiences.
  • Supermarkets and Hypermarkets: Maintains a strong presence through high foot traffic, wide assortment, and competitive pricing.
  • Brand Outlets: Anticipated to hold a major share by offering popular branded products at discounted prices.
  • Online Stores: Growing rapidly through e-commerce platforms and direct-to-consumer models.
  • Others: Includes additional retail formats supporting sneaker distribution.

Breakup by End User:

  • Men: Expected to hold a major share driven by lifestyle, sports, and fashion influences, along with athlete and influencer collaborations.
  • Women: Rapidly expanding as female consumers embrace athleisure, fitness routines, and fashion-forward footwear.
  • Kids: Holds a strong share driven by consistent parental spending on durable, comfortable, and affordable children’s footwear.

Breakup by Region:

  • Northeast: Driven by urban culture, fashion-forward consumers, and cities like New York and Boston serving as sneaker trend hubs.
  • Midwest: Supported by growing interest in health and fitness, sports culture, and expanding e-commerce access.
  • South: Driven by lifestyle preferences, warm weather, and trendsetting hubs like Atlanta, Houston, and Miami.
  • West: Driven by innovation, sustainability, and strong fitness culture, with Los Angeles and San Francisco leading in streetwear.

Key Challenges and Growth Opportunities in the United States Sneaker Market

The United States sneaker market faces challenges including intense competition among established and emerging brands, price sensitivity amid economic uncertainty, and the need for continuous innovation to keep pace with rapidly shifting fashion trends.

Despite these challenges, the market offers considerable growth opportunities driven by continued athleisure adoption, celebrity and brand collaborations, and rising demand for sustainable and technologically advanced sneakers. Expansion of e-commerce, resale marketplaces, and direct-to-consumer models are expected to create substantial opportunities for long-term growth in the United States sneaker market.

Competitive Landscape

The United States sneaker market features a highly competitive landscape dominated by global giants such as Nike, Adidas, Puma, and New Balance, which leverage extensive R&D, celebrity endorsements, and limited-edition releases to maintain market leadership. Emerging players and niche brands like Allbirds and On are gaining traction by focusing on sustainability, innovation, and direct-to-consumer models, while e-commerce platforms and resale marketplaces such as StockX and GOAT continue to reshape consumer access and pricing dynamics.

Recent Developments in the United States Sneaker Market

  • June 2025: Patta unveiled a new partnership with Nike with the release of the ‘The New Wave’ line of sneakers, incorporating their iconic ‘Wave’ design into the Air Max 90, with two colorways released so far.
  • May 2025: DICK’S Sporting Goods, Inc. announced plans to acquire Foot Locker, Inc., aiming to leverage Foot Locker’s sneaker expertise and brand portfolio including Champs Sports, WSS, atmos, and Kids Foot Locker.
  • April 2025: Under Armour announced the launch of the UA Echo, a sneaker blending street culture into sportswear with a bold, sculpted design and cutting-edge materials.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
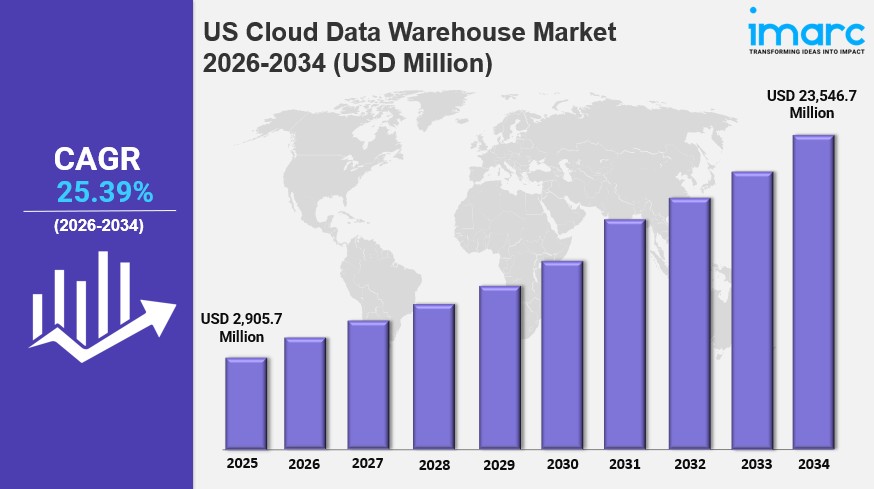
US Cloud Data Warehouse Market Size, Share, Trends & Growth Report 2026-2034

US Cloud Data Warehouse Market Size, Share, Trends & Growth Report 2026-2034

IMARC Group has recently released a new research study titled “US Cloud Data Warehouse Market Size, Share, Trends and Forecast by Offerings, Organization Size, Deployment Model, Application, Industry Vertical, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

US Cloud Data Warehouse Market Size & Share 2026-2034

The US cloud data warehouse market size reached USD 2,905.7 Million in 2025 and is projected to reach USD 23,546.7 Million by 2034, expanding at a CAGR of 25.39% during 2026-2034. The market is expanding as enterprises modernize legacy data systems, adopt cloud-native analytics, and integrate AI-driven tools.

Growth is further supported by hybrid and multi-cloud strategies, stringent compliance requirements, and rising demand for real-time insights, which are expected to strengthen the US cloud data warehouse market share across the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 2,905.7 Million
  • Projected Market Size (2034): USD 23,546.7 Million
  • Growth Rate: CAGR of 25.39% (2026-2034)

Explore Opportunities in the US Cloud Data Warehouse Market: Download the IMARC Sample Report: https://www.imarcgroup.com/us-cloud-data-warehouse-market/requestsample

Key Growth Drivers and Trends in the US Cloud Data Warehouse Market

Growth in the US cloud data warehouse market is being driven by rising adoption of DWaaS and AI-enhanced analytics, as organizations increasingly shift toward Data Warehouse-as-a-Service solutions to support scalable, pay-as-you-go models. These platforms enable businesses to unify structured and semi-structured data, while AI-powered query optimization improves performance, particularly for customer analytics and fraud detection. In August 2025, Snowflake’s shares surged approximately 14%, driven by strong demand for its AI-focused data platform offerings, and the company raised its annual product revenue forecast to USD 4.40 Billion, signaling enterprises’ accelerating investments in analytic services that harness AI in SQL-based data warehouses.

One of the leading US cloud data warehouse market trends is hybrid cloud deployment and regulatory compliance, as enterprises balance flexibility with regulatory requirements. A survey found that 69% of enterprises worldwide have adopted hybrid cloud, with 82% expecting to run enterprise workloads across hybrid environments by 2024, highlighting the model’s regulatory and operational appeal. Financial institutions and healthcare providers prefer hybrid or private deployments to meet data residency, privacy, and security standards while still leveraging the scalability of public cloud, with vendors integrating tokenization, role-based access controls, and encryption at scale to support compliance frameworks such as HIPAA, SOX, and GDPR.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=42115&flag=C

US Cloud Data Warehouse Industry Segmentation Insights

Breakup by Offerings:

  • DWaaS: Encompasses fully managed, scalable data warehouse services offered on a pay-as-you-go basis.
  • Data Storage: Covers underlying storage infrastructure supporting structured and semi-structured data management.

Breakup by Organization Size:

  • Large Enterprises: Drives substantial demand through investment in DWaaS and data storage solutions supporting large-scale analytics operations.
  • SME: Increasingly adopting DWaaS and data storage solutions to enable cost-effective digital transformation with minimal upfront investment.

Breakup by Deployment Model:

  • Public Cloud: Offers scalable, cost-efficient infrastructure widely adopted for flexible data warehouse deployment.
  • Private Cloud: Supports organizations with strict data residency, privacy, and security requirements.
  • Hybrid Cloud: Balances flexibility and regulatory compliance, gaining strong traction among financial and healthcare institutions.

Breakup by Application:

  • Customer Analytics: Supports data-driven insights into customer behavior and engagement patterns.
  • Data Modernization: Facilitates migration of legacy data systems to scalable, cloud-native platforms.
  • Business Intelligence: Enables organizations to derive actionable insights from unified enterprise data.
  • Predictive Analytics: Leverages AI and machine learning to forecast trends and support proactive decision-making.
  • Others: Includes additional application areas supporting specialized data warehouse use cases.

Breakup by Industry Vertical:

  • Healthcare: Relies on cloud data warehouses for secure, compliant management of patient and operational data.
  • Government: Depends on secure data storage and compliance infrastructure to support public sector digital services.
  • BFSI: Utilizes cloud data warehouses for regulatory compliance, fraud detection, and customer analytics.
  • IT and Telecom: Integrates cloud data warehousing to support growing connectivity and network data needs.
  • Retail and Consumer: Leverages data warehousing for customer analytics and supply chain optimization.
  • Manufacturing and Automotive: Uses cloud data warehouses to support operational efficiency and predictive maintenance.
  • Others: Includes additional industry verticals adopting cloud data warehouse solutions.

Breakup by Region:

  • Northeast: Benefits from dense concentration of financial institutions and enterprise technology adoption.
  • Midwest: Reflects steady demand driven by manufacturing and industrial data modernization needs.
  • South: Represents a leading regional market, supported by growing enterprise technology investment.
  • West: Benefits from strong presence of technology companies and cloud-native innovation hubs.

Key Challenges and Growth Opportunities in the US Cloud Data Warehouse Market

The US cloud data warehouse market faces challenges including data security and privacy concerns, complex regulatory compliance requirements across industries, and the need for skilled talent to manage advanced cloud-native analytics platforms.

Despite these challenges, the market offers considerable growth opportunities driven by continued adoption of AI-enhanced analytics, expansion of hybrid and multi-cloud strategies, and rising demand for real-time insights. Growing investment in data modernization and generative AI-powered querying tools are expected to create substantial opportunities for long-term growth in the US cloud data warehouse market.

Competitive Landscape

The US cloud data warehouse market is shaped by both established technology providers and emerging players expanding their footprint through platform enhancements and AI integration. Companies are investing in generative AI features, serverless architectures, and interoperability with data lakes to differentiate their offerings and meet growing enterprise demand for scalable, intelligent data warehousing solutions.

Recent Developments in the US Cloud Data Warehouse Market

  • April 2024: Snowflake announced a series of platform enhancements that embed generative AI for natural language query support, aiming to improve accessibility and reduce analytics complexity for enterprise users.
  • January 2025: Amazon Web Services (AWS) expanded its Redshift Serverless offerings in U.S. regions, enabling businesses to deploy large-scale data warehouses without managing infrastructure, further supporting cost optimization and flexibility.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
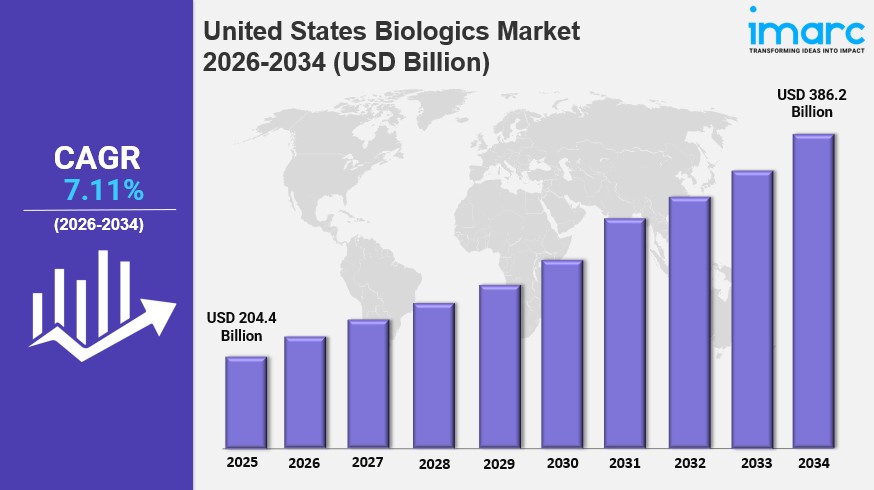
United States Biologics Market Size to Expand to USD 386.2 Billion by 2034

United States Biologics Market Size to Expand to USD 386.2 Billion by 2034

IMARC Group has recently released a new research study titled “United States Biologics Market Size, Share, Trends and Forecast by Source, Product, Disease, Manufacturing and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Biologics Market Size & Share 2026-2034

The United States biologics market size was valued at USD 204.4 Billion in 2025 and is projected to reach USD 386.2 Billion by 2034, expanding at a CAGR of 7.11% during 2026-2034. The market is primarily driven by the rapid adoption of bioprocessing technologies for efficiency, growing expansion of biosimilars addressing affordability, and rising AI integration in drug discovery, clinical trials, and manufacturing.

According to the CDC, an estimated 129 Million Americans have at least one chronic disease, with 42% managing two or more and 12% dealing with at least five conditions, and chronic diseases account for 90% of the annual USD 4.1 Trillion healthcare expenditure, highlighting the need for innovative biologics. Growing investments in research and development by biotech and pharmaceutical firms, alongside supportive FDA frameworks such as fast-track approvals, are expected to strengthen the United States biologics market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 204.4 Billion
  • Projected Market Size (2034): USD 386.2 Billion
  • Growth Rate: CAGR of 7.11% (2026-2034)

Explore Opportunities in the United States Biologics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-biologics-market/requestsample

Key Growth Drivers and Trends in the United States Biologics Market

Growth in the United States biologics market is being driven by growing adoption of advanced bioprocessing technologies, thus leading to highly improved efficiency in production and scalability. Technologies such as single-use bioreactors, continuous manufacturing, and high-throughput screening systems are streamlining manufacturing processes. Rentschler Biopharma’s Milford facility, operational since July 11, 2024, with four 2,000L single-use bioreactors, doubled cGMP capacity for complex biologics, supporting innovative therapies and global healthcare advancements while reducing production costs and enhancing biologics’ accessibility.

One of the leading United States biologics market trends is the rapid expansion of the biosimilars segment given growing demand for affordable alternatives to branded biologics. The FDA’s Biosimilar Approval Pathway has allowed easier market entry and increased competition while decreasing treatment costs, making biologic therapies more accessible for chronic diseases like cancer and autoimmune disorders. On July 2, 2024, Sobi began a rolling BLA submission for SEL-212, a novel biologic aimed at serum urate levels in chronic refractory gout, reflecting continued pharmaceutical investment in biosimilar research and development as patents for existing biologics expire.

Another key factor supporting United States biologics market growth is the ongoing integration of artificial intelligence in biologics development, speeding up drug discovery, optimizing clinical trials, and enhancing production processes. AI-powered platforms analyze enormous datasets to identify promising biologic candidates, cutting down time and cost involved in traditional R&D, while streamlining patient recruitment, monitoring real-time data, and predicting outcomes in clinical trials. On May 15, 2024, Galapagos NV and Blood Centers of America announced a partnership decentralizing CAR-T therapy manufacturing across 50 U.S. centers to ensure rapid seven-day vein-to-vein delivery and enhance scalability, physician control, and patient access.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20441&flag=C

United States Biologics Industry Segmentation Insights

Breakup by Source:

  • Microbial: Serves as an efficient host system for producing recombinant proteins, enzymes, and vaccines, with E. coli and yeast systems commonly employed for high-yield, cost-effective, and scalable manufacturing.
  • Mammalian: Critical for producing complex biologics such as monoclonal antibodies, fusion proteins, and cell therapies, with CHO cells dominating this segment given their superior post-translational modifications and bioactivity.
  • Others: Includes additional biologic source systems supporting specialized production needs.

Breakup by Product:

  • Monoclonal Antibodies: Represents a mainstay of the market, used widely for cancer, autoimmune diseases, and infections, with continued innovation in antibody-drug conjugates and bispecific antibodies.
  • Vaccines: Growing at an impressive rate, driven by advancements in mRNA technology, pandemic preparedness, and expanding research into cancer and personalized vaccines.
  • Recombinant Proteins: Widely used in treating diabetes, anemia, and growth disorders, with innovations in protein engineering enhancing therapeutic efficacy and stability.
  • Antisense, RNAi and Molecular Therapy: Represents an advancing therapeutic category leveraging molecular mechanisms to target disease at the genetic level.
  • Others: Includes additional biologic product categories serving specialized therapeutic needs.

Breakup by Disease:

  • Oncology: Leads the market given the significant occurrence of cancer and rising need for targeted treatments, with monoclonal antibodies and immune checkpoint inhibitors transforming cancer therapy.
  • Immunological Disorders: Witnessing strong growth with rising incidence of diseases like rheumatoid arthritis, psoriasis, and inflammatory bowel disease managed through cytokine inhibitors and TNF blockers.
  • Cardiovascular Disorders: Gaining ground through innovative treatments such as PCSK9 inhibitors for cholesterol regulation and growth in regenerative therapies.
  • Hematological Disorders: Represents a significant application area for biologic therapies addressing blood-related conditions.
  • Others: Includes additional disease categories benefiting from biologic therapy development.

Breakup by Manufacturing:

  • Outsourced: Increasing as companies rely on contract research and manufacturing organizations for effective, cost-efficient production, freeing up processes and providing access to sophisticated, scalable facilities.
  • In-House: Remains vital for companies prioritizing control over manufacturing processes, quality assurance, and intellectual property, particularly for high-value biologics like monoclonal antibodies and cell therapies.

Breakup by Region:

  • Northeast: Driven by a concentration of leading biotechnology and pharmaceutical companies, particularly in Massachusetts and New York, supported by robust R&D infrastructure and academic collaborations.
  • Midwest: Growing rapidly in biologics manufacturing, with significant contributions from Illinois and Indiana supported by an established pharmaceutical manufacturing base and government incentives.
  • South: Benefits from major biopharmaceutical companies and favorable business climates in states like North Carolina and Texas, alongside increasing clinical trial and biotechnology research activity.
  • West: Dominates biologics innovation, particularly in California, home to Silicon Valley’s biotechnology companies and strong venture capital funding for CAR-T cell therapies and mRNA vaccines.

Key Challenges and Growth Opportunities in the United States Biologics Market

The United States biologics market faces challenges including high manufacturing costs associated with complex biologic production, particularly for mammalian cell-based therapies, along with the technical complexity of scaling advanced bioprocessing technologies. Ensuring consistent quality and regulatory compliance across increasingly complex biologic modalities also remains an ongoing consideration for manufacturers.

Despite these challenges, the market offers considerable growth opportunities driven by expanding biosimilar adoption addressing affordability, growing integration of AI across drug discovery and manufacturing, and rising healthcare expenditure with positive reimbursement policy increasing patient access to biologic therapies. Continued advancement of personalized medicine addressing complex medical needs is expected to create substantial opportunities for long-term growth in the United States biologics market.

Competitive Landscape

Competition in the United States biologics market comes through key pharmaceutical and biotech innovators, which continue investing heavily in R&D activities. Major players boast advanced portfolios for next-generation monoclonal antibodies, vaccines, and gene therapies, while emerging startups and contract research organizations contribute niche biologics development and outsourcing solutions. Strategic partnerships and acquisitions often serve as primary market-positioning strategies, while advances in manufacturing technologies and personalized medicine continuously reshape the competitive landscape of this rapidly growing market.

Recent Developments in the United States Biologics Market

  • September 27, 2024: The FDA approved Dupixent (dupilumab) as the first biologic for inadequately controlled COPD with an eosinophilic phenotype, with Phase 3 trials showing exacerbation reductions of up to 34% and improved lung function.
  • February 29, 2024: Biocon Biologics Ltd signed a settlement and license agreement with Janssen Biotech to commercialize Bmab 1200, a biosimilar to Stelara, in the U.S. starting February 2025 pending FDA approval, resolving a patent dispute and supporting Biocon’s immunology franchise expansion.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Tequila Market Size to Hit USD 13.8 Billion in 2034 | Grow CAGR by 4.19%

United States Tequila Market Size to Hit USD 13.8 Billion in 2034 | Grow CAGR by 4.19%

IMARC Group has recently released a new research study titled “United States Tequila Market Size, Share, Trends and Forecast by Product Type, Purity, Price Range, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Tequila Market Size & Share 2026-2034

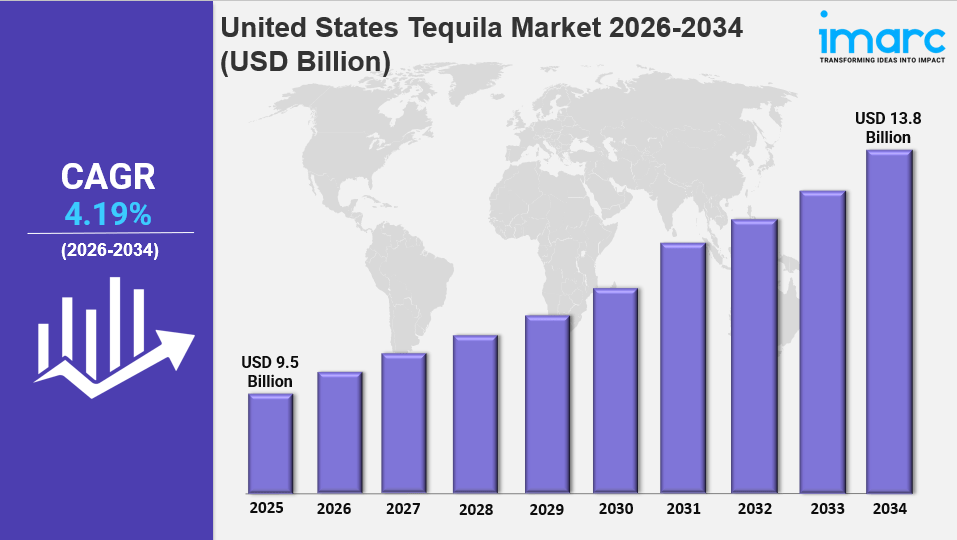
The United States tequila market size was valued at USD 9.5 Billion in 2025 and is projected to reach USD 13.8 Billion by 2034, expanding at a CAGR of 4.19% during 2026-2034. The market is witnessing steady expansion, impacted by magnifying requirement for artisanal and premium products, transforming customer choices, and the proliferating popularity of cocktails.

Growth in 2026 is further reinforced by bolstering agave spirit imports and advancements addressing the younger consumer segment, sustainability, and authenticity. As tequila continues gaining recognition as a refined, health-conscious spirit choice, these dynamics are expected to strengthen the United States tequila market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 9.5 Billion
  • Projected Market Size (2034): USD 13.8 Billion
  • Growth Rate: CAGR of 4.19% (2026-2034)

Explore Opportunities in the United States Tequila Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-tequila-market/requestsample

Key Growth Drivers and Trends in the United States Tequila Market

Growth in the United States tequila market is being driven by the continued premiumization of tequila, as customers increasingly look for authenticity and better quality, escalating a shift toward 100% agave tequila, especially aged variations such as Reposado and Añejo. In August 2024, Humano, a tequila company, launched in the United States with four varieties including Joven, Blanco, Añejo, and Reposado, reflecting this broader inclination in the alcohol sector where customers are receptive to spending on premium beverages that provide unique flavor attributes and artisanal craftsmanship.

One of the leading United States tequila market trends is the rise in tequila-based cocktails, as cocktail culture rapidly expands and tequila emerges as an integral component in drinks like the margarita, Tequila Sour, and Paloma. In Q1 2024, Proximo Spirits, a major U.S.-based tequila brand with a robust presence in the Paloma category, recorded a 1% rise in overall sales, with the U.S. region showing 7.4% growth compared to the same period in 2023, reflecting bolstering demand for premium and versatile tequila expressions among mixologists and consumers alike.

Another key factor supporting United States tequila market growth is rising sustainability and eco-friendly practices, as customers and producers gain more awareness regarding environmental impact. In August 2024, DE-NADA Tequila, a U.S.-based brand, announced new sustainable packaging strengthening its carbon-neutral certification, including a new aluminum bottle for its Blanco and Reposado spirits with a 100% sustainable cork topper, reflecting an elevating consumer inclination toward eco-conscious, ethical products across the tequila category.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=3777&flag=C

United States Tequila Industry Segmentation Insights

Breakup by Product Type:

  • Blanco: Holds the largest market share, driven by its versatility and pure flavor profile, offering a clean, crisp taste ideal for cocktails including margaritas and tequila sours.
  • Joven: Represents a blended style appealing to consumers seeking balanced flavor profiles.
  • Mixto Gold: Serves a more affordable segment of the market with broader mainstream appeal.
  • Reposado: Benefits from rising demand for aged expressions offering richer, more complex flavor notes.
  • Anejo: Appeals to consumers seeking extended barrel-aged, premium tequila experiences.
  • Extra Anejo: Represents the most extensively aged category, favored by connoisseurs and collectors.

Breakup by Purity:

  • 100% Tequila: Leads the market as consumers increasingly prioritize quality and authenticity, made exclusively from blue agave offering a smoother, purer taste free from added sugars or flavorings.
  • 60% Tequila: Also known as mixto tequila, holds a smaller share due to lower purity but remains prevalent given its price competitiveness and widespread retail availability.

Breakup by Price Range:

  • Premium Tequila: Commands the largest market share, reflecting growing demand for high-quality, aged expressions such as Reposado and Añejo undergoing extended oak barrel aging.
  • Value Tequila: Serves budget-conscious consumers seeking accessible entry points into the category.
  • Premium and Super-Premium Tequila: Benefits from rising consumer interest in fine dining and craft cocktail experiences.
  • Ultra-Premium Tequila: Represents the top tier of the market, favored by consumers seeking exclusive, organically sourced and additive-free expressions.

Breakup by Distribution Channel:

  • On-Trade: Captures the largest market share, including restaurants and bars, liquor stores, and others, benefiting from the increasing popularity of tequila-based cocktails in casual and high-end establishments alike.
  • Off-Trade: Includes supermarkets and hypermarkets, discount stores, online stores, and others, providing broad retail access for at-home tequila consumption.

Breakup by Region:

  • West: Holds the largest market share, driven by proximity to Mexico and a long-standing affinity for tequila-based beverages, with California, Arizona, and Nevada experiencing exponential growth in premium and super-premium segments.
  • South: Benefits from strong cultural affinity for Mexican cuisine and flavors, with Texas, Florida, and Louisiana exhibiting high tequila consumption rates.
  • Northeast: Driven by affluent consumers and a vibrant cocktail culture in major metropolitan cities like New York and Boston.
  • Midwest: Experiencing a gradual yet notable rise in tequila consumption as consumer preferences diversify beyond whiskey and beer.

Key Challenges and Growth Opportunities in the United States Tequila Market

The United States tequila market faces challenges including price volatility tied to agave supply cycles, intense competition among established international producers and emerging craft distillers, and the need for continuous product innovation to maintain consumer engagement. Ensuring consistent quality and authenticity amid rising demand for 100% agave products also requires sustained investment in sourcing and production transparency.

Despite these challenges, the market offers considerable growth opportunities driven by continued premiumization, expanding tequila-based cocktail culture, and growing consumer preference for sustainable, additive-free products. Rising domestic agave cultivation, including over 400 acres dedicated to agave farming in California, along with expanding distribution partnerships, are expected to create substantial opportunities for long-term growth in the United States tequila market.

Competitive Landscape

The United States tequila market is intensely competitive, with major international producers dominating the premium and super-premium categories through strong brand recognition and extensive distribution networks, while emerging craft distillers gain traction by emphasizing authenticity, sustainability, and innovation. In January 2025, Cincoro Tequila announced a strategic distribution agreement with Southern Glazer’s Wine & Spirits, expanding distribution to seven new markets including Maryland, Illinois, Florida, Colorado, Delaware, and Minnesota, raising its total market count to 43. Key players include Bacardi and Company Ltd., Diageo PLC, Pernod Ricard, Constellation Brands Inc., Suntory Holdings Limited, Heaven Hill Distilleries Inc., Campari Group, Casa Aceves, Sazerac Company Inc., and Brown-Forman Corporation.

Recent Developments in the United States Tequila Market

  • November 2024: Maguey Spirits’ U.S. distribution arm Maguey Imports strategically acquired Pasote Tequila and Bozal Mezcal to boost Mexico’s agave spirits legacy while offering the craftsmanship of these two Mexico-based brands.
  • September 2024: Reserva de la Familia, a major Añejo Tequila brand, collaborated with MICHELIN Guide U.S. as its official tequila partner for 2025, promoting premium Mexican cuisine across the United States.
  • March 2024: Tequila Ocho unveiled new packaging launching across the U.S., highlighting the company’s dedication to showcasing terroir in spirits.
  • January 2024: Zamora Co announced plans to expand its footprint in the United States tequila segment with its upcoming Volteo brand, produced by Destileria Casa De Piedra and both additive-free and organic.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
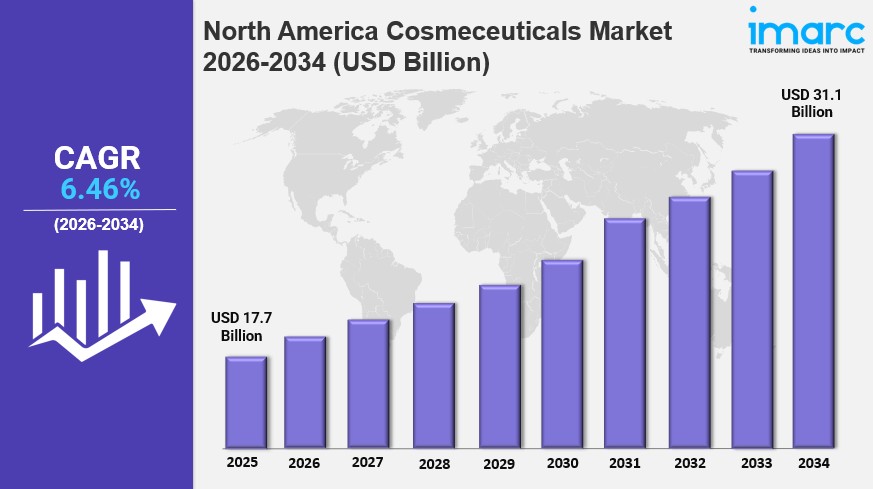
North America Cosmeceuticals Market Size, Share, Growth, Trends Analysis, Report 2026-2034

North America Cosmeceuticals Market Size, Share, Growth, Trends Analysis, Report 2026-2034

IMARC Group has recently released a new research study titled “North America Cosmeceuticals Market Size, Share, Trends and Forecast by Product Type, Distribution Channels, and Country, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

North America Cosmeceuticals Market Size & Share 2026-2034

The North America cosmeceuticals market size reached USD 17.7 Billion in 2025 and is projected to reach USD 31.1 Billion by 2034, expanding at a CAGR of 6.46% during 2026-2034. The market is driven by increasing consumer awareness of skincare benefits, aging populations seeking anti-aging solutions, and demand for science-backed, high-efficacy products.

Growth in 2026 is further supported by rising preference for clean, sustainable, and natural formulations, coupled with advancements in cosmetic science and digital marketing. These dynamics are expected to strengthen the North America cosmeceuticals market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 17.7 Billion
  • Projected Market Size (2034): USD 31.1 Billion
  • Growth Rate: CAGR of 6.46% (2026-2034)

Explore Opportunities in the North America Cosmeceuticals Market: Download the IMARC Sample Report: https://www.imarcgroup.com/north-america-cosmeceuticals-market/requestsample

Key Growth Drivers and Trends in the North America Cosmeceuticals Market

Growth in the North America cosmeceuticals market is being driven by rising demand for anti-aging and skin rejuvenation products, as the population ages, particularly with the baby boomer generation reaching their older years, increasing emphasis on keeping skin young and healthy-looking. Consumers want latest-generation formulations that offer both cosmetic and pharmaceutical benefits, including peptides, retinoids, and hyaluronic acid, to smooth wrinkles, increase skin elasticity, and promote overall skin texture, while the growing popularity of preventive skincare practices among younger consumers is further driving the trend.

One of the leading North America cosmeceuticals market trends is the increasing popularity of clean and sustainable cosmeceuticals, as consumers become more conscious of the environmental and health impacts of their skincare choices. More consumers are leaning toward chemical-free, paraben-free, and synthetic fragrance-free products, prompting brands to widely adopt sustainable packaging, reduce carbon footprints, and pursue cruelty-free and vegan certifications. An industry report indicates that 68% of consumers currently place a high priority on clean-label skin care products, with 41% influenced by social media.

Another key factor supporting North America cosmeceuticals market growth is continued innovation in sustainably sourced ingredients, as brands respond to consumer demand for pure, natural formulations. On January 30, 2025, TRI-K launched OleaClear Olive Squalane, a sustainable, plant-derived emollient designed to provide deep hydration and moisture retention in skincare products such as creams and lipsticks, featuring a natural origin index of 1 and holding COSMOS, REACH, vegan, halal, and kosher certifications, reflecting how clean and sustainable formulations are becoming a key differentiator across the market.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=28648&flag=C

North America Cosmeceuticals Industry Segmentation Insights

Breakup by Product Type:

  • Skin Care: This segment represents a major category in the North America cosmeceuticals market, driven by increasing consumer focus on skin health, appearance, and preventive care.
    • Anti-Aging: Products target wrinkles, fine lines, pigmentation, and loss of skin elasticity, supported by growing demand for youthful-looking skin.
    • Anti-Acne: Includes treatments designed to manage acne, blemishes, and excess oil, particularly among younger consumers.
    • Sun Protection: Includes advanced sunscreens and UV-protection products that help prevent sun damage, premature aging, and pigmentation.
    • Moisturizers: Formulated to improve hydration, strengthen the skin barrier, and address dryness and sensitivity.
    • Others: Includes products targeting pigmentation, skin brightening, redness, and other specific skin concerns.
  • Hair Care: The segment includes specialized products addressing common hair and scalp concerns, with rising demand for clinically backed and ingredient-focused formulations.
    • Hair Fall: Products are designed to reduce hair loss and support stronger, healthier hair growth.
    • Anti-Dandruff: Targets dandruff, scalp irritation, and flaking through specialized cleansing and treatment formulations.
    • Hair Colorants: Includes products offering hair coloring while incorporating conditioning and protective ingredients.
    • Others: Covers products for hair repair, scalp care, hair strengthening, and damage protection.
  • Oral Care: Includes specialized toothpastes, mouthwashes, whitening products, and other formulations designed to improve oral hygiene and address specific dental concerns. Growing awareness of preventive oral healthcare is supporting demand.
  • Others: Includes cosmeceutical products across areas such as body care, nail care, and specialized personal care. Innovation in active ingredients and multifunctional formulations is creating additional growth opportunities in this segment.

Breakup by Distribution Channels:

  • Hypermarkets and Supermarkets: Provides broad retail access and convenience for everyday cosmeceutical product purchases.
  • Convenience Stores: Serves quick, accessible purchase occasions for cosmeceutical essentials.
  • Online Stores: Growing rapidly, driven by expanding e-commerce adoption and digital marketing reaching health-conscious consumers.
  • Specialty Stores: Offers curated selections and expert guidance for premium and clinically validated cosmeceutical products.
  • Others: Includes additional retail formats supporting cosmeceuticals distribution.

Breakup by Country:

  • United States: Represents the largest market within the region, driven by strong consumer spending power, an aging population, and a well-established dermatological and cosmeceutical industry base.
  • Canada: Benefits from rising consumer awareness of clean beauty and growing demand for clinically validated skincare solutions.

Key Challenges and Growth Opportunities in the North America Cosmeceuticals Market

The North America cosmeceuticals market faces challenges including regulatory complexity around ingredient claims and product classification, along with the need for continuous investment in clinical validation to substantiate efficacy claims. Intense competition among established and emerging brands also requires sustained investment in product differentiation and digital marketing to maintain consumer trust and market visibility.

Despite these challenges, the market offers considerable growth opportunities driven by rising demand for anti-aging and preventive skincare solutions, expanding clean and sustainable product lines, and growing consumer reliance on digital and social media channels for product discovery. Continued innovation in dermatologically validated formulations and sustainably sourced ingredients is expected to create substantial opportunities for long-term growth in the North America cosmeceuticals market.

Competitive Landscape

The North America cosmeceuticals market is highly competitive, with established dermatological brands and emerging innovators focusing on clinical validation, clean formulation, and strategic partnerships to strengthen their market position. Companies are investing in science-backed ingredient innovation, sustainable packaging, and digital marketing to build consumer trust, while forming collaborations to expand their presence and capture the growing demand for high-efficacy, clean-label skincare and haircare products across the region.

Recent Developments in the North America Cosmeceuticals Market

  • December 2024: K-beauty brand MDP+, a subsidiary of Medipeel, expanded its U.S. presence by introducing four new cosmeceutical products, including a vegan hyaluronic acid sunscreen and a peptide-infused plumping mask, increasing its total product range to 13 and addressing rising U.S. demand for collagen and peptide-based solutions.
  • June 2024: Hugel Inc. formed a partnership with BENEV Company Inc. to enter the U.S. market with its botulinum toxin product, Letybo, aiming to secure a 10% share of the U.S. market within three years by combining Hugel’s global toxin business with BENEV’s strong growth in medical aesthetics.
  • March 2024: Obagi Cosmeceuticals, a division of Waldencast plc, introduced the Daily Hydro-Drops Rejuvenating Eye Gel Cream, a medical-grade skincare solution priced at USD 75, incorporating Niacinamide and Isoplentix technology, with clinical testing showing 89% of participants observing decreased dryness after one week of use.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302