Category: Uncategorized

United States Pharmacy Market Size to Worth USD 937.4 Billion by 2034

United States Pharmacy Market Size to Worth USD 937.4 Billion by 2034

IMARC Group has recently released a new research study titled “United States Pharmacy Market Report by Product Type (Prescription, OTC), Pharmacy Type (Hospital Pharmacy, Retail Pharmacy, ePharmacy, and Others), Ownership (Independent, Chain), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Pharmacy Market Size & Share 2026-2034

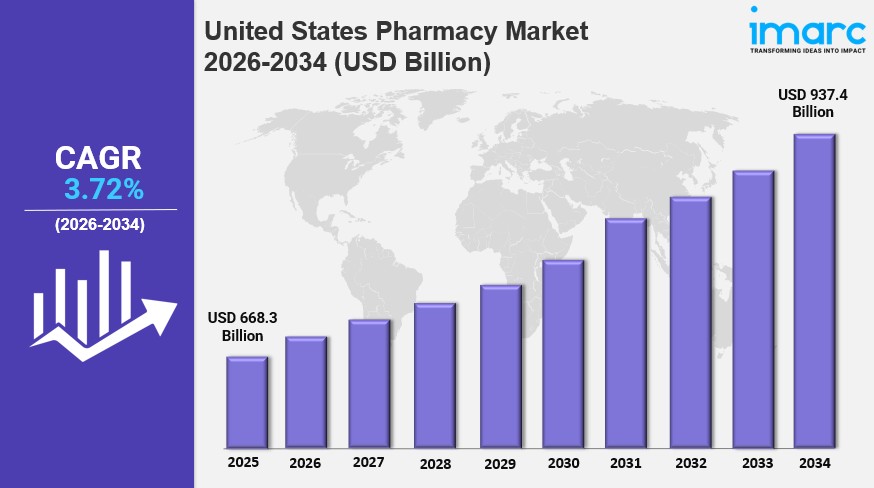
The United States pharmacy market size reached USD 668.3 Billion in 2025 and is projected to reach USD 937.4 Billion by 2034, expanding at a CAGR of 3.72% during 2026-2034. In 2026, the market continues to gain momentum, shaped by the rising incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions, an aging population, and the growing adoption of ePharmacy and digital health solutions.

Growth in 2026 is further reinforced by the expanding role of pharmacists in patient-centered care, including immunizations, medication counseling, and chronic disease management, along with ongoing advancements in medical research and specialty drug development. These dynamics are expected to strengthen the United States pharmacy market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 668.3 Billion
  • Projected Market Size (2034): USD 937.4 Billion
  • Growth Rate: CAGR of 3.72% (2026-2034)

Explore Opportunities in the United States Pharmacy Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-pharmacy-market/requestsample

Key Growth Drivers and Trends in the United States Pharmacy Market

Growth in the United States pharmacy market is being driven primarily by the increasing incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions. As the burden of these long-term conditions rises, fueled by lifestyle changes and environmental factors, demand for a diverse range of medications continues to grow.

One of the leading United States pharmacy market trends is the aging demographic. The elderly typically require a higher volume of medications and healthcare services, contributing substantially to prescription volumes. This is complemented by a growing regional population, rising healthcare awareness, and increased access to healthcare services, all of which sustain upward pressure on demand for pharmaceutical products.

Another key factor supporting United States pharmacy market growth is the expanding role of e-commerce and digital health solutions. Online pharmacies and telehealth platforms are gaining traction, offering consumers a convenient and efficient way to fulfill their healthcare needs. In parallel, advancements in medical research and technology, the development of specialty drugs, personalized medicine, and the expansion of retail pharmacy chains are shaping the future dynamics of the market.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21066&flag=C

United States Pharmacy Industry Segmentation Insights

Breakup by Product Type:

  • Prescription: Medications dispensed only on a prescription from a licensed healthcare provider, covering chronic, acute, and specialty therapies.
  • OTC: Over-the-counter medicines that consumers can purchase without a prescription for common and self-treatable conditions.

Breakup by Pharmacy Type:

  • Hospital Pharmacy: Pharmacies operating within hospitals and health systems, supplying medications for inpatient care and outpatient needs.
  • Retail Pharmacy: Community and drugstore pharmacies that dispense prescriptions and sell OTC products, and provide services such as counseling and immunizations.
  • ePharmacy: Online pharmacies and digital platforms that enable customers to order prescription and OTC products for home delivery.
  • Others: Includes other dispensing channels such as mail-order and specialty pharmacy formats.

Breakup by Ownership:

  • Independent: Locally owned pharmacies that offer personalized service and close relationships with patients in their communities.
  • Chain: Multi-location pharmacy networks operating under common ownership, benefiting from scale, wide geographic reach, and purchasing power.

Breakup by Region:

  • Northeast: A densely populated region with a large base of hospitals, health systems, and pharmacy locations serving demand for prescription and OTC products.
  • Midwest: A region combining urban centers and smaller communities, where chain and independent pharmacies both play an important role in medication access.
  • South: A large and growing region whose population base supports sustained demand for prescription medications and pharmacy services.
  • West: A region with strong adoption of digital health, telehealth, and ePharmacy solutions alongside a broad network of retail pharmacies.

Key Challenges and Growth Opportunities in the United States Pharmacy Market

The United States pharmacy market faces challenges including thin prescription reimbursement, rising operating costs, and intensifying competition from big-box retailers and online pharmacies, which are pressuring traditional drugstore models.

Despite these challenges, the market offers considerable growth opportunities driven by the rising burden of chronic diseases, an aging population, the expansion of ePharmacy and telehealth services, and the growth of specialty drugs and personalized medicine. The broader role of pharmacists in immunizations and chronic disease management is also expected to support long-term growth.

Competitive Landscape

The United States pharmacy market is highly competitive and is shaped by large national chains and retailers such as CVS Health, Walgreens, Walmart, and Kroger, alongside digital entrants such as Amazon Pharmacy. Key players focus on expanding services, strengthening home delivery and online ordering, and integrating healthcare offerings. The IMARC report examines the competitive landscape, including market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with profiles of the major companies.

Recent Developments in the United States Pharmacy Market

  • August 2025: Sycamore Partners completed its acquisition of Walgreens Boots Alliance in a deal valued at around USD 10 billion, taking Walgreens private as a standalone company under new CEO Mike Motz.
  • November 2020: Amazon launched Amazon Pharmacy, allowing prescriptions to be sent to Amazon with free two-day delivery for Prime members.
  • June 2018: Amazon acquired online pharmacy PillPack for around USD 1 billion, marking its entry into the prescription pharmacy market.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
North America Active Pharmaceutical Ingredients Market Size Worth USD 133.0 Billion by 2034 | CAGR: 5.17%: IMARC Group

North America Active Pharmaceutical Ingredients Market Size Worth USD 133.0 Billion by 2034 | CAGR: 5.17%: IMARC Group

IMARC Group has recently released a new research study titled “North America Active Pharmaceutical Ingredients Market Size, Share, Trends and Forecast by Drug Type, Manufacturer Type, Synthesis Type, Therapeutic Application, and Country, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

North America Active Pharmaceutical Ingredients Market Size & Share 2026-2034

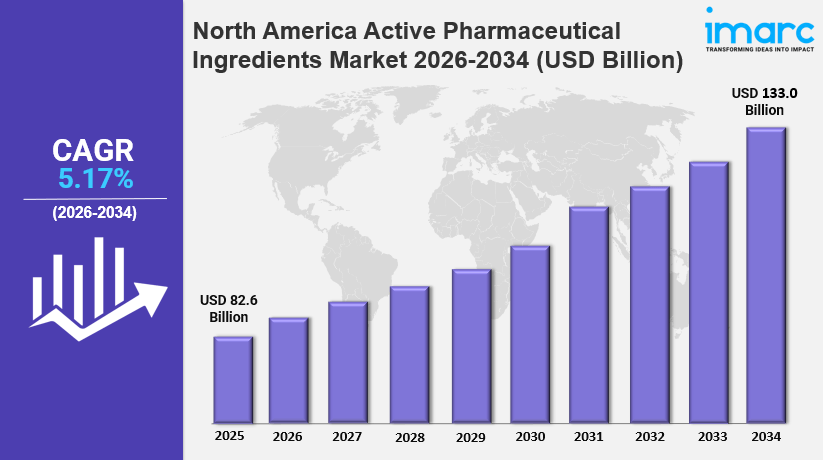
The North America active pharmaceutical ingredients market size was valued at USD 82.6 Billion in 2025 and is projected to reach USD 133.0 Billion by 2034, expanding at a CAGR of 5.17% during 2026-2034. In 2026, the market continues to gain momentum, driven by increasing healthcare needs, novel drug formulations, strong research activities, strict compliance standards, and rising demand for cost-effective treatments.

Growth in 2026 is further reinforced by the incorporation of advanced technologies and synergistic partnerships that have improved efficiency in addressing evolving therapeutic needs. These dynamics are expected to strengthen the North America active pharmaceutical ingredients market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 82.6 Billion
  • Projected Market Size (2034): USD 133.0 Billion
  • Growth Rate: CAGR of 5.17% (2026-2034)
  • Leading Drug Type (2025): Innovative Active Pharmaceutical Ingredients
  • Leading Manufacturer Type (2025): Captive API Manufacturers
  • Leading Synthesis Type (2025): Synthetic Active Pharmaceutical Ingredients
  • Leading Therapeutic Application (2025): Oncology
  • Leading Country: United States

Explore Opportunities in the North America Active Pharmaceutical Ingredients Market: Download the IMARC Sample Report: https://www.imarcgroup.com/north-america-active-pharmaceutical-ingredients-market/requestsample

Key Growth Drivers and Trends in the North America Active Pharmaceutical Ingredients Market

Growth in the North America active pharmaceutical ingredients market is being driven primarily by the increasing number of chronic diseases such as diabetes, cardiovascular diseases, and cancer, which require innovative and effective drugs. On June 12, 2024, the U.S. Centers for Medicare and Medicaid Services reported that national healthcare spending grew 7.5% in 2023 to USD 4.8 trillion, outpacing GDP growth of 6.1%. Regulatory frameworks that encourage domestic production over imports are also supporting the market. A January 2024 report by the Active Pharmaceutical Ingredient Innovation Center (APIIC) addressed dependence on foreign API sources and recommended advanced manufacturing technologies, public incentives, and public-private partnerships to reshore production of critical APIs.

One of the leading North America active pharmaceutical ingredients market trends is the integration of advanced technologies such as artificial intelligence (AI). AI is used to optimize chemical synthesis routes, predict molecular behavior, reduce development times, monitor manufacturing parameters in real time, and enable predictive maintenance of equipment. On June 25, 2024, Eli Lilly announced a partnership with OpenAI to use AI in discovering treatments for drug-resistant diseases, including novel antimicrobials. The adoption of sustainable manufacturing practices is another trend, with green chemistry techniques such as solvent-free operations, biocatalysis, and continuous flow chemistry helping to reduce waste and environmental impact.

Another key factor supporting North America active pharmaceutical ingredients market growth is the rise in biologics API production. Demand for monoclonal antibodies, therapeutic proteins, and vaccines is increasing, leading to specialized API manufacturing supported by recombinant DNA technology, cell culture systems, single-use bioreactors, and continuous bioprocessing. In May 2024, Eli Lilly committed an additional USD 5.3 billion to a new manufacturing site in Indiana to increase production of the diabetes and weight loss drugs Mounjaro and Zepbound.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1521&flag=C

North America Active Pharmaceutical Ingredients Industry Segmentation Insights

Breakup by Drug Type:

  • Innovative Active Pharmaceutical Ingredients: The leading segment in 2025, essential for addressing complex and unmet medical needs in areas such as cardiology, oncology, and rare diseases, and supported by the focus on biologics and precision medicine.
  • Generic Active Pharmaceutical Ingredients: APIs used in off-patent medicines, supported by growing demand for cost-effective treatments.

Breakup by Manufacturer Type:

  • Captive API Manufacturers: The leading segment in 2025, in which pharmaceutical companies produce APIs in-house, giving them control over quality, pricing, and production time and reducing dependence on external suppliers.
  • Merchant API Manufacturers: Independent producers that supply APIs to pharmaceutical companies, divided into Innovative Merchant API Manufacturers and Generic Merchant API Manufacturers.

Breakup by Synthesis Type:

  • Synthetic Active Pharmaceutical Ingredients: The leading segment in 2025, covering Innovative Synthetic APIs and Generic Synthetic APIs. These are used mainly in small-molecule drugs for conditions such as cardiovascular disease, diabetes, and neurological disorders, and benefit from cost-effective, scalable production.
  • Biotech Active Pharmaceutical Ingredients: APIs produced using biological systems, segmented by drug type (Innovative Biotech APIs and Biosimilars), product type (Monoclonal Antibodies, Vaccines, Cytokines, Others), and expression system (Mammalian, Microbial, Yeast, Others).

Breakup by Therapeutic Application:

  • Oncology: The leading segment in 2025, driven by rising cancer prevalence, investment in cancer research, targeted therapies, immunotherapy, and the need for high-quality APIs.
  • Cardiovascular and Respiratory: APIs used in medicines for heart, circulatory, and breathing disorders.
  • Diabetes: APIs used in treatments for diabetes and related metabolic conditions.
  • Central Nervous System Disorders: APIs used in treatments for conditions affecting the central nervous system.
  • Neurological Disorders: APIs used in treatments for neurological conditions.
  • Others: Includes other therapeutic areas not captured in the categories above.

Breakup by Country:

  • United States: The dominant country, supported by strong pharmaceutical and biotechnology industries, advanced R&D infrastructure, FDA regulatory oversight, a rising elderly population, and a strong presence of captive API manufacturers and contract development organizations.
  • Canada: A regional market supported by healthcare needs and pharmaceutical activity.
  • Mexico: A regional market with growing pharmaceutical demand.

Key Challenges and Growth Opportunities in the North America Active Pharmaceutical Ingredients Market

The North America active pharmaceutical ingredients market faces challenges linked to dependence on foreign API sources, supply chain disruptions, and drug shortages. Strict regulatory and compliance standards also require continued investment in quality, scalability, and cost-effectiveness.

Despite these challenges, the market offers considerable growth opportunities driven by government initiatives and private investment in domestic API production, reshoring of critical APIs, and rising demand for complex APIs such as biologics and high-potency drugs. Advances in continuous manufacturing, green chemistry, and AI-enabled production, along with growth in biologics and biosimilars, are expected to support long-term growth.

Competitive Landscape

The North America active pharmaceutical ingredients market is highly competitive, shaped by advances in manufacturing technology and a strong emphasis on innovation. Manufacturers compete by adopting newer processes such as continuous manufacturing and green chemistry to improve efficiency and regulatory compliance, and growing demand for complex APIs such as biologics and high-potency drugs is driving investment in high-tech facilities. Competition is intensified by continuous efforts to ensure quality, scalability, and cost-effectiveness while addressing supply chain resilience and local demand. The IMARC report examines the competitive landscape along with profiles of the key players.

Recent Developments in the North America Active Pharmaceutical Ingredients Market

  • April 9, 2024: The API Innovation Center announced a partnership with Apertus Pharmaceuticals to manufacture the API for the cancer drug lomustine domestically in the United States using advanced continuous manufacturing, ensuring a reliable and cost-effective supply for glioblastoma treatment and reducing dependence on foreign sources.
  • March 15, 2024: Noramco launched the Noramco Group, integrating its subsidiaries Purisys and Halo Pharma, with plans to address U.S. drug shortages and quality concerns by improving supply chain reliability, encouraging domestic production, and reducing logistics costs.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Canada Hair Care Market Size is Expected to Reach USD 2,613.6 Million by 2034 | CAGR 3.56%

Canada Hair Care Market Size is Expected to Reach USD 2,613.6 Million by 2034 | CAGR 3.56%

IMARC Group has recently released a new research study titled “Canada Hair Care Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Canada Hair Care Market Size & Share 2026-2034

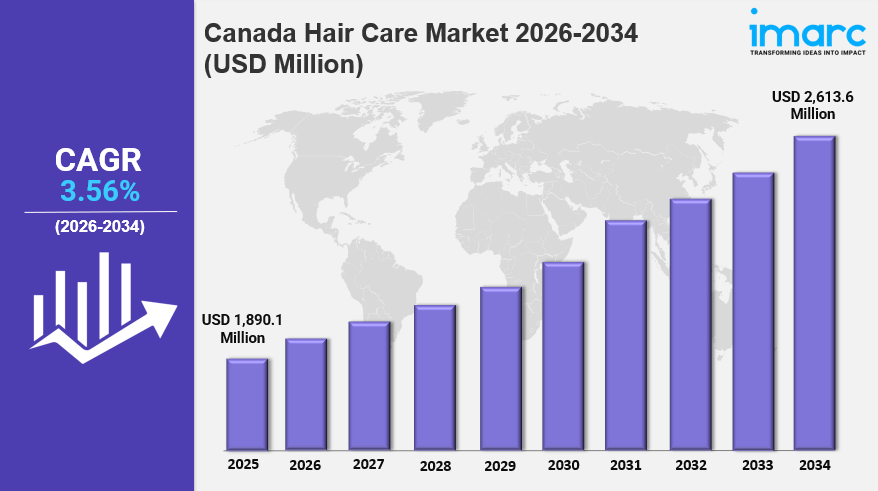
The Canada hair care market size reached USD 1,890.1 Million in 2025 and is projected to reach USD 2,613.6 Million by 2034, expanding at a CAGR of 3.56% during 2026-2034. In 2026, the market continues to gain momentum, shaped by rising consumer focus on personal grooming, growing demand for organic and sulfate-free products, and increased awareness about scalp health.

Growth in 2026 is further reinforced by innovation in product formulations and targeted marketing across digital platforms, which are enhancing brand visibility and customer engagement. These dynamics are expected to strengthen the Canada hair care market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 1,890.1 Million
  • Projected Market Size (2034): USD 2,613.6 Million
  • Growth Rate: CAGR of 3.56% (2026-2034)

Explore Opportunities in the Canada Hair Care Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-hair-care-market/requestsample

Key Growth Drivers and Trends in the Canada Hair Care Market

Growth in the Canada hair care market is being driven primarily by rising consumer focus on personal grooming and growing demand for organic and sulfate-free products. Increased awareness about scalp health and continued innovation in product formulations are also supporting the market, while targeted marketing across digital platforms is enhancing brand visibility and customer engagement.

One of the leading Canada hair care market trends is the rising demand for natural and organic hair products. Consumers in Canada are favoring products made with natural, organic, and chemical-free ingredients, and growing awareness of the adverse impact of sulfates, parabens, and artificial perfumes is pushing a shift toward cleaner and more sustainable formulas. Brands are launching plant-based shampoos, conditioners, and treatments enriched with botanical ingredients such as aloe vera, argan oil, and tea tree, a trend especially visible among Millennials and Gen Z. Retailers and e-commerce stores are increasing shelf space for green beauty brands. In November 2024, DESIGNME, a salon-originated Canadian hair care brand known for its professional-grade vegan formulations, announced its entry into the U.S. market through a retail collaboration with Nordstrom.

Another key factor supporting Canada hair care market growth is the rising focus on scalp health and targeted hair treatments. Consumers increasingly treat scalp issues as part of their wellness routines, and concerns about dandruff, hair thinning, and product buildup are lifting demand for scalp serums, exfoliating scrubs, anti-inflammatory shampoos, and hair growth treatments. The popularity of skinification, which treats hair and scalp like skincare, has led brands to innovate with active ingredients such as niacinamide, salicylic acid, and biotin. Educational marketing and dermatologist-endorsed formulations are strengthening trust and adoption, creating new product segments and revenue streams.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=37993&flag=C

Canada Hair Care Industry Segmentation Insights

Breakup by Product Type:

  • Shampoo: Cleansing products for hair and scalp, including sulfate-free, plant-based, and targeted scalp-care formulations.
  • Hair Color: Products used to change or enhance hair color at home or in salons.
  • Conditioner: Products that moisturize, detangle, and improve the condition of hair after cleansing.
  • Hair Styling Products: Products such as gels, sprays, creams, and serums used to shape and finish hairstyles.
  • Others: Includes treatments, scalp serums, masks, and other hair care products not captured above.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Large-format retail outlets offering a broad range of hair care brands in one place.
  • Specialty Stores: Beauty and personal care retailers offering curated and premium hair care assortments, such as Sephora Canada.
  • Convenience Stores: Neighborhood outlets offering quick access to everyday hair care essentials.
  • Online Retailers: E-commerce platforms offering wide choice and convenience, including Amazon.ca’s Premium Beauty store.
  • Others: Includes salons and other retail formats not captured above.

Breakup by Region:

  • Ontario: Canada’s most populous province, with a large consumer base and extensive retail and salon networks.
  • Quebec: A large provincial market with a strong beauty and personal care culture.
  • Alberta: A province whose consumers and retail base support steady demand for hair care products.
  • British Columbia: A province where demand for natural and wellness-oriented products is notable.
  • Others: Includes the remaining provinces and territories.

Key Challenges and Growth Opportunities in the Canada Hair Care Market

The Canada hair care market requires brands to keep pace with fast-changing consumer preferences for clean, sulfate-free, and scalp-focused formulations. Brands must also build trust through education and credible, dermatologist-endorsed claims, and compete for shelf space as retailers and online stores expand their offerings of green beauty brands.

The market offers considerable growth opportunities driven by the mainstream acceptance of premium natural hair care, the rise of problem-specific and preventative scalp care, and the skinification of hair care. Innovation in product formulations, digital marketing, and wider online and specialty retail distribution are also expected to support long-term growth.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the Canada hair care market, covering market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant. Detailed profiles of all major companies are also included.

Recent Developments in the Canada Hair Care Market

  • June 2025: Estée Lauder officially launched in Amazon.ca’s Premium Beauty store, expanding access to its skincare, makeup, and fragrance offerings for customers across Canada. The brand had debuted on Amazon.com’s Premium Beauty store in Fall 2024.
  • November 2024: Canadian hair care brand DESIGNME, known for its professional-grade vegan formulations, announced its entry into the U.S. market through a retail collaboration with Nordstrom.
  • September 2024: Sephora Canada launched Fenty Hair by Rihanna across its retail locations and online store, the first time all Fenty beauty categories are available together in one destination across North America.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Poultry Market Size to Worth USD 7.1 Billion by 2034

Mexico Poultry Market Size to Worth USD 7.1 Billion by 2034

IMARC Group has recently released a new research study titled “Mexico Poultry Market Size, Share, Trends and Forecast by Product Type, Nature, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Poultry Market Size & Share 2026-2034

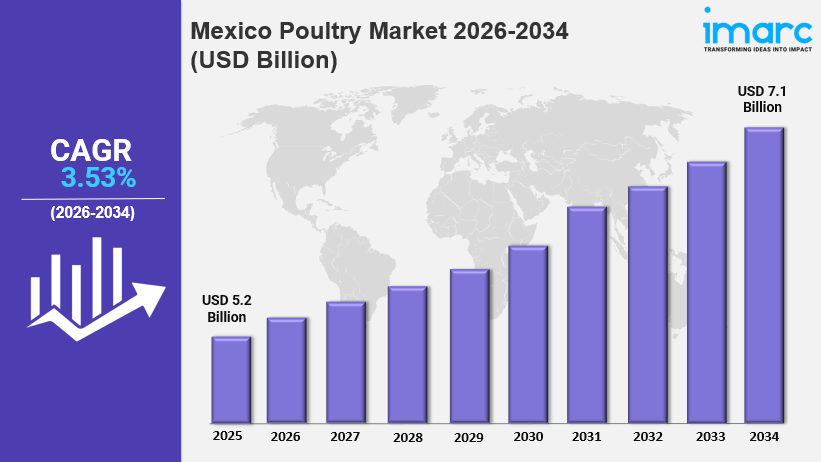
The Mexico poultry market size reached USD 5.2 Billion in 2025 and is projected to reach USD 7.1 Billion by 2034, expanding at a CAGR of 3.53% during 2026-2034. In 2026, the market continues to gain momentum, propelled by increasing consumer demand for affordable protein, rising health consciousness, advancements in poultry farming technologies, growing exports, and government support aimed at enhancing production efficiency and sustainability.

Growth in 2026 is further reinforced by rising domestic production, improved operational efficiency, and increasing private-sector investment in infrastructure and production capacity. These factors are expected to strengthen Mexico poultry market demand and support the Mexico poultry market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 5.2 Billion
  • Projected Market Size (2034): USD 7.1 Billion
  • Growth Rate: CAGR of 3.53% (2026-2034)

Explore Opportunities in the Mexico Poultry Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-poultry-market/requestsample

Key Growth Drivers and Trends in the Mexico Poultry Market

Growth in the Mexico poultry market is being driven by the expansion of domestic poultry production. In 2023, chicken meat production reached 3.89 million metric tons, an increase of 3% from the previous year, and is projected to climb by another 2% in 2025 to 4.1 million metric tons. Improved biosecurity protocols and animal husbandry techniques have led to higher survival rates and reduced mortality, while private sector investments are enhancing infrastructure and production capacity. Stable and relatively low feed prices have also enabled producers to scale operations cost-effectively, and Mexico now ranks as the world’s sixth-largest chicken meat producer.

One of the leading Mexico poultry market trends is increased poultry consumption. Chicken remains the most economical protein option, and population growth, higher disposable incomes, and rising demand from the hotel, restaurant, and institutional (HRI) sectors are boosting consumption levels. Whole chickens account for the majority of poultry sales, as many consumers perceive whole birds as offering better value and freshness compared to processed alternatives.

Another key factor supporting Mexico poultry market growth is the central role poultry plays in the Mexican diet and in national food security. Rising health consciousness, growing exports, and government initiatives to improve production efficiency and sustainability are further strengthening the country’s position as a leading regional supplier and a strategic player in the global poultry market.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=35289&flag=C

Mexico Poultry Industry Segmentation Insights

Breakup by Product Type:

  • Broiler: Represents chicken meat, the most economical protein option, with whole chickens accounting for the majority of poultry sales.
  • Eggs: Benefits from poultry’s central role in the Mexican diet and affordable protein demand.
  • Others: Covers additional poultry products beyond broiler and eggs.

Breakup by Nature:

  • Organic: Appeals to health-conscious consumers seeking poultry produced under organic standards.
  • Conventional: Represents the mainstream segment, supported by affordability and large-scale, efficient production.

Breakup by Distribution Channel:

  • On-Trade: Supported by rising demand from the hotel, restaurant, and institutional (HRI) sectors.
  • Off-Trade: Covers retail sales to households, where consumers value whole chickens for their perceived freshness and value.

Breakup by Region:

  • Northern Mexico: One of the major regional markets analyzed in the report.
  • Central Mexico: One of the major regional markets analyzed in the report.
  • Southern Mexico: Home to expanding production capacity, including Pilgrim’s Mexico’s planned hatchery and feed mill in Merida, Yucatan.
  • Others: Covers the remaining regions analyzed in the report.

Key Challenges and Growth Opportunities in the Mexico Poultry Market

The Mexico poultry market depends on stable feed prices and strong biosecurity to sustain production efficiency, and producers must keep investing in infrastructure, logistics, and supply chain capabilities to meet growing demand across the country and export markets.

Despite these challenges, the market offers considerable growth opportunities driven by affordable protein demand, rising HRI consumption, growing exports, and supportive government initiatives. Investments in new production capacity and supply chain optimization, such as Pilgrim’s Mexico’s planned hatchery and feed mill in February 2024 and Bachoco’s January 2024 logistics partnership with Optilogic, are expected to create substantial opportunities for long-term growth in the Mexico poultry market.

Competitive Landscape

The Mexico poultry market is competitive, with leading producers such as Pilgrim’s Mexico and Bachoco focusing on capacity expansion, operational efficiency, and supply chain optimization to strengthen their market position. The IMARC report covers market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Luxury Cosmetics Market Size to Reach USD  895.62 Million by 2034 | CAGR 3.05% Growth Outlook

Mexico Luxury Cosmetics Market Size to Reach USD 895.62 Million by 2034 | CAGR 3.05% Growth Outlook

IMARC Group has recently released a report titled “Mexico Luxury Cosmetics Market Report by Product Type (Skincare, Haircare, Makeup, and Fragrances), Type (Organic and Conventional), Distribution Channel (Supermarkets and Hypermarkets, Specialty and Monobrand Stores, Online Stores, and Others), End User (Male and Female), and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

Mexico Luxury Cosmetics Market Size and Forecast 2026–2034

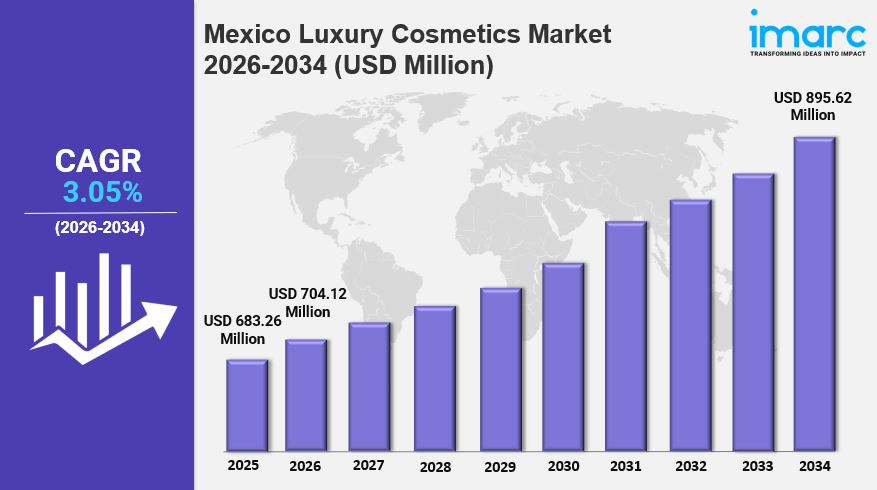
The Mexico luxury cosmetics market size increased from USD 683.26 Million in 2025 to USD 704.12 Million in 2026 and is projected to reach USD 895.62 Million by 2034, exhibiting a CAGR of 3.05% during 2026–2034. Rising disposable incomes among affluent Mexican consumers, increasing demand for premium skincare formulations, and a growing preference for sustainable and clean beauty products are the primary drivers of expansion.

In 2026, the Mexico luxury cosmetics market growth is being supported by the rapid expansion of e-commerce platforms, influencer-led marketing, and the spread of specialty retail formats that offer personalized, high-quality formulations and exclusive brand experiences. Based on the stated CAGR, the market is expected to reach approximately USD 794.0 Million by 2030, with the forecast to 2034 reinforced by continued premiumization, rising penetration of international luxury brands, and the maturing of domestic premium brands.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 683.26 Million
  • Market Size (2026): USD 704.12 Million
  • Projected Size (2034): USD 895.62 Million
  • Growth Rate: CAGR of 3.05%
  • Segments Covered: Product Type, Type, Distribution Channel, End User, and Region

Explore Opportunities in the Mexico Luxury Cosmetics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-luxury-cosmetics-market/requestsample

Mexico Luxury Cosmetics Market Growth: Key Trends and Market Insights

The Mexico luxury cosmetics market growth is supported by the expanding affluent and upper-middle-class population, increasing urbanization, and the strong cultural emphasis on personal appearance and grooming. Social media and digital content creators have raised awareness of scientifically advanced formulations and exclusive brand offerings, while flagship stores and premium department store beauty counters have widened access to international luxury brands. In August 2025, Ulta Beauty opened its first stores in Mexico at Antara Fashion Hall and Galerías Metepec, offering 35 global and local brands.

Key Mexico luxury cosmetics market trends include the rising demand for sustainable and clean beauty formulations. Consumers, especially millennials and Generation Z, are seeking eco-friendly packaging, cruelty-free formulas, and naturally derived ingredients, prompting brands to launch refillable compacts, biodegradable packaging, and vegan skincare, often using traditional ingredients such as nopal, avocado oil, and vanilla. In February 2025, Aora MÉXICO partnered with rePurpose Global to become the first luxury beauty brand in Mexico certified Plastic Negative. Another key trend is the digital transformation of retail, with augmented reality (AR) try-on tools, AI-powered skincare consultations, social commerce, and click-and-collect services reshaping how consumers discover and buy luxury products.

The Mexico luxury cosmetics market growth is also being supported by the premiumization of skincare through science-backed innovation. Affluent consumers increasingly favor dermatology-backed, clinically proven formulations, including advanced anti-aging treatments and brightening serums, and dermocosmetic brands that pair pharmaceutical-grade actives with luxury positioning are gaining traction. In October 2025, Estée Lauder launched its products on Amazon Premium Beauty in Mexico, expanding nationwide access to prestige skincare, makeup, and fragrance.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=31763&flag=C

Mexico Luxury Cosmetics Market Segmentation Analysis

The Mexico luxury cosmetics market is segmented by product type, type, distribution channel, end user, and region, offering a comprehensive view of consumer preferences and regional dynamics across the country, with forecasts for 2026–2034.

Breakup by Product Type

  • Skincare: The leading segment, with a 37.82% share in 2025, driven by growing skin health awareness, anti-aging concerns, demand for dermatology-backed products, and social media–influenced multi-step routines, along with rising demand for sun protection and anti-pollution solutions.
  • Haircare: Premium shampoos, treatments, and styling products, supported by consumer interest in salon-quality and ingredient-led hair health solutions.
  • Makeup: Prestige color cosmetics that benefit from new brand launches, celebrity endorsements, and superior wear characteristics.
  • Fragrances: Luxury perfumes and scents supported by gifting occasions, exclusive launches, and growing domestic fragrance brands.

Breakup by Type

  • Organic: Natural and clean formulations that appeal to sustainability-minded consumers and are gaining ground as an emerging alternative to conventional products.
  • Conventional: The leading segment, with a 70.65% share in 2025, supported by established brand heritage, proven efficacy, extensive distribution networks, and strong consumer trust. In November 2025, The Estée Lauder Companies made a strategic minority investment in Mexican luxury fragrance brand XINÚ.

Breakup by Distribution Channel

  • Supermarkets and Hypermarkets: Mass retail formats offering convenient access to selected premium beauty ranges.
  • Specialty and Monobrand Stores: The largest channel, with a 46.51% share in 2025, driven by curated assortments, personalized service, expert consultations, and exclusive in-store experiences preferred by luxury consumers.
  • Online Stores: A fast-evolving channel boosted by e-commerce platforms, AR try-on tools, exclusive online launches, and social commerce.
  • Others: Remaining distribution channels, including department store counters and travel retail.

Breakup by End User

  • Male: A smaller but developing segment, as grooming and skincare awareness rises among men.
  • Female: The dominant segment, with an 88.9% share in 2025, owing to higher beauty consciousness, extensive skincare and makeup routines, social media influence, and cultural emphasis on personal grooming.

Breakup by Region

  • Northern Mexico: Characterized by higher income levels and strong urbanization in cities such as Monterrey and Tijuana, with demand shaped by cross-border shopping and exposure to United States beauty trends.
  • Central Mexico: Anchored by Mexico City, it holds the largest consumer base and highest concentration of purchasing power, with flagship stores, luxury department counters, and specialty boutiques.
  • Southern Mexico: An emerging opportunity where awareness and purchasing power are gradually rising, with digital channels increasing exposure to national beauty trends.
  • Others: Including the Pacific Coast, Bajío, and Yucatan Peninsula, where secondary cities such as Querétaro, Guadalajara, and Mérida are seeing rising luxury cosmetics penetration.

Key Challenges and Growth Opportunities in the Mexico Luxury Cosmetics Market

The Mexico luxury cosmetics market faces several challenges that could affect its growth, including price sensitivity among broader consumer groups, economic uncertainty and inflationary pressures, the spread of counterfeit and gray market products, and complex cosmetics registration, labeling, and safety regulations that raise entry barriers for newer brands.

Despite these challenges, the market offers significant growth opportunities in e-commerce and omnichannel capabilities, sustainable product development, and personalized customer experiences. Companies that expand premium retail presence, strengthen brand authentication, and invest in science-backed, clean beauty innovation will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The Mexico luxury cosmetics market is moderately consolidated, with established multinational beauty corporations competing alongside premium regional players and emerging domestic brands. Leading companies rely on extensive distribution networks, substantial marketing investments, continuous product innovation, and strong brand heritage. The report provides a comprehensive analysis of the competitive landscape, along with detailed profiles of all major companies operating in the space.

Competitive intensity continues to rise as brands invest in digital transformation, influencer partnerships, and experiential retail, and differentiate through sustainability, natural ingredients, or dermatological expertise. In May 2025, Charlotte Tilbury entered the Mexican market, launching its makeup, skincare, and fragrance range at Sephora Mexico, with counters planned at two El Palacio de Hierro stores and a travel retail concession at Mexico City Airport.

Latest News and Developments

  • December 2025: Clinique launched its products in the Amazon.com.mx Premium Beauty store, expanding nationwide access to dermatologist-guided, allergy-tested, and fragrance-free skincare and makeup.
  • November 2025: The Estée Lauder Companies made a strategic minority investment in Mexican luxury fragrance brand XINÚ, its first investment in Latin America.
  • October 2025: Estée Lauder launched its products on Amazon Premium Beauty in Mexico, widening access to prestige skincare, makeup, and fragrance in urban and remote regions.
  • August 2025: Ulta Beauty opened its first stores in Mexico at Antara Fashion Hall and Galerías Metepec, offering 35 global and local brands.
  • May 2025: Charlotte Tilbury entered the Mexico luxury cosmetics market through Sephora Mexico, with planned counters at El Palacio de Hierro and Mexico City Airport.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Fintech Market Size, Demands, Growth Analysis, Industry Report 2026-2034

United States Fintech Market Size, Demands, Growth Analysis, Industry Report 2026-2034

IMARC Group has recently released a report titled “United States Fintech Market Size, Share, Trends and Forecast by Deployment Mode, Technology, Application, End User, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Fintech Market Size and Forecast 2026–2034

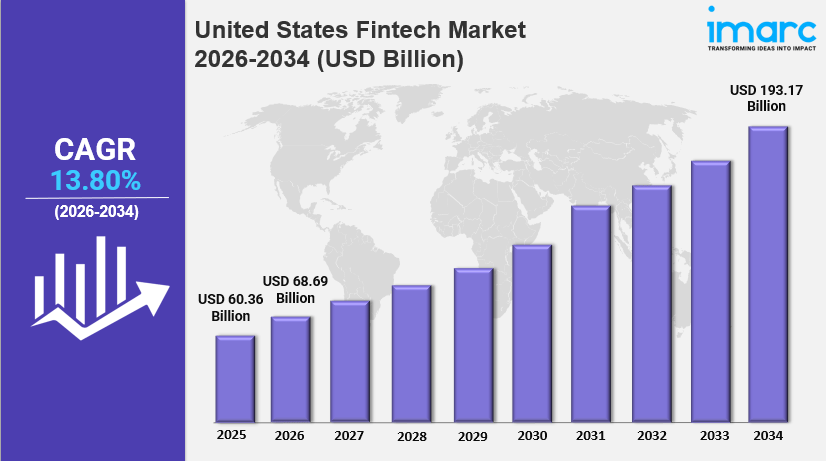
The United States fintech market grew from USD 60.36 Billion in 2025 to USD 68.69 Billion in 2026 and is projected to reach USD 193.17 Billion by 2034, growing at a CAGR of 13.80% during 2026-2034. Accelerating adoption of artificial intelligence and generative AI across financial services, combined with rising digital payment volumes and embedded finance, continues to drive market expansion. Cloud-based deployment dominates the deployment mode segment at 64.8% share, banking leads the end user segment at 42.5%, and the West region leads regionally at 31.7% in 2025.

In 2026, the United States fintech market is estimated at USD 68.69 Billion, with growth being fueled by the expansion of open banking API ecosystems and deeper bank-fintech collaboration, rapid consumer migration toward digital wallets and cashless payment methods with 91% of Gen Z consumers adopting digital wallets, and growing cloud-first fintech deployment across banking, insurance, and securities. The launch of dedicated fintech banking divisions and expanded startup ecosystems is further strengthening access to funding, partnerships, and banking infrastructure, accelerating the commercialization of innovative financial solutions.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 60.36 Billion
  • Market Size (2026): USD 68.69 Billion
  • Projected Size (2034): USD 193.17 Billion
  • Growth Rate: CAGR of 13.80%

Explore Opportunities in the United States Fintech Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-fintech-market/requestsample

United States Fintech Market Growth: Key Trends and Market Insights

The United States fintech market growth is supported by the expansion of startup-focused ecosystems and stronger collaboration between fintech companies, banks, investors, and technology providers. In August 2026, Money20/20 announced an expanded Startup Hub at Money20/20 USA, giving fintech startups greater access to investors, banks, technology firms, enterprise partners, and media. In June 2026, Capital Community Bank (CCBank) launched Quill Bank, a dedicated fintech banking division positioned as a banking backbone for fintech partners, reflecting the broader shift among traditional banks toward specialized units that combine regulatory expertise with fintech-focused services.

Key United States fintech market trends include embedded finance and banking-as-a-service expansion, as financial services such as checking accounts, debit cards, lending, and insurance are integrated directly into e-commerce, mobility, healthcare, and software platforms through fintech API infrastructure. Digital payment adoption is also accelerating, with nearly 90% of US consumers now using contactless payments and 41% of Gen Z digital wallet users transacting more than five times per month, encouraging payment providers and banks to improve digital payment infrastructure and deliver more seamless, personalized financial services.

The United States fintech market growth is also being supported by AI and generative AI advancement, with large language models deployed across customer service, credit underwriting, fraud detection, regulatory document analysis, and personalized financial advice. Bank of America’s Erica AI assistant surpassed 1.5 billion client interactions as of July 2023, illustrating the scale of AI-driven engagement. Meanwhile, growing regulatory clarity around cryptocurrency, stablecoins, and blockchain is enabling new applications in securities settlement, cross-border payments, and tokenized asset management. Companies are investing in AI capabilities, open banking integrations, and cloud-native platforms to improve market reach through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=10452&flag=C

United States Fintech Market Segmentation Analysis

The United States fintech market is segmented by deployment mode, technology, application, end user, and region, offering a comprehensive view of technology adoption, financial service use cases, and regional dynamics across the country.

Breakup by Deployment Mode

  • Cloud-based: Dominates the market with a 64.8% share in 2025, reflecting the shift toward SaaS, PaaS, and IaaS-based financial platforms that deliver superior scalability, faster product iteration, and elastic cost structures, with cloud-based fintech growing at a CAGR of approximately 15.2% through 2034.
  • On-premises: Retains a 35.2% share in 2025, primarily among systemically important financial institutions with legacy core banking systems, high-frequency trading firms with strict latency requirements, and institutions with specific regulatory examination access needs.

Breakup by Technology

  • Application Programming Interface (API): Enables secure, consent-based data sharing and seamless integration between banks and fintech providers, underpinning open banking and embedded finance.
  • Artificial Intelligence: Powers real-time fraud detection, AI-driven credit underwriting, personalized product recommendations, and generative AI customer service automation.
  • Blockchain: Supports secure, transparent recording of financial transactions, enabling digital payments, cross-border transfers, asset tokenization, and smart contracts.
  • Robotic Process Automation: Automates repetitive back-office, compliance, and operational workflows, improving efficiency across financial institutions.
  • Data Analytics: Supports risk decisioning, personalization, and customer retention through insights drawn from transaction and behavioral data.
  • Others: Includes additional enabling technologies supporting diverse fintech applications.

Breakup by Application

  • Payment and Fund Transfer: Benefits from contactless payments, peer-to-peer transfer platforms, real-time payments, and embedded payment integration across e-commerce and retail platforms.
  • Loans: Driven by digital lending marketplaces and AI-powered credit decisioning that expands access to credit for underserved consumers.
  • Insurance and Personal Finance: Supported by insurtech adoption, AI-powered underwriting, digital claims processing, and personal finance management tools.
  • Wealth Management: Expands through robo-advisory platforms, commission-free retail investing, and personalized wealth advisory at scale.
  • Others: Includes additional applications such as regulatory technology, mortgage technology, and digital asset services.

Breakup by End User

  • Banking: Leads with a 42.5% share in 2025, driven by the digital transformation of retail banking, commercial lending, corporate treasury management, and neobanking, with growth at a CAGR of approximately 13.4%.
  • Insurance: Holds a 24.8% share in 2025, reflecting rapid insurtech adoption across property and casualty, health, life, and specialty lines through AI-powered underwriting and embedded insurance distribution.
  • Securities: Accounts for an 18.6% share in 2025 and is the fastest-growing end user at a CAGR of approximately 15.8%, supported by AI-driven trading, robo-advisory platforms, and blockchain-based settlement.
  • Others: Holds a 14.1% share in 2025, encompassing payments, cryptocurrency exchanges, mortgage technology, and proptech-adjacent financial services.

Breakup by Region

  • West: Leads with a 31.7% share in 2025, benefiting from a mature technology ecosystem, strong venture capital availability, and a large concentration of fintech startups and skilled technology talent, anchored by Silicon Valley and the Bay Area.
  • Northeast: Holds a 27.4% share in 2025, supported by an established financial services sector, strong banking presence, and growing collaboration between traditional financial institutions and fintech companies, particularly in New York City.
  • South: Accounts for a 24.6% share in 2025 and is emerging as a fast-growing fintech hub, supported by business-friendly environments, lower operating costs, and expanding technology ecosystems in cities such as Austin and Atlanta.
  • Midwest: Holds a 16.3% share in 2025, benefiting from an established banking network, comparatively affordable talent, and increasing digital banking adoption among regional financial institutions, with Chicago anchoring derivatives fintech and B2B banking technology.

Key Challenges and Growth Opportunities in the United States Fintech Market

The United States fintech market faces several challenges that could affect its growth, including complex multi-regulator compliance across consumer protection, banking supervision, securities regulation, and state money transmitter licensing that can consume 20–30% of fintech startup operational budgets, increasing cybersecurity threats including ransomware, account takeover fraud, and API attacks targeting platforms that process large volumes of sensitive financial data, intense competition for engineering and compliance talent that raises workforce costs, and venture capital normalization that makes funding harder for early-stage firms as capital concentrates among established players.

Despite these challenges, the market offers significant growth opportunities driven by generative AI applications and RegTech automation, including AI-powered compliance document generation, intelligent contract review, and personalized banking advisor chatbots. Financial inclusion represents another major opportunity, with 22% of US adults earning less than $25,000 annually unbanked, compared with just 1% of adults earning $100,000 or more, creating a sizable addressable market for mobile-first neobanks, earned wage access platforms, and credit-builder products. Companies investing in AI capabilities, open banking infrastructure, and embedded finance will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The United States fintech market features a multi-tier competitive structure encompassing global payment giants, consumer fintech platforms, financial infrastructure providers, vertical specialists, and emerging AI-native fintech companies. Key players include Stripe, LLC, PayPal, Block, Inc., Chime Financial, Inc., and Robinhood. The market is moderately fragmented at the company level but highly concentrated within specific product categories, with Stripe and PayPal collectively dominating online merchant payment processing infrastructure.

Competition centers on product innovation velocity, AI capability depth, regulatory compliance expertise, partnership network breadth, and customer acquisition economics. Companies deploying proprietary LLM-based financial analysis tools, AI-powered underwriting, and generative AI customer experience platforms are establishing durable advantages, while strategic M&A is consolidating capabilities around payments-banking, lending-deposits, and investment-insurance bundles in the evolving United States fintech market.

Latest News and Developments

  • August 2026: Money20/20 announced an expanded Startup Hub at Money20/20 USA, providing fintech startups with greater access to investors, banks, technology firms, enterprise partners, and media through founder showcases, curated networking, industry events, and partnership opportunities.
  • June 2026: US-based Capital Community Bank (CCBank) launched Quill Bank, a dedicated fintech banking division designed to serve as a banking backbone for fintech partners by leveraging CCBank’s regulatory, operational, and relationship-banking expertise.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Cybersecurity Market Size, Growth, Latest Trends and Forecast 2026-2034

United States Cybersecurity Market Size, Growth, Latest Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “United States Cybersecurity Market Report by Component (Solutions, Services), Deployment Type (Cloud Based, On-Premises), User Type (Large Enterprises, Small and Medium Enterprises), Industry Vertical (IT and Telecom, Retail, BFSI, Healthcare, Defense/Government, Manufacturing, Energy, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Cybersecurity Market Size & Share 2026-2034

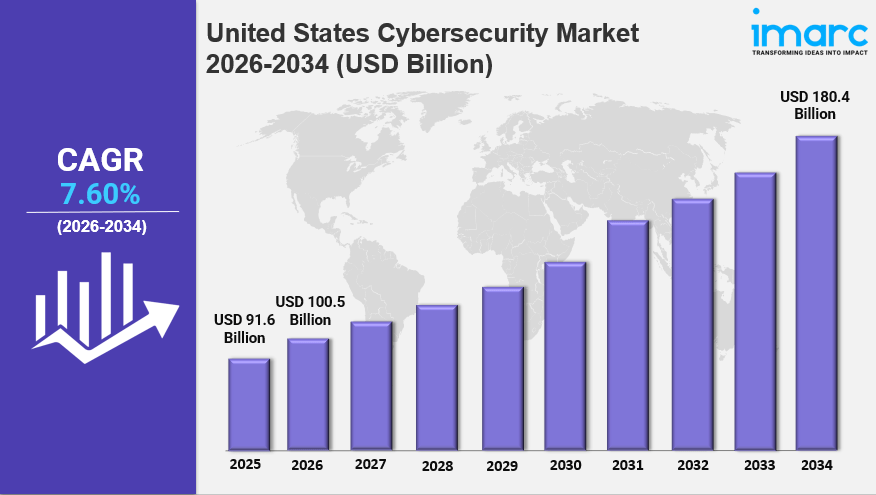
The United States cybersecurity market size increased from USD 91.6 Billion in 2025 to USD 100.5 Billion in 2026 and is projected to reach USD 180.4 Billion by 2034, expanding at a CAGR of 7.60% during 2026-2034. In 2026, the market continues to gain momentum, driven by increasing cyber threats, ongoing digital transformation, strict data protection and privacy regulations, a growing cyber insurance market, and an increasing remote workforce.

The market is segmented by component (solutions and services), deployment type (cloud-based and on-premises), user type (large enterprises and small and medium enterprises), industry vertical, and region (Northeast, Midwest, South, and West). Technological advancements and the need for stronger protection across industries are expected to strengthen the United States cybersecurity market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 91.6 Billion
  • Market Size (2026): USD 100.5 Billion
  • Projected Market Size (2034): USD 180.4 Billion
  • Growth Rate: CAGR of 7.60% (2026-2034)

Explore Opportunities in the United States Cybersecurity Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-cybersecurity-market/requestsample

Key Growth Drivers and Trends in the United States Cybersecurity Market

Growth in the United States cybersecurity market is being driven primarily by the rising sophistication of cyberattacks and ransomware threats. Growing use of cloud services, remote work, and a widening Internet of Things (IoT) ecosystem has expanded the attack surface, while rising regulatory compliance demands are pushing organizations in every industry vertical to invest in advanced security solutions.

One of the leading United States cybersecurity market trends is the adoption of AI-powered security. AI and machine learning tools analyze large volumes of data in real time to detect anomalies, automate incident response, reduce false alarms, and help security teams focus on high-priority attacks. Zero-trust architectures, built on continuous verification, micro-segmentation, multi-factor authentication, and least-privilege access, are also becoming mainstream for hybrid cloud and remote environments.

Another key factor supporting United States cybersecurity market growth is the rise of cybersecurity-as-a-service. Managed security services, security consulting, threat intelligence, and cloud security give organizations, especially small and medium-sized businesses, enterprise-class protection without large capital outlays, and the ongoing shortage of cybersecurity professionals is increasing demand for managed services.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=9660&flag=C

United States Cybersecurity Industry Segmentation Insights

Breakup by Component:

  • Solutions: Includes identity and access management (IAM), infrastructure security, governance, risk and compliance, unified vulnerability management, data security and privacy, and other solutions.
  • Services: Includes professional services and managed services.

Breakup by Deployment Type:

  • Cloud Based: Security delivered through cloud environments, aligned with rising cloud adoption and hybrid IT.
  • On-Premises: Security deployed within an organization’s own infrastructure.

Breakup by User Type:

  • Large Enterprises: Large organizations with complex, hybrid IT environments and extensive compliance needs.
  • Small and Medium Enterprises: Smaller businesses that benefit from cybersecurity-as-a-service and managed offerings.

Breakup by Industry Vertical

  • IT and Telecom: Protects digital infrastructure, networks, customer information, and communication systems against evolving cyber threats.
  • Retail: Secures online transactions, payment systems, customer data, and digital commerce platforms against fraud and data breaches.
  • BFSI: Safeguards financial transactions, banking platforms, confidential customer records, and digital payment systems from cyberattacks.
  • Healthcare: Protects electronic health records, medical devices, patient information, and connected healthcare systems from unauthorized access.
  • Defense/Government: Secures critical government networks, confidential information, defense systems, and essential public services against cyber threats.
  • Manufacturing: Protects industrial control systems, connected machinery, production networks, and intellectual property from cyberattacks.
  • Energy: Secures power grids, energy infrastructure, operational technology, and critical systems against disruptions and malicious attacks.
  • Others: Includes education, transportation, hospitality, and other sectors requiring data protection and cybersecurity risk management.

Breakup by Region

  • Northeast: Demand is supported by financial services, healthcare institutions, government organizations, and technology companies requiring advanced security solutions.
  • Midwest: Manufacturing, automotive, and industrial businesses drive cybersecurity adoption to protect operational systems and sensitive business data.
  • South: Expanding technology, healthcare, energy, and defense sectors increase demand for reliable cybersecurity infrastructure and threat prevention.
  • West: Technology firms, cloud service providers, and digital businesses support demand for advanced cybersecurity, data protection, and network security solutions.

Key Challenges and Growth Opportunities in the United States Cybersecurity Market

The United States cybersecurity market faces challenges including the ongoing skills shortage, the growing complexity of hybrid IT environments, balancing security controls with operational efficiency, managing the cost of end-to-end security solutions, and keeping pace with a fast-evolving threat landscape.

Despite these challenges, the market offers considerable growth opportunities, including integration of AI and machine learning in security products, growth in managed security services, industry-specific cybersecurity models, rising demand for privacy-oriented technology, and the emergence of quantum-resistant cryptography.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the United States cybersecurity market, including market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant. Detailed profiles of all major companies are also provided. Recent activity shows consolidation, with ongoing mergers and acquisitions in cloud-native, AI-driven identity, and fraud prevention technologies.

Recent Developments in the United States Cybersecurity Market

  • September 2025: 27 cybersecurity M&A deals were announced, a slowdown from earlier months. Key transactions included Accenture acquiring CyberCX for over USD 650 million, CrowdStrike buying Onum for USD 290 million, and Diginex acquiring Findings for USD 305 million, along with F5’s purchase of MantisNet and Incode’s acquisition of AuthenticID.
  • July 2025: Rising cybercrime drove a surge in U.S. cybersecurity M&A as businesses faced escalating threats, regulatory pressure, and financial liabilities. Incidents such as the Change Healthcare breach and attacks on AT&T, Verizon, and Lumen highlighted sector vulnerabilities, while IoT malware and AI-driven phishing increased attack complexity.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Generator Sales Market Size is Expected to Reach USD 9.02 Billion by 2034 | CAGR 4.55%

United States Generator Sales Market Size is Expected to Reach USD 9.02 Billion by 2034 | CAGR 4.55%

IMARC Group has recently released a new research study titled “United States Generator Sales Market Size, Share, Trends and Forecast by Power Rating, Fuel Type, Application, End Use Industry, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Generator Sales Market Size & Share 2026-2034

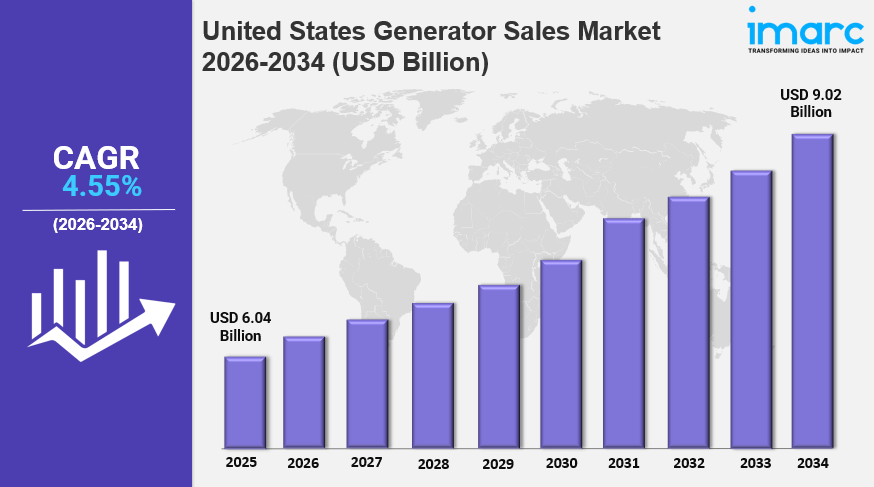
The United States generator sales market size reached USD 6.04 Billion in 2025 and is projected to reach USD 9.02 Billion by 2034, expanding at a CAGR of 4.55% during 2026-2034. In 2026, the market continues to gain momentum, driven by the increasing frequency and severity of power outages caused by extreme weather events, aging grid infrastructure requiring reliable backup solutions, and rapid industrialization across key sectors.

Growth in 2026 is further reinforced by rising electricity demand from data centers, commercial establishments, and industrial facilities, along with technological advancements in generator efficiency and the expansion of the construction sector. These dynamics are expected to strengthen the United States generator sales market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 6.04 Billion
  • Projected Market Size (2034): USD 9.02 Billion
  • Growth Rate: CAGR of 4.55% (2026-2034)
  • Leading Power Rating: Above 750 kVA (34% share in 2025)
  • Leading Fuel Type: Diesel (60% share in 2025)
  • Leading Application: Standby Load (41% share in 2025)
  • Leading End Use Industry: Industrial (39% share in 2025)
  • Leading Region: South (32% share in 2025)

Explore Opportunities in the United States Generator Sales Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-generator-sales-market/requestsample

Key Growth Drivers and Trends in the United States Generator Sales Market

Growth in the United States generator sales market is being driven primarily by the increasing frequency and severity of power outages from extreme weather events such as hurricanes, wildfires, ice storms, and heatwaves. According to reports, the average longest U.S. power outage increased from 8.1 hours in 2022 to 12.8 hours by mid-2025, compelling residential, commercial, and industrial users to invest in reliable backup power.

One of the leading United States generator sales market trends is the aging electrical grid, with substantial portions of transmission lines and transformers approaching or exceeding their intended operational lifespans. In 2025, Avangrid announced a USD 20 Billion plan to modernize and expand U.S. grid infrastructure through 2030. The rapid expansion of AI-driven data centers is also adding to electricity demand and accelerating the adoption of generators for both primary and backup power. In April 2025, Generac launched five new high-capacity standby generators (2.25 to 3.25 MW) for hyperscale, colocation, enterprise, and edge data centers, and in January 2026 it acquired a new facility in Sussex, Wisconsin, to expand manufacturing of commercial and industrial generators.

Another key factor supporting United States generator sales market growth is the integration of smart technologies and the rise of hybrid systems. Modern generators increasingly feature IoT-enabled sensors and connectivity for real-time monitoring, remote diagnostics, and predictive maintenance, as seen in Generac’s Mobile Link app for home standby generators. Hybrid generator systems that combine conventional fuel with renewable energy and battery storage are also gaining traction; Aggreko’s natural gas battery system in the Permian Basin reduced generator running times from 167 to 6 hours and lowered fuel expenses by as much as 96%.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21137&flag=C

United States Generator Sales Industry Segmentation Insights

Breakup by Power Rating:

  • Below 75 kVA: Smaller generators used for residential, small commercial, and portable applications.
  • 75-375 kVA: Mid-range generators used for commercial buildings and light industrial applications.
  • 375-750 kVA: Higher-capacity generators used for larger commercial and industrial facilities.
  • Above 750 kVA: The leading segment with a 34% share in 2025, driven by heavy industrial applications, large-scale manufacturing facilities, and hyperscale data centers requiring megawatt-level backup power.

Breakup by Fuel Type:

  • Diesel: The leading segment with a 60% share in 2025, owing to its reliability, high power density, wide availability, and proven performance in critical applications across industrial and commercial sectors.
  • Gas: Natural gas and other gas-fueled generators, including mobile units suited to oil, gas, and remote applications.
  • Others: Includes other fuel types and hybrid configurations.

Breakup by Application:

  • Continuous Load: Generators that supply continuous primary power to facilities and sites.
  • Peak Load: Generators used to meet peak demand and supplement grid supply.
  • Standby Load: The leading segment with a 41% share in 2025, driven by emergency power supply needs in healthcare organizations, data centers, and telecom operations.

Breakup by End Use Industry:

  • Industrial: The leading segment with a 39% share in 2025, covering utilities/power generation, oil and gas, chemicals and petrochemicals, mining and metals, manufacturing, marine, construction, and others.
  • Commercial: Covers IT and telecom, healthcare, data centers, and others, where uninterrupted power is critical to operations.
  • Residential: Home standby and portable generators, with growing adoption in regions prone to extended outages.

Breakup by Region:

  • Northeast: One of the major regional markets analyzed in the report.
  • Midwest: One of the major regional markets analyzed in the report.
  • South: The leading region with a 32% share in 2025, supported by hurricane exposure along the Gulf Coast and Atlantic seaboard, a concentrated oil and gas industry, expanding data center investment, and major metropolitan areas such as Houston, Dallas, Atlanta, and Miami.
  • West: One of the major regional markets analyzed in the report.

Key Challenges and Growth Opportunities in the United States Generator Sales Market

The United States generator sales market faces challenges including high initial capital investment and installation costs, stringent environmental regulations and emissions standards, and growing competition from alternative backup power technologies such as battery energy storage systems, fuel cells, and renewable microgrids. Skilled labor shortages for installation and maintenance and varying state-level regulatory requirements also complicate adoption.

Despite these challenges, the market offers considerable growth opportunities in high-capacity generators for data centers, healthcare facilities, and critical infrastructure, as well as in premium offerings built on fuel efficiency, emissions reduction, smart monitoring, and hybrid and renewable-integrated systems. Growing residential adoption in outage-prone regions and rising investment in backup power by commercial and industrial users are also expected to support long-term growth.

Competitive Landscape

The United States generator sales market is moderately consolidated, with established global manufacturers competing alongside regional distributors and specialized solution providers. Players compete on product reliability, technological innovation, fuel efficiency, emissions performance, and comprehensive after-sales service networks, supported by extensive distribution and dealer relationships. Companies such as Generac, Aggreko, Rolls-Royce, GE Vernova, and Baseline Energy Services have recently announced product launches and capacity expansions, and strategic partnerships between generator manufacturers and technology providers are creating differentiated offerings with advanced monitoring and predictive maintenance. The IMARC report examines the competitive landscape along with profiles of the key players.

Recent Developments in the United States Generator Sales Market

  • January 2026: Generac acquired a new facility in Sussex, Wisconsin, to expand manufacturing of commercial and industrial generators, supporting data center growth and backup power capacity.
  • October 2025: Rolls-Royce introduced the 20V4000 mtu gas generator for North American data centers, delivering 2.8 MW full output with a 45-second ramp-up and supporting both primary and backup power.
  • August 2025: Aggreko launched its 400 kW Tier 4 Final diesel generator in North America, offering lower emissions, strict noise compliance, and reduced operating costs for industrial and construction applications. GE Vernova also announced a USD 41 Million investment to expand steam and gas generator assembly and testing capacity at its Schenectady facility.
  • June 2025: Baseline Energy Services introduced the NexGen 400, a 400 kW natural gas mobile generator with smart engine technology, ultra-low emissions, and remote monitoring, scalable up to 15 MW for oil, gas, and remote applications.
  • April 2025: Generac launched five new high-capacity standby generators (2.25 to 3.25 MW) tailored for hyperscale, colocation, enterprise, and edge data centers.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Ready to Drink Coffee Market Size, Industry Trends, Share, Growth and Report 2026-2034

Mexico Ready to Drink Coffee Market Size, Industry Trends, Share, Growth and Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Ready to Drink Coffee Market Size, Share, Trends and Forecast by Packaging, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Ready to Drink Coffee Market Size & Share 2026-2034

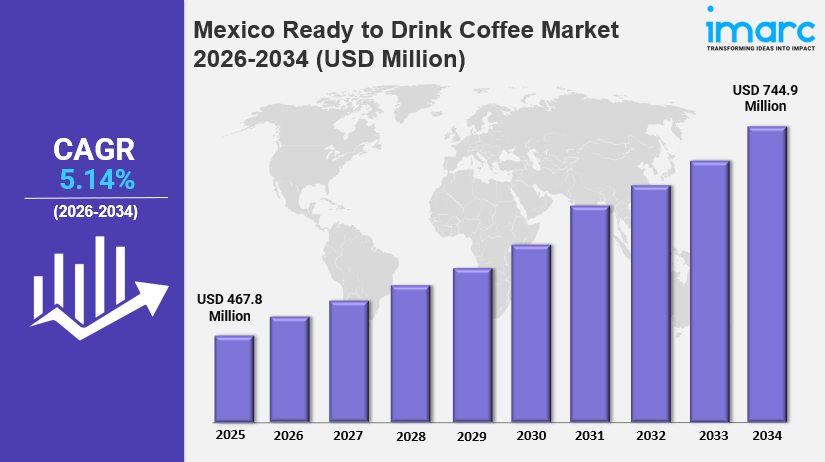
The Mexico ready to drink coffee market size reached USD 467.8 Million in 2025 and is projected to reach USD 744.9 Million by 2034, expanding at a CAGR of 5.14% during 2026-2034. In 2026, the market continues to gain momentum, fueled by a growing working population opting for easy and swift beverage consumption that fits an on-the-go lifestyle, rising spending on specialty and premium drinks, and the increasing influence of coffee culture.

Ready to drink coffee offers consumers their preferred beverage without any preparation, which suits the busy routines of young professionals, students, and daily commuters in urban centers. The growing presence of convenience stores, supermarkets, vending machines, and ready-to-consume facilities at fuel stations is also making these products easier to find. These dynamics are expected to strengthen the Mexico ready to drink coffee market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 467.8 Million
  • Projected Market Size (2034): USD 744.9 Million
  • Growth Rate: CAGR of 5.14% (2026-2034)

Explore Opportunities in the Mexico Ready to Drink Coffee Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-ready-to-drink-coffee-market/requestsample

Key Growth Drivers and Trends in the Mexico Ready to Drink Coffee Market

Growth in the Mexico ready to drink coffee market is being driven primarily by the rise of urban life and convenience culture. As more people move to cities for jobs and education, daily routines have become more hectic, and consumers look for grab-and-go food and beverages. In cities such as Mexico City, Guadalajara, and Monterrey, where traffic and long working hours are common, ready to drink coffee provides a quick, stimulating beverage that does not need to be brewed. According to Mexico’s National Agricultural Planning, national coffee consumption is predicted to rise from 0.80 to 0.94 Million Tons by 2030.

One of the leading Mexico ready to drink coffee market trends is the influence of global coffee culture and premiumization. Mexico’s coffee industry includes over 500,000 producers and more than 75,500 coffee shops, a figure that continues to rise steadily. As international cafe chains spread and social media raises awareness of coffee styles, consumers are looking for higher-quality, specialty-style coffee experiences in convenient formats, prompting companies to offer cold brews, flavored lattes, and plant-based milk alternatives, supported by packaging that communicates quality and style.

Another key factor supporting Mexico ready to drink coffee market growth is the focus on local ingredients and sustainability. Brands increasingly highlight Mexican-grown coffee beans from regions such as Chiapas, Veracruz, and Oaxaca, which, according to SADER, account for 41.3%, 24.4%, and 8.2% of national coffee production, respectively. Companies are also testing traditional flavors such as cinnamon, piloncillo (unrefined cane sugar), and chocolate, while adopting recyclable packaging, reducing plastic use, and encouraging fair trade practices.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=35242&flag=C

Mexico Ready to Drink Coffee Industry Segmentation Insights

Breakup by Packaging:

  • Bottles: Ready to drink coffee sold in bottles, offering portability and a premium presentation suited to cold brews and flavored lattes.
  • Cans: Ready to drink coffee sold in cans, a compact and widely stocked format for on-the-go consumption.
  • Others: Includes other packaging formats used for ready to drink coffee products.

Breakup by Distribution Channel:

  • Supermarkets/Hypermarkets: Large retail formats where consumers can choose from a wide range of ready to drink coffee brands.
  • Convenience Stores: A fast-growing point of purchase for grab-and-go beverages among urban consumers and commuters.
  • Online Retail: E-commerce platforms offering ready to drink coffee products with home delivery.
  • Others: Includes vending machines, fuel stations, and other points of sale.

Breakup by Region:

  • Northern Mexico: Includes major urban centers such as Monterrey, where long working hours support demand for convenient beverages.
  • Central Mexico: Includes Mexico City, one of the country’s largest urban centers, where traffic and busy lifestyles drive demand for on-the-go coffee.
  • Southern Mexico: Includes coffee-producing states such as Chiapas and Oaxaca, supporting the use of locally sourced Mexican coffee.
  • Others: Covers the remaining regions of Mexico, including other producing and consuming areas.

Key Growth Opportunities in the Mexico Ready to Drink Coffee Market

The Mexico ready to drink coffee market offers considerable growth opportunities driven by premiumization, as consumers seek cold brews, flavored lattes, plant-based milk alternatives, and gourmet and artisanal flavor profiles, particularly among young consumers. Ready to drink coffee is evolving from a generic energy drink into a lifestyle product, meeting the changing demands of an expanding middle class and wellness-oriented, trend-savvy consumers.

Local flavors, locally sourced beans, and sustainable packaging also offer scope for differentiation, while state initiatives aimed at boosting coffee production and consumption in the coming years, along with the rising number of convenience stores, supermarkets, and vending points, are expected to support long-term growth.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the Mexico ready to drink coffee market, covering market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of all major companies. Local and global brands are investing in premium products and in packaging that communicates quality and style.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
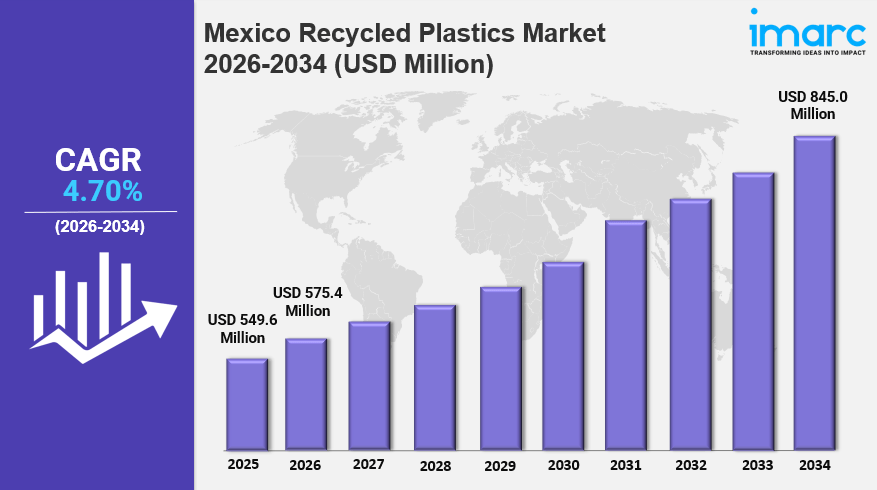
Mexico Recycled Plastics Market Size, Trends, Growth and Forecast 2026-2034

Mexico Recycled Plastics Market Size, Trends, Growth and Forecast 2026-2034

IMARC Group has recently released a new research study titled “Mexico Recycled Plastics Market Size, Share, Trends and Forecast by Plastic Type, Raw Material, Application, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Recycled Plastics Market Size & Share 2026-2034

The Mexico recycled plastics market size increased from USD 549.6 Million in 2025 to USD 575.4 Million in 2026 and is projected to reach USD 845.0 Million by 2034, growing at a CAGR of 4.70% during 2026-2034. The market is driven by rising environmental awareness, single-use plastic restrictions, and expanding construction activity adopting recycled materials. In 2024, Mexico generated around 5.7 Million Tons of mismanaged plastic waste, intensifying recycling efforts.

Plastic bottles dominate raw materials at 44.2%, non-food contact packaging leads applications at 37.8%, and Central Mexico commands 43.5% of national demand. These dynamics are expected to strengthen the Mexico recycled plastics market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 549.6 Million
  • Market Size (2026): USD 575.4 Million
  • Projected Market Size (2034): USD 845.0 Million
  • Growth Rate: CAGR of 4.70% (2026-2034)
  • Dominant Raw Material: Plastic Bottles (44.2%, 2025)
  • Dominant Application: Non-Food Contact Packaging (37.8%, 2025)
  • Leading Region: Central Mexico (43.5%, 2025)

Explore Opportunities in the Mexico Recycled Plastics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-recycled-plastics-market/requestsample

Key Growth Drivers and Trends in the Mexico Recycled Plastics Market

Growth in the Mexico recycled plastics market is driven by rising awareness of plastic pollution, which is pushing businesses and consumers toward recycled materials, supported by corporate sustainability targets and consumer preference for products made with recycled content. State-level single-use plastic bans and recycling programs encourage recycled content, while beverage and consumer-goods brand owners are committing to recycled-content targets, especially in PET, through bottle-to-bottle programs with local recyclers.

The expanding construction sector is another driver, adopting recycled plastics in piping, insulation, panels, and roofing for their lightweight, durable, and moisture-resistant properties. Mexico’s proximity to the United States also supports cross-border recycled resin trade and nearshoring-driven industrial demand for recycled materials.

Key trends include the scale-up of bottle-to-bottle food-grade rPET, the emergence of chemical recycling for hard-to-recycle plastics, extended producer responsibility (EPR) proposals and collection investment, and growing use of recycled content in construction and automotive components.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32982&flag=C

Mexico Recycled Plastics Industry Segmentation Insights

The report categorizes the Mexico recycled plastics market by plastic type, raw material, application, and region, with historical analysis for 2020-2025 and forecasts for 2026-2034.

Breakup by Plastic Type:

  • Polyethylene Terephthalate (PET): Supported by Mexico’s high post-consumer PET recovery rate and food-grade rPET capacity.
  • High Density Polyethylene (HDPE): Used in containers and increasingly in construction and infrastructure as rHDPE.
  • Polypropylene (PP): Used in packaging, construction, and automotive components.
  • Low Density Polyethylene (LDPE): Mainly recovered from film and flexible packaging.
  • Others: Covers the remaining plastic types.

Breakup by Raw Material:

  • Plastic Bottles (44.2%): The leading raw material, reflecting Mexico’s mature PET bottle collection and bottle-to-bottle recycling base; growing at about 4.9% CAGR.
  • Plastic Films (21.7%): Captures flexible packaging recovery from retail, food, and consumer-goods streams, though contamination and multi-layer structures raise processing complexity.
  • Rigid Plastic and Foam (18.5%): Serves containers, crates, and durable goods, supported by HDPE and PP recovery.
  • Fibers (9.4%): Reflects textile and carpet recycling.
  • Others (6.2%): Covers the remaining raw materials.

Breakup by Application:

  • Non-Food Contact Packaging (37.8%): The leading application, using recycled resin in non-food bottles, containers, and films where regulatory thresholds are lower.
  • Food Contact Packaging (26.4%): The fastest-growing application at about 5.4% CAGR as bottle-to-bottle rPET adoption deepens among beverage brand owners.
  • Construction (17.3%): Recycled plastics in piping, panels, insulation, and roofing; growing at about 5.1% CAGR.
  • Automotive (11.2%): Recycled components in interior trim, under-hood, and structural parts as OEMs pursue sustainability targets.
  • Others (7.3%): Covers the remaining applications.

Breakup by Region:

  • Central Mexico (43.5%): The leading region, with a dense concentration of recyclers, packaging converters, and beverage bottlers in the central industrial corridor.
  • Northern Mexico (29.1%): Driven by manufacturing, automotive, and nearshoring activity demanding recycled materials.
  • Southern Mexico (16.2%): Emerging, with growing collection initiatives, packaging demand, and infrastructure development.
  • Others (11.2%): Remaining areas with developing recycling capacity and collection networks.

Key Challenges and Growth Opportunities in the Mexico Recycled Plastics Market

Market restraints include the high cost and limited availability of advanced recycling infrastructure, competition from low-priced virgin plastics (particularly when oil prices are low), and inconsistent feedstock quality and collection gaps caused by low household source-separation rates. Challenges also include low national recycling rates despite strong PET recovery, and regulatory fragmentation, since single-use plastic and recycling rules vary widely across states.

The market offers considerable opportunities in food-grade rPET capacity expansion, chemical recycling for hard-to-recycle plastics, rHDPE in construction and infrastructure, and EPR-driven collection expansion. Food contact packaging (about 5.4% CAGR), construction (about 5.1%), and plastic bottles (about 4.9%) are the highest-growth segments.

Competitive Landscape

The Mexico recycled plastics market is moderately concentrated, led by integrated food-grade rPET producers, large polyester recyclers, and collection-focused specialists serving the beverage and packaging value chain. Competition centers on feedstock access, processing quality, and the ability to meet brand-owner recycled-content specifications. Key players include Alpek, S.A.B. de C.V. and JC PLASTICS, among others. The IMARC report covers market structure, key player positioning, top winning strategies, and detailed company profiles.

  • Alpek, S.A.B. de C.V.: Market leader and the largest producer and recycler of PET in the Americas, with an integrated polyester value chain; key products include rPET flake and pellet and PerPETual recycled PET resin.
  • JC PLASTICS: A 100% Mexican recycling company supplying recycled polypropylene (PP) and high-density polyethylene (HDPE) pellets and flakes to national and international customers.

Key Industry Data Points

  • 2024 Mismanaged Plastic Waste: Mexico generated around 5.7 Million Tons of mismanaged plastic waste in 2024, intensifying recycling efforts.
  • Outlook to 2034: Food-grade rPET is expected to consolidate as the highest-value output category, while chemical recycling reaches early commercial scale for harder-to-recycle streams as EPR frameworks mature.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302