Canada E-Commerce Market Size is Expected to Reach USD 5,353.6 Billion by 2034 | CAGR 25.15%

Canada E-Commerce Market Size is Expected to Reach USD 5,353.6 Billion by 2034 | CAGR 25.15%

IMARC Group has recently released a new research study titled “Canada E-Commerce Market Size, Share, Trends and Forecast by Business Model, Mode of Payment, Service Type, Product Type, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Canada E-Commerce Market Size & Share 2026-2034

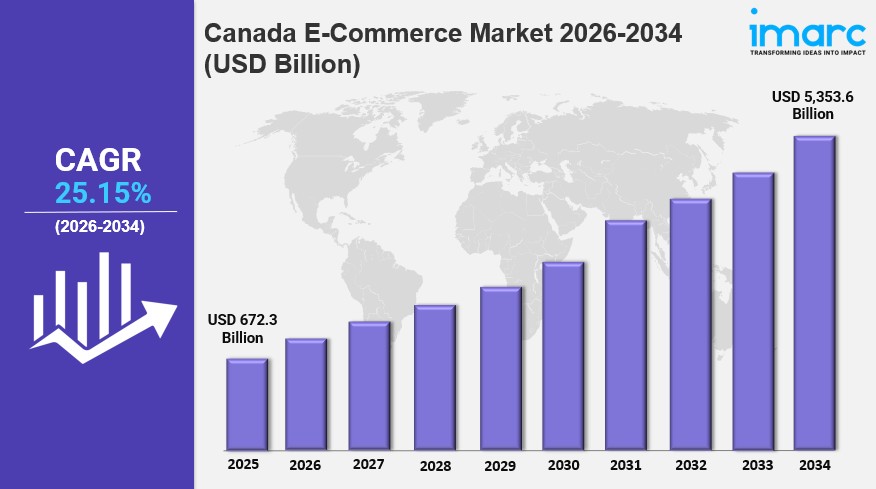
The Canada e-commerce market size reached USD 672.3 Billion in 2025 and is projected to reach USD 5,353.6 Billion by 2034, expanding at a CAGR of 25.15% during 2026-2034. The growth of the e-commerce market is driven by rapid digital adoption, rising mobile commerce penetration, expanding broadband infrastructure, and evolving consumer preference for online retail.

Canada’s high internet penetration rate of 95% in 2025 provides a strong foundation for sustained e-commerce growth, while government digital infrastructure investment and innovation in digital payments further influence the Canada e-commerce market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 672.3 Billion
  • Projected Market Size (2034): USD 5,353.6 Billion
  • Growth Rate: CAGR of 25.15% (2026-2034)

Explore Opportunities in the Canada E-Commerce Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-e-commerce-market/requestsample

Key Growth Drivers and Trends in the Canada E-Commerce Market

Growth in the Canada e-commerce market is being driven by rising internet and mobile penetration, as the country’s internet penetration reached 95% in 2025, providing a vast addressable digital consumer base. Mobile commerce is projected to account for over 50% of all e-commerce transactions in Canada by 2025, with smartphone users reaching 35 million, and platforms investing in mobile-first experiences are capturing higher conversion rates and stronger customer retention.

One of the leading Canada e-commerce market trends is government digital infrastructure investment, as federal and provincial broadband initiatives, including the Universal Broadband Fund targeting USD 2.35 billion in investment, expand internet access in underserved rural and remote communities. Increased connectivity directly expands the e-commerce addressable market, unlocking new consumer segments outside major metropolitan areas such as Toronto, Vancouver, and Montreal.

Another key factor supporting Canada e-commerce market growth is innovation in digital payments, as Canada’s Real-Time Rail (RTR) system under Payments Canada’s modernization program, set to launch in late 2026, will introduce instant account-to-account payment rails. By 2025, digital payments account for approximately 86% of total payment volume, with digital wallets including Apple Pay, Google Pay, and Interac e-Transfer reducing transaction friction and increasing checkout conversion among mobile-native consumers.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=37397&flag=C

Canada E-Commerce Industry Segmentation Insights

Breakup by Business Model:

  • B2C: Leads the market at 68.4% in 2025, driven by marketplace platforms and direct-to-consumer storefronts offering convenience, competitive pricing, and broad product assortments.
  • B2B: Growing rapidly at 21.7% share as enterprise procurement digitalization accelerates online sourcing for office supplies, industrial equipment, and business services.
  • C2C: Holds a 6.3% share, operating through platforms like eBay Canada, Facebook Marketplace, and Kijiji.
  • Others: Includes government e-procurement, nonprofit digital fundraising, and hybrid models, holding a 3.6% share.

Breakup by Mode of Payment:

  • Payment Cards: Represents a widely used payment method supported by strong card issuance and merchant acceptance networks.
  • Online Banking: Supports direct bank-to-merchant transactions favored for security and convenience.
  • E-Wallets: Growing in popularity through digital wallets such as Apple Pay, Google Pay, and Interac e-Transfer.
  • Cash-On-Delivery: Continues to serve consumers preferring payment upon receipt of goods.
  • Others: Includes emerging payment methods such as buy-now-pay-later and digital currencies.

Breakup by Service Type:

  • E-Tailing: Leads the market at 52.6% in 2025 through fashion, electronics, home goods, and grocery categories.
  • Financial: Holds an 18.4% share, including digital banking, insurance, and investment platforms.
  • Travel and Leisure: Represents 14.3% share, benefiting from growing online booking adoption across airlines, hotels, and experience providers.
  • Digital Content: Accounts for 10.2% share and grows at approximately 28.2% CAGR through streaming, gaming, e-learning, and SaaS subscriptions.
  • Others: Includes government services, healthcare telemedicine, and niche digital platforms at 4.5% share.

Breakup by Product Type:

  • Groceries: Represents a growing category supported by expanding online grocery delivery and subscription services.
  • Clothing and Accessories: Benefits from strong fashion e-tailing demand and competitive online discounting.
  • Mobiles and Electronics: Driven by consumer demand for the latest devices and competitive online pricing.
  • Health and Personal Care: Growing steadily through expanding online pharmacy and wellness product offerings.
  • Others: Includes home goods, furniture, and additional product categories sold through online channels.

Breakup by Region:

  • Ontario: Represents the leading regional market at 39.4% in 2025, anchored by dense urban population, high household incomes, and advanced logistics infrastructure.
  • Quebec: Holds a 23.8% share, supported by French-language platform investments, growing mobile commerce, and provincial e-commerce support programs.
  • British Columbia: Represents 15.6% share, driven by tech-forward consumer demographics in Vancouver and expanding cross-border trade with Asia-Pacific markets.
  • Alberta: Holds a 13.4% share, supported by high per-capita income and strong enterprise B2B platform adoption.
  • Others: Includes Saskatchewan, Manitoba, Nova Scotia, New Brunswick, and the Northern Territories, contributing 7.8% share through rural e-commerce and government digital services.

Key Challenges and Growth Opportunities in the Canada E-Commerce Market

The Canada e-commerce market faces challenges including cybersecurity and data privacy concerns under PIPEDA regulations, high last-mile logistics costs in suburban and rural regions, and regulatory complexity such as Quebec’s Bill 96 mandating French-language parity across digital touchpoints.

Despite these challenges, the market offers considerable growth opportunities driven by mobile commerce expansion, AI-driven personalization, cross-border e-commerce growth, and rural broadband rollout. Social commerce integration and same-day and micro-fulfillment expansion are expected to create substantial opportunities for long-term growth in the Canada e-commerce market.

Competitive Landscape

The Canada e-commerce market is moderately concentrated, with the top five players holding approximately 40% combined market share in 2025. Companies including Amazon.com, Inc., Costco Wholesale Corporation, Walmart Inc., The Home Depot, Inc., and Canadian Tire compete on fulfillment speed, platform breadth, payment convenience, AI-powered personalization, and customer loyalty programs, while investing in logistics automation and retail media networks to differentiate their offerings.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Beauty and Personal Care Market Size, Share, Trends, Growth Factors and Forecast 2026-2034

Mexico Beauty and Personal Care Market Size, Share, Trends, Growth Factors and Forecast 2026-2034

IMARC Group has recently released a new research study titled “Mexico Beauty and Personal Care Market Size, Share, Trends and Forecast by Product Type, Category, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Beauty and Personal Care Market Size & Share 2026-2034

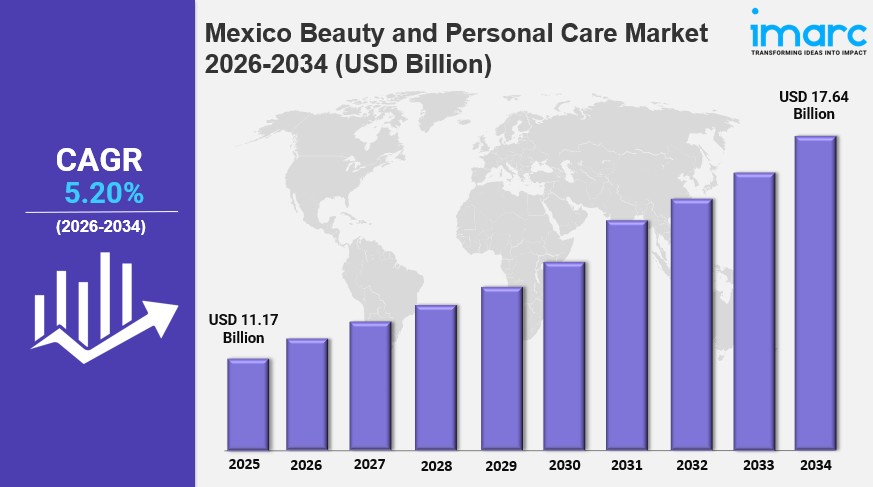
The Mexico beauty and personal care market size was valued at USD 11.17 Billion in 2025 and is projected to reach USD 17.64 Billion by 2034, growing at a CAGR of 5.20% during 2026-2034. The market is propelled by increasing consumer awareness about skincare and personal grooming, a growing middle-class population with higher disposable income, and the influence of social media and beauty influencers.

The cultural emphasis on appearance and wellness, coupled with rapid urbanization, drives demand for both premium and mass-market beauty products. E-commerce expansion and the entry of international brands through strategic partnerships continue to reshape the Mexico beauty and personal care market share, with skin care leading product types at 27%, mass products commanding 74% of the category share, supermarkets/hypermarkets holding 37% of distribution, and Central Mexico representing 41% of regional demand in 2025.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 11.17 Billion
  • Projected Market Size (2034): USD 17.64 Billion
  • Growth Rate: CAGR of 5.20% (2026-2034)
  • Leading Product Type (2025): Skin Care, holding a 27% share
  • Leading Category (2025): Mass, holding a 74% share
  • Leading Distribution Channel (2025): Supermarkets/Hypermarkets, holding a 37% share
  • Leading Region (2025): Central Mexico, holding a 41% share

Explore Opportunities in the Mexico Beauty and Personal Care Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-beauty-personal-care-market/requestsample

Key Growth Drivers and Trends in the Mexico Beauty and Personal Care Market

Growth in the Mexico beauty and personal care market is being driven by rising demand for clean and sustainable beauty products, as Mexican consumers increasingly prioritize natural, organic, and cruelty-free formulations. Environmental consciousness is driving preference for products with recyclable packaging and biodegradable formulas, with brands responding by securing sustainability certifications and launching refill stations in major metropolitan areas. In February 2025, Mexican skincare brand Aora partnered with RePurpose Global to launch a plastic-free skincare initiative, becoming certified as a plastic-negative brand using recyclable materials like tin and wood in its packaging.

One of the leading Mexico beauty and personal care market trends is digital transformation and social commerce growth, as e-commerce platforms and social commerce channels reshape consumer purchasing behaviors. Influencer marketing through Instagram, TikTok, and YouTube significantly impacts product discovery and brand loyalty among millennials and Gen Z consumers, while virtual try-on services and AI-driven skin analysis tools enhance online shopping experiences. The February 2025 launch of TikTok Shop in Mexico has enabled beauty brands to achieve double-digit sales increases through promotional livestreams and user-generated content strategies.

Another key factor supporting Mexico beauty and personal care market growth is the expansion of men’s grooming and inclusive beauty, as cultural norms around male self-care continue to evolve. Mexican men are increasingly adopting skincare routines and exploring haircare and beard care products, driven by social media influence and celebrity endorsements, while brands launch gender-neutral products and expand shade ranges to cater to diverse skin tones. In August 2025, Ulta Beauty opened its first stores in Mexico through a partnership with Grupo Axo, demonstrating the market’s receptivity to new retail concepts.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=22200&flag=C

Mexico Beauty and Personal Care Industry Segmentation Insights

Breakup by Product Type:

  • Skin Care: Leads the market with a 27% share in 2025, including facial care, lip care, body care, and foot and hand care, driven by increasing consumer focus on preventive skincare routines, anti-aging solutions, and growing preference for natural ingredient formulations.
  • Oral Care: Serves consistent consumer demand for dental hygiene and oral health products.
  • Hair Care: Benefits from diverse consumer needs spanning styling, treatment, and everyday hair maintenance products.
  • Perfumes and Fragrances: Represents a significant category driven by personal expression and gifting occasions.
  • Deodorants: Maintains steady demand as an everyday personal care essential.
  • Bath and Shower: Serves core hygiene needs across Mexican households.
  • Color Cosmetics: Benefits from growing interest in makeup and self-expression among younger consumers.

Breakup by Category:

  • Mass: Leads with a 74% share in 2025, owing to widespread accessibility through supermarkets and convenience stores, affordability appealing to price-conscious consumers, and availability of trusted household brands.
  • Premium: Represents the higher-value segment, appealing to consumers seeking elevated formulations and international brand experiences.

Breakup by Distribution Channel:

  • Supermarkets/Hypermarkets: Leads with a 37% share in 2025, reflecting consumer preference for one-stop shopping experiences, competitive pricing through promotional campaigns, and convenient access to diverse product ranges.
  • Specialty/Beauty Stores: Offers curated selections and expert guidance for premium and specialized beauty products.
  • Convenience/Grocery Stores: Serves quick, accessible purchase occasions for everyday personal care essentials.
  • Pharmacies/Drugstores: Supports distribution of dermatologically tested and health-focused beauty products.
  • Online Retail Stores: Growing rapidly, driven by e-commerce expansion, social commerce, and digital beauty discovery platforms.
  • Others: Includes additional retail formats supporting beauty and personal care distribution.

Breakup by Region:

  • Central Mexico: Leads with a 41% share in 2025, anchored by Mexico City’s high-income households, sophisticated retail infrastructure, and strong penetration of both premium and mass-market beauty channels.
  • Northern Mexico: Benefits from higher income levels and strong demand for premium beauty products.
  • Southern Mexico: An emerging region with growing beauty and personal care consumption as retail networks expand.
  • Others: Comprises smaller regional markets experiencing gradual growth in beauty product demand.

Key Challenges and Growth Opportunities in the Mexico Beauty and Personal Care Market

The Mexico beauty and personal care market faces challenges including the proliferation of counterfeit products and gray market distribution, which poses risks to consumer safety and undermines brand value, particularly in premium segments. Economic uncertainty and price sensitivity, along with evolving COFEPRIS regulatory requirements and rising raw material costs, also pose ongoing considerations for manufacturers and retailers.

Despite these challenges, the market offers considerable growth opportunities driven by rising disposable income and middle-class expansion, growing social media influence shaping digital beauty culture, and increasing consumer preference for natural and organic products rooted in Mexico’s biodiversity. Continued international brand expansion, nearshoring of manufacturing facilities, and regulatory improvements by COFEPRIS are expected to create substantial opportunities for long-term growth in the Mexico beauty and personal care market.

Competitive Landscape

The Mexico beauty and personal care market exhibits a moderately concentrated competitive structure featuring established multinational corporations alongside emerging local brands. Major international players leverage their global expertise, extensive brand portfolios, and sophisticated distribution networks to maintain market leadership, while local manufacturers differentiate through culturally relevant formulations and competitive pricing. Companies compete through continuous product innovation, strategic marketing investments, and expansion of digital engagement capabilities, with the market witnessing increased investment in manufacturing infrastructure as nearshoring trends position Mexico as a strategic production hub for serving North American demand.

Recent Developments in the Mexico Beauty and Personal Care Market

  • August 2025: Ulta Beauty opened its first stores in Mexico through a partnership with Grupo Axo, marking the U.S. beauty retailer’s entry into the Mexican market.
  • February 2025: Mexican skincare brand Aora partnered with RePurpose Global to launch a plastic-free skincare initiative, becoming certified as a plastic-negative brand using recyclable materials like tin and wood in its packaging.
  • February 2025: TikTok Shop launched in Mexico, enabling beauty brands to achieve double-digit sales increases through promotional livestreams and user-generated content strategies.
  • September 2023: Korean beauty conglomerate Amorepacific launched its Laneige skincare brand in Mexico through a partnership with Sephora Mexico, introducing K-beauty innovations to Mexican consumers.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Commercial Real Estate Market Size, Share, Growth, Trends Analysis, Report 2026-2034

United States Commercial Real Estate Market Size, Share, Growth, Trends Analysis, Report 2026-2034

IMARC Group has recently released a new research study titled “United States Commercial Real Estate Market Size, Share, Trends and Forecast by Type and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Commercial Real Estate Market Size & Share 2026-2034

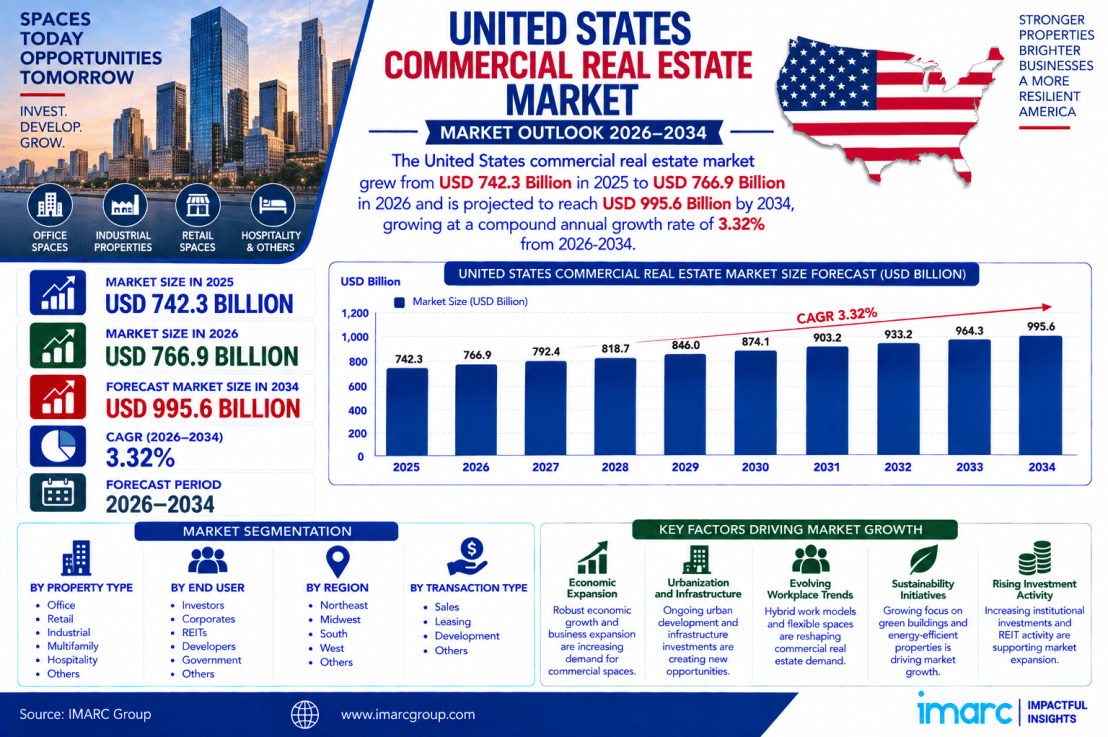
The United States commercial real estate market grew from USD 742.3 Billion in 2025 to USD 766.9 Billion in 2026 and is projected to reach USD 995.6 Billion by 2034, expanding at a CAGR of 3.32% during 2026–2034. The market is experiencing steady expansion, driven by robust demand for industrial and logistics properties, sustained e-commerce growth, and population migration toward economically vibrant regions.

Favorable business climates in emerging metropolitan areas, coupled with ongoing infrastructure development and technological advancements in building systems, continue to attract institutional investments in 2026. The diversified nature of property types, including offices, retail spaces, warehouses, and multifamily housing, supports resilient performance across economic cycles, strengthening the United States commercial real estate market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 742.3 Billion
  • Market Size (2026): USD 766.9 Billion
  • Projected Market Size (2034): USD 995.6 Billion
  • Growth Rate: CAGR of 3.32% (2026-2034)
  • Leading Type (2025): Industrial, holding a 26.96% share
  • Leading Region (2025): South, holding a 29% share

Explore Opportunities in the United States Commercial Real Estate Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-commercial-real-estate-market/requestsample

Key Growth Drivers and Trends in the United States Commercial Real Estate Market

Growth in the United States commercial real estate market is being driven by the sustained expansion of e-commerce, which continues to serve as a primary catalyst for demand within the industrial and logistics segment. The United States e-commerce market size reached USD 1,236.5 Billion in 2025, with online retail sales capturing an increasing share of total consumer spending, necessitating extensive warehouse networks positioned near major population centers to facilitate rapid order fulfillment. The Census Bureau reported that projected U.S. retail e-commerce sales for the third quarter of 2025 reached USD 310.3 Billion, reflecting continued momentum that is compelling retailers to expand both large-scale regional distribution centers and smaller last-mile facilities.

One of the leading United States commercial real estate market trends is population migration toward Sun Belt states, as warmer climates, lower state taxes, affordable housing, and expanding employment opportunities attract households and businesses from higher-cost coastal markets. This migration pattern is generating demand for multifamily housing, retail centers, and office space in emerging metropolitan areas, while major corporations relocate headquarters and expand operations in states offering favorable business environments, further accelerating commercial real estate development across the South and Southwest.

Another key factor supporting United States commercial real estate market growth is the accelerating adoption of AI, cloud computing, and digital business operations, generating unprecedented demand for data centers and technology-enabled commercial properties. The United States AI market size reached USD 41,532.7 Million in 2025, with hyperscale data center development moving at a rapid pace to support growing computational needs. The commercial real estate sector is increasingly integrating smart building technology, energy management solutions, and advanced connectivity infrastructure to attract technology-oriented tenants amid a broader flight to quality reshaping tenant preferences across all property types.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20946&flag=C

United States Commercial Real Estate Industry Segmentation Insights

Breakup by Type:

  • Industrial: Leads the market with a 26.96% share in 2025, driven by sustained demand for warehouse and distribution facilities supporting e-commerce fulfillment, with Modern Class A warehouses featuring higher clear heights and automation-ready infrastructure commanding premium rents.
  • Offices: Continues to experience a pronounced flight to quality, with prime vacancy rates significantly lower than non-prime properties as companies prioritize buildings with advanced technological infrastructure and sustainability certifications.
  • Retail: Benefits from adaptive reuse and mixed-use development trends as landlords reposition assets and invest in experiential formats to offset e-commerce-driven disruption.
  • Logistics: Sees strong demand from third-party logistics providers expanding warehousing and fulfillment networks near ports, highways, and major consumer hubs.
  • Multi-Family: Benefits from population migration trends and household formation in emerging Sun Belt metropolitan areas.
  • Hospitality: Reflects steady demand supported by tourism and business travel across key metropolitan and coastal markets.

Breakup by Region:

  • South: Leads with a 29% share in 2025, driven by sustained population influx, favorable business climates, and lower tax environments attracting corporate relocations, with Texas and Florida experiencing rapid expansion across industrial, multifamily, and retail segments.
  • West: Benefits from strong technology sector presence and data center development supporting demand for advanced commercial real estate infrastructure.
  • Northeast: Maintains appeal for premium office and retail assets in gateway cities, supported by institutional investor demand for high-quality, stable cash-flow properties.
  • Midwest: Shows steady demand supported by manufacturing clusters and logistics activity tied to core industrial markets such as Chicago.

Key Challenges and Growth Opportunities in the United States Commercial Real Estate Market

The United States commercial real estate market faces challenges including persistently elevated interest rates that continue to constrain financing activities and suppress transaction volumes, particularly impacting properties requiring refinancing at significantly higher rates than those originated during the prior low-rate environment. Increasing frequency and severity of natural disasters are elevating climate-related risks and insurance premium inflation, particularly in coastal and wildfire-prone regions, while structural shifts toward remote and hybrid work models continue to reduce demand for traditional office space in many urban cores.

Despite these challenges, the market offers considerable growth opportunities driven by improving capital market conditions and firming fundamentals across most property sectors as interest rates moderate and property values stabilize, enabling more favorable refinancing conditions. The ongoing digital economy expansion, driven by e-commerce growth and AI adoption, is expected to sustain demand for logistics facilities and data centers, creating substantial opportunities for long-term growth in the United States commercial real estate market.

Competitive Landscape

The United States commercial real estate market features a diverse competitive landscape, comprising real estate investment trusts, private equity firms, institutional investors, and specialized property developers. Market participants compete through strategic acquisitions, portfolio diversification, and operational excellence while differentiating through specialized sector expertise and geographic focus. Industry leaders are investing in technological capabilities, sustainability initiatives, and tenant experience enhancements to maintain competitive positioning, with increased consolidation occurring as larger players pursue scale advantages and operational synergies through mergers and acquisitions. Competition for high-quality assets remains intense, particularly in sectors demonstrating strong fundamentals, including industrial, multifamily, and data center properties.

Recent Developments in the United States Commercial Real Estate Market

  • January 2026: SVN Commercial Partners unveiled the resumption of the sale for the Waterfront Property in Fishermen’s Village, Punta Gorda, Florida, including over 97,000 square feet of retail and office areas, five fully leased waterfront eateries, a permitted marina with 142 wet slips and upland development rights, plus 47 two-bedroom, two-bath waterfront hotel apartment suites.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Display Market Size Worth USD 55.0 Billion by 2034 | CAGR: 2.66%: IMARC Group

United States Display Market Size Worth USD 55.0 Billion by 2034 | CAGR: 2.66%: IMARC Group

IMARC Group has recently released a new research study titled “United States Display Market Report by Display Type (Flat Panel Display, Flexible Panel Display, Transparent Panel Display), Technology (OLED, Quantum Dot, LED, LCD, E-paper, and Others), Application (Smartphone and Tablet, Smart Wearable, Television and Digital Signage, PC and Laptop, Vehicle Display, and Others), Industry Vertical (BFSI, Retail, Healthcare, Consumer Electronics, Military and Defense, Automotive, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Display Market Size & Share 2026-2034

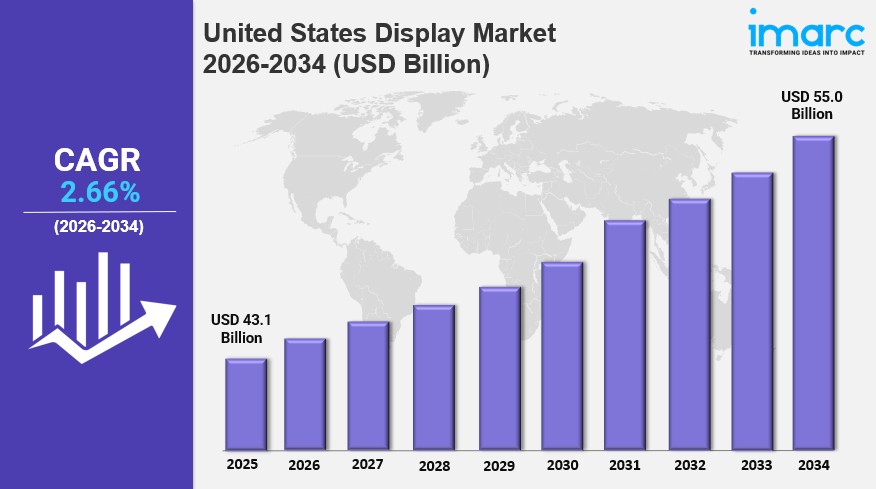
The United States display market size reached USD 43.1 Billion in 2025 and is projected to reach USD 55.0 Billion by 2034, expanding at a CAGR of 2.66% during 2026–2034. The increasing adoption of advanced display technologies across various industries, the proliferation of smartphones, tablets, wearables, and smart home devices, and robust economic growth and increased disposable income levels are among the key factors driving the market. mention this value only

Rising consumer demand for high-definition, interactive displays across industries continues to fuel growth, with advanced technologies including OLED, LED, and microLED gaining traction in smartphones, gaming, and automotive applications, while digital transformation initiatives across healthcare, retail, and education verticals significantly boost display technology investments nationwide.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Base Year Market Size (2025): USD 43.1 Billion
  • Forecast Market Size (2034): USD 55.0 Billion
  • Growth Rate: CAGR of 2.66% (2026-2034)

Explore Opportunities in the United States Display Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-display-market/requestsample

Key Growth Drivers and Trends in the United States Display Market

Growth in the United States display market is being driven by innovation in flexible and wearable display technologies, as foldable displays, rollable displays, and bendable OLED panels gain popularity in smartphones, smartwatches, and other wearable products, enabling compact form factors without sacrificing image quality. Research on lightweight, low-power displays is also gaining traction in healthcare and fitness markets, where wearables depend on crisp, resilient screens.

One of the leading United States display market trends is the shift toward sustainability and energy-efficient display adoption, as businesses and consumers increasingly seek displays with smaller carbon footprints, such as OLED, MiniLED, and quantum dot screens that run more efficiently while offering better images. Manufacturers are adapting with eco-friendly production processes, recycling initiatives, and green materials to meet regulatory and consumer demands.

Another key factor supporting market growth is the deepening integration of displays into automotive and smart infrastructure, as car dashboards, infotainment centers, and head-up displays add high-definition touchscreens, while public areas, offices, and retail spaces incorporate digital signage and interactive kiosks. In September 2025, Meta launched its first consumer-ready smart glasses with a built-in display, the Meta Ray-Ban Display, featuring notifications on the right lens and gesture-based controls.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=10199&flag=C

United States Display Industry Segmentation Insights

Breakup by Display Type:

  • Flat Panel Display: The established display format spanning smartphones, televisions, monitors, and digital signage applications.
  • Flexible Panel Display: Growing rapidly with foldable and bendable OLED panels used in wearables and next-generation smartphones.
  • Transparent Panel Display: An emerging category used in automotive, retail, and smart infrastructure applications.

Breakup by Technology:

  • OLED: Delivers deep blacks and vivid colors, widely adopted in premium smartphones, TVs, and wearables.
  • Quantum Dot: Offers enhanced brightness and color accuracy for premium display applications.
  • LED: Provides energy-efficient, cost-competitive performance across a broad range of devices.
  • LCD: Remains a widely used technology for value-oriented display applications.
  • E-paper: Supports low-power, high-readability applications such as e-readers and signage.
  • Others: Includes additional and emerging display technologies.

Breakup by Application:

  • Smartphone and Tablet: Represents a core application area driven by continuous device upgrade cycles.
  • Smart Wearable: A fast-growing segment supported by advances in flexible and low-power display technology.
  • Television and Digital Signage: Covers large-format consumer and commercial display applications.
  • PC and Laptop: Serves computing device demand across consumer and enterprise segments.
  • Vehicle Display: Growing quickly with the integration of dashboards, infotainment, and head-up displays.
  • Others: Includes additional consumer and industrial display applications.

Breakup by Industry Vertical:

  • BFSI: Uses displays in digital banking kiosks, ATMs, and customer service touchpoints.
  • Retail: Incorporates displays in digital signage, interactive kiosks, and point-of-sale systems.
  • Healthcare: Applies displays in diagnostic imaging, patient monitoring, and telehealth systems.
  • Consumer Electronics: A leading vertical spanning smartphones, TVs, laptops, and wearable devices.
  • Military and Defense: Utilizes ruggedized displays for command, control, and communication systems.
  • Automotive: Growing steadily with expanding in-vehicle display and infotainment integration.
  • Others: Includes additional industrial and commercial display applications.

Breakup by Region:

  • Northeast: Supported by dense population centers and strong enterprise and healthcare display adoption.
  • Midwest: Benefits from steady industrial and automotive display demand.
  • South: A leading region supported by population growth and expanding retail and consumer electronics demand.
  • West: Driven by technology-forward consumer preferences and strong presence of display innovators.

Key Challenges and Growth Opportunities in the United States Display Market

The United States display market faces challenges including supply chain disruptions and raw material cost volatility that affect production planning, and increasingly stringent environmental sustainability requirements that require ongoing investment in eco-friendly manufacturing processes.

Despite these challenges, the market offers considerable growth opportunities driven by emerging applications including automotive displays, smart infrastructure, and wearable technologies, along with miniaturization trends and power efficiency improvements that unlock new market segments. Continued innovation in flexible, transparent, and energy-efficient display technologies is expected to support long-term growth in the United States display market.

Competitive Landscape

The United States display market is shaped by market consolidation as leading manufacturers focus on technological innovation and strategic partnerships. Companies are investing in research and development for next-generation technologies while leveraging vertical integration, supply chain optimization, and customization capabilities to maintain competitive advantages in this rapidly evolving industry.

Recent Developments in the United States Display Market

  • September 2025: Meta launched its first consumer-ready smart glasses with a built-in display, the Meta Ray-Ban Display, featuring notifications on the right lens and gesture-based controls designed to provide AI-driven experiences.
  • January 2025: Tianma showcased a wide range of advanced automotive display technologies at CES, including dual-screen multi-curved OLEDs, 3D instrument clusters, Mini-LED InvisiVue, and Light Field 3D-HUD systems.
  • December 2024: Apple was reported to be collaborating with Samsung Display and LG Display to develop a future iPhone featuring zero-bezel OLED technology and under-panel cameras.
  • January 2025: LG Display unveiled its fourth-generation OLED TV panel, optimized for the AI era, featuring enhanced brightness, ultra-low reflection, and energy-efficient design.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Pharmacy Market Size is Expected to Reach USD 937.4 Billion by 2034 | CAGR 3.72%

United States Pharmacy Market Size is Expected to Reach USD 937.4 Billion by 2034 | CAGR 3.72%

IMARC Group has recently released a new research study titled “United States Pharmacy Market Report by Product Type (Prescription, OTC), Pharmacy Type (Hospital Pharmacy, Retail Pharmacy, ePharmacy, and Others), Ownership (Independent, Chain), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Pharmacy Market Size & Share 2026-2034

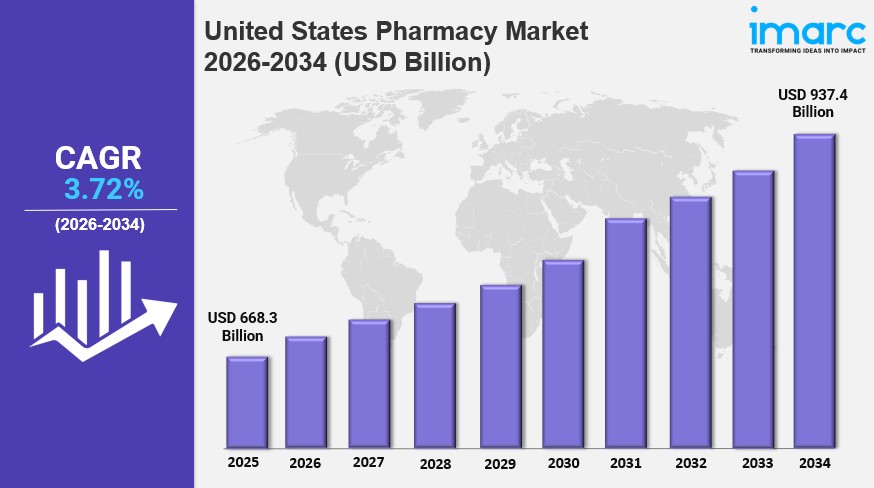
The United States pharmacy market size reached USD 668.3 Billion in 2025 and is projected to reach USD 937.4 Billion by 2034, expanding at a CAGR of 3.72% during 2026-2034. The growth of the pharmacy market is driven by the increasing incidence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions, which leads to higher demand for medications.

Rising regional population, growing healthcare awareness, and advancements in medical research and technology further influence the United States pharmacy market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 668.3 Billion
  • Projected Market Size (2034): USD 937.4 Billion
  • Growth Rate: CAGR of 3.72% (2026-2034)

Explore Opportunities in the United States Pharmacy Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-pharmacy-market/requestsample

Key Growth Drivers and Trends in the United States Pharmacy Market

Growth in the United States pharmacy market is being driven by rising population and healthcare awareness, as the increasing regional population and growing awareness of healthcare needs significantly propel demand for pharmaceutical products. As the population grows, so does the need for medications, creating sustained upward pressure on the pharmacy market, while advancements in medical research and technology serve as catalysts driving the development of innovative drugs and therapies.

One of the leading United States pharmacy market trends is the aging demographic and rising chronic disease burden, as the elderly typically require a higher volume of medications and healthcare services, contributing substantially to the expanding pharmacy market. The prevalence of chronic diseases, fueled by lifestyle changes and environmental factors, underscores the importance of pharmaceutical interventions, further amplifying demand for a diverse range of medications.

Another key factor supporting United States pharmacy market growth is the expanding role of e-commerce and digital health solutions, as online pharmacies and telehealth platforms gain traction, offering consumers a seamless and efficient way to fulfill their healthcare needs. These digital channels facilitate convenient access to pharmaceutical products and services, complementing the growth of retail pharmacy chains and specialty drug development.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21066&flag=C

United States Pharmacy Industry Segmentation Insights

Breakup by Product Type:

  • Prescription: Represents the core segment, driven by rising chronic disease prevalence and growing demand for specialty and maintenance medications.
  • OTC: Covers over-the-counter medications supporting self-care and everyday health management needs.

Breakup by Pharmacy Type:

  • Hospital Pharmacy: Supports inpatient and outpatient medication needs within healthcare facility settings.
  • Retail Pharmacy: Represents a widely accessible channel for prescription and OTC medications across communities.
  • ePharmacy: Growing rapidly through online platforms offering convenient home delivery and digital health integration.
  • Others: Includes additional pharmacy formats supporting specialized medication distribution needs.

Breakup by Ownership:

  • Independent: Represents locally owned pharmacies offering personalized service and community-focused care.
  • Chain: Covers large multi-location pharmacy networks benefiting from scale, brand recognition, and broad accessibility.

Breakup by Region:

  • Northeast: Benefits from dense population centers and strong healthcare infrastructure supporting pharmacy demand.
  • Midwest: Reflects steady demand driven by established healthcare networks and chronic disease management needs.
  • South: Represents a leading regional market, supported by population growth and expanding retail pharmacy presence.
  • West: Benefits from strong adoption of digital health solutions and ePharmacy services.

Key Challenges and Growth Opportunities in the United States Pharmacy Market

The United States pharmacy market faces challenges including rising drug pricing pressures, complex regulatory compliance requirements, and reimbursement policy changes that can affect pharmacy operations and profitability. Competition between independent and chain pharmacies also shapes market dynamics amid evolving consumer preferences.

Despite these challenges, the market offers considerable growth opportunities driven by continued adoption of digital health and ePharmacy solutions, growth in specialty and personalized medicine, and expansion of retail pharmacy chains. Rising chronic disease management needs and increased healthcare access are expected to create substantial opportunities for long-term growth in the United States pharmacy market.

Competitive Landscape

The United States pharmacy market is shaped by both independent operators and large chain pharmacy networks expanding their footprint through digital health integration and service diversification. Companies are investing in ePharmacy platforms, telehealth partnerships, and personalized medication management services to differentiate their offerings and meet growing consumer demand for convenient, accessible, and comprehensive pharmacy care.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Yogurt Market Size to Reach USD 2.9 Billion by 2034 at 5.68% CAGR

Mexico Yogurt Market Size to Reach USD 2.9 Billion by 2034 at 5.68% CAGR

IMARC Group has recently released a new research study titled “Mexico Yogurt Market Size, Share, Trends and Forecast by Product Type, Flavor, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Yogurt Market Size & Share 2026-2034

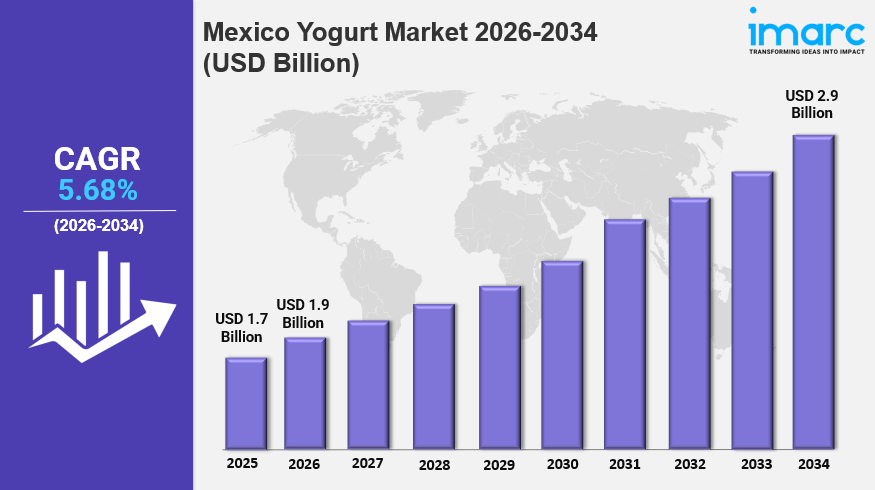
The Mexico yogurt market size increased from USD 1.7 Billion in 2025 to USD 1.9 Billion in 2026. Looking forward, the market is expected to reach USD 2.9 Billion by 2034, exhibiting a growth rate (CAGR) of 5.68% during 2026-2034. The market is experiencing significant growth driven by increasing demand for healthy, functional, and organic options.

Flavored and drinkable yogurts are gaining popularity, particularly among younger consumers, while clean-label preferences boost the adoption of organic and preservative-free products, collectively shaping the Mexico yogurt market throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Base Year Market Size (2025): USD 1.7 Billion
  • Market Size (2026): USD 1.9 Billion
  • Forecast Market Size (2034): USD 2.9 Billion
  • Growth Rate: CAGR of 5.68% (2026-2034)

Explore Opportunities in the Mexico Yogurt Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-yogurt-market/requestsample

Key Growth Drivers and Trends in the Mexico Yogurt Market

Growth in the Mexico yogurt market is being driven by rising demand for healthy and functional foods, as Mexican consumers become increasingly health-conscious and seek functional foods that provide added health benefits. Yogurt products with added probiotics, high protein content, and low sugar levels are gaining popularity, with probiotic yogurts appealing to consumers looking for digestive health benefits, while high-protein options are embraced by fitness enthusiasts seeking muscle recovery or weight management. In November 2024, LALA, a Mexican dairy brand, launched LALA Gold, a high-protein yogurt available in drinkable (25g protein, 6g fiber) and spoonable (20g protein) formats featuring no added sugar across five flavors.

One of the leading Mexico yogurt market trends is expansion of flavored and drinkable yogurt segments, as these variants rapidly gain popularity, especially among younger and urban consumers seeking convenience and diverse taste experiences. Flavored yogurts in fruity and dessert-inspired options attract consumers looking for both taste and health benefits, while drinkable yogurt formats see significant growth for on-the-go consumption, aligning with fast-paced urban lifestyles and proving particularly popular among millennials and Gen Z.

Another key factor supporting Mexico yogurt market growth is growth of organic and natural yogurt products, as consumers become more health-conscious and aware of ingredients, driving growing preference for products free from artificial additives, preservatives, and chemicals. Organic yogurt made from milk produced without synthetic pesticides or fertilizers is particularly attractive to consumers seeking environmentally friendly and sustainable food options, with demand also driven by concerns over long-term health impacts associated with highly processed foods.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32945&flag=C

Mexico Yogurt Industry Segmentation Insights

Breakup by Product Type:

  • Set Yogurt: Represents a traditional yogurt format supporting broad consumer accessibility and established purchasing habits.
  • Greek Yogurt: Benefits from strong demand for high-protein, thick-textured yogurt formats among health-conscious consumers.
  • Yogurt Drinks: Growing rapidly for on-the-go consumption, particularly appealing to millennials and Gen Z urban consumers.
  • Frozen Yogurt: Supports demand for indulgent, dessert-oriented yogurt formats.
  • Others: Includes additional yogurt product formats supporting diverse consumer preferences.

Breakup by Flavor:

  • Strawberry Blend: Represents a popular flavor combination appealing to fruity and dessert-inspired taste preferences.
  • Vanilla: Supports classic, widely popular flavor demand across product formats.
  • Plain: Caters to health-conscious consumers and those using yogurt as a versatile ingredient.
  • Strawberry: Remains a consistently popular fruit flavor across yogurt product categories.
  • Peach: Supports demand for fruit-forward flavor variety in the market.
  • Others: Includes additional flavor varieties supporting diverse consumer tastes.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Provides broad accessibility for yogurt products across general retail channels.
  • Convenience Stores: Supports accessible, everyday purchasing options for yogurt products.
  • Specialty Stores: Offers curated assortments for health-focused and premium yogurt consumers.
  • Online Stores: Growing channel offering convenient home delivery and expanded product selection.
  • Others: Includes additional distribution formats supporting market reach.

Breakup by Region:

  • Northern Mexico: Benefits from strong dairy production infrastructure and established retail networks.
  • Central Mexico: Represents a leading regional market, anchored by dense urban population and retail infrastructure.
  • Southern Mexico: An emerging market with growing retail access and health-conscious consumer awareness.
  • Others: Includes additional regional markets contributing to national yogurt demand.

Key Challenges and Growth Opportunities in the Mexico Yogurt Market

The Mexico yogurt market faces challenges including price sensitivity among broader consumer segments limiting premium and functional product adoption, competition from other dairy and non-dairy snack alternatives, and the need for continued cold chain infrastructure investment to support product freshness across distribution channels.

Despite these challenges, the market offers considerable growth opportunities driven by continued demand for probiotic and high-protein functional yogurt, expansion of flavored and drinkable yogurt formats among younger consumers, and rising adoption of organic and clean-label products. Growing brand innovation in packaging, texture, and flavor variety are expected to create substantial opportunities for long-term growth in the Mexico yogurt market.

Competitive Landscape

The Mexico yogurt market is shaped by both domestic and international operators expanding their footprint through new product launches and functional innovation. Companies are investing in high-protein, low-sugar, and probiotic-enriched formulations, along with organic and clean-label product lines, to differentiate their offerings and meet growing consumer demand for health-focused, convenient, and great-tasting yogurt products.

Recent Developments in the Mexico Yogurt Market

  • November 2024: LALA, a Mexican dairy brand, announced the launch of LALA Gold, a high-protein yogurt aimed at health-conscious consumers. Available in drinkable (25g protein, 6g fiber) and spoonable (20g protein) formats, it features no added sugar and comes in five flavors, catering to growing demand in the yogurt market.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Frozen Pizza Market Size is Expected to Reach USD 11,012.8 Million by 2034 | CAGR 4.64%

United States Frozen Pizza Market Size is Expected to Reach USD 11,012.8 Million by 2034 | CAGR 4.64%

IMARC Group has recently released a new research study titled “United States Frozen Pizza Market Size, Share, Trends and Forecast by Crust Type, Size, Product Type, Topping, Distribution, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Frozen Pizza Market Size & Share 2026-2034

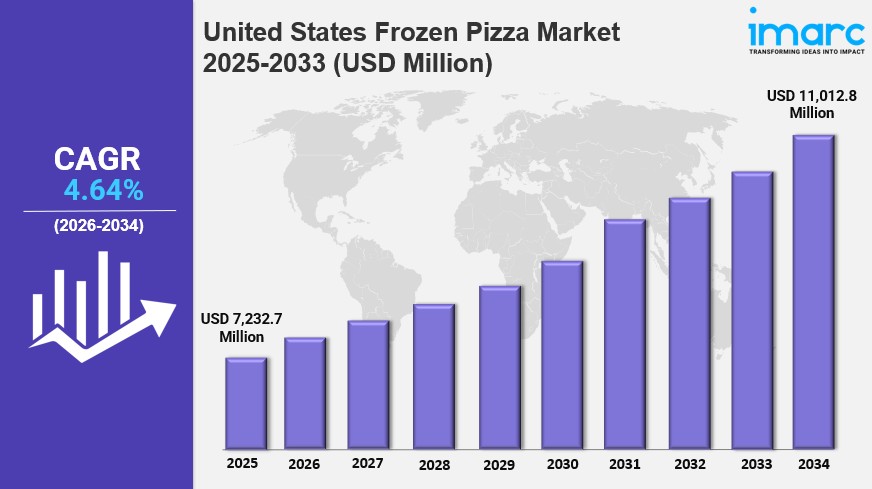
The United States frozen pizza market size reached USD 7,232.7 Million in 2025 and is projected to reach USD 11,012.8 Million by 2034, expanding at a CAGR of 4.64% during 2026-2034. The Midwest currently dominates the market, supported by deep-rooted regional food traditions and strong household penetration. Growth is driven by rising consumer demand for convenient, ready-to-eat meals that fit busy, fast-paced lifestyles.

Innovation across crust types, toppings, and healthier formulations is helping brands attract a wider and more diverse consumer base in 2026. Strong retail distribution, intense brand competition, and the entry of foodservice chains into the retail freezer aisle continue to shape the evolving United States frozen pizza market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 7,232.7 Million
  • Projected Market Size (2034): USD 11,012.8 Million
  • Growth Rate: CAGR of 4.64% (2026-2034)

Explore Opportunities in the United States Frozen Pizza Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-frozen-pizza-market

Key Growth Drivers and Trends in the United States Frozen Pizza Market

Rising workforce participation and shifting lifestyle preferences are a major factor behind rising frozen pizza consumption. As American households juggle demanding work schedules, ready-to-eat meal formats are becoming a bigger part of everyday routines, with convenience-driven behavior notably stronger among Millennial and Gen Z consumers. Inflationary pressure on dining-out budgets is also pushing families toward affordable at-home alternatives, reinforcing frozen pizza’s position as a value-driven meal solution.

Another leading United States frozen pizza market trends is the pace of product innovation. Manufacturers are expanding into gluten-free, whole wheat, multigrain, dairy-free, and other health-focused crust and topping options to meet growing demand for cleaner-label, allergen-friendly products. At the same time, premium and gourmet formats designed to replicate restaurant-quality taste and presentation are helping brands capture consumers seeking indulgence without leaving home.

Growing fast-food affinity among younger consumers is also supporting market growth. Younger age groups, who prioritize speed, affordability, and variety, are consuming quick-service and convenience food more frequently than older generations, making frozen pizza a natural fit for their eating habits. Meanwhile, food-chain brands are extending their restaurant identities into the retail freezer aisle, and manufacturing capacity expansions by major food conglomerates are strengthening domestic supply and competitive intensity across the country.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=3080&flag=C

United States Frozen Pizza Industry Segmentation Insights

Breakup by Crust Type:

  • Thin Crust: Appeals to consumers seeking a lighter, crispier eating experience with classic pizzeria-style appeal.
  • Thick Crust: Offers a heartier, bread-forward bite favored by consumers looking for a more filling meal.
  • Stuffed Crust: Holds the largest share, driven by its indulgent, cheese-filled format and strong association with comfort food.
  • Others: Includes additional crust formats catering to niche and evolving consumer preferences.

Breakup by Size:

  • Small: Suits single-serve occasions and portion-conscious consumers.
  • Medium: Leads the market, valued for its balance of portion size, affordability, and everyday convenience for small families and individuals.
  • Large: Preferred for family gatherings and multi-serving occasions.

Breakup by Product Type:

  • Regular Frozen Pizza: Leads the market due to its broad familiarity, competitive pricing, and consistent availability across retail channels.
  • Premium Frozen Pizza: Targets consumers seeking elevated ingredients and restaurant-style quality at home.
  • Gourmet Frozen Pizza: Caters to consumers pursuing distinctive flavors and artisanal crust styles.

Breakup by Topping:

  • Cheese: Remains a foundational and widely consumed topping category across all pizza formats.
  • Meat: Leads the market, driven by strong consumer preference for protein-rich, indulgent options such as pepperoni and sausage.
  • Fruits and Vegetables: Supports demand from health-conscious and vegetarian-leaning consumers.
  • Others: Covers specialty and combination topping formats.

Breakup by Distribution:

  • Food Chain Services: Holds the largest share as branded restaurant-style frozen pizzas build on established consumer trust and recognition.
  • Modern Trade: Benefits from wide retail footprint and consistent promotional activity in supermarkets and hypermarkets.
  • Departmental Stores: Provides accessible everyday purchase options for regional and local shoppers.
  • Online Stores: Emerging as a growing channel supported by expanding e-commerce and online grocery adoption.
  • Others: Includes additional retail and foodservice distribution formats.

Breakup by Region:

  • Northeast: Supported by dense urban populations and strong retail infrastructure.
  • Midwest: Dominates the market, rooted in the region’s historic ties to frozen pizza and demand for easy-to-store comfort food during cold winters.
  • South: Growing steadily on the back of expanding retail networks and rising household demand.
  • West: Reflects increasing interest in premium, gourmet, and health-focused frozen pizza formats.

Key Challenges and Growth Opportunities in the United States Frozen Pizza Market

The United States frozen pizza market faces challenges such as intense competition among established national brands and growing private-label alternatives, along with the need to continually balance affordability with rising input and packaging costs. Meeting the evolving expectations of health-conscious consumers, including demand for gluten-free, dairy-free, and reduced-preservative formulations, also requires sustained investment in product development.

Despite these challenges, the market offers considerable growth opportunities through continued premiumization, expansion of plant-based and allergen-friendly product lines, and deeper penetration of online grocery and delivery channels. Strategic collaborations between food brands, retailers, and quick-service chains aimed at translating recognizable flavors into frozen formats are expected to create substantial opportunities for long-term growth in the United States frozen pizza market.

Competitive Landscape

The United States frozen pizza market is highly competitive, led by major players including Nestlé, Schwan’s Company, and General Mills, which compete on product variety, flavor innovation, and pricing. Retail private-label brands are gaining traction by offering quality-focused, budget-friendly alternatives, while foodservice brands are expanding into the retail freezer aisle to extend their restaurant identities into at-home consumption. Companies are increasingly investing in premium, gluten-free, and plant-based product development to capture shifting consumer preferences and defend their competitive position.

Recent Developments in the United States Frozen Pizza Market

  • June 2025: Nestlé introduced a new wood-fired style crust pizza line under its DiGiorno brand, its first major frozen pizza innovation in about a decade, aimed at capturing a larger share of the broader U.S. pizza market with premium, restaurant-style options.
  • May 2025: A leading Northeast grocery chain launched a new Roman-style frozen pizza line made with Italian-crafted crusts, expanding its private-label frozen pizza offerings across its store network.
  • May 2025: A well-known pasta sauce brand partnered with a private-label pizza manufacturer to launch a new frozen pizza line featuring its signature sauce across several varieties.
  • May 2025: A gluten-free food brand known for cauliflower-based crusts expanded its frozen pizza range with a new specialty flavor, reflecting continued innovation in alternative-crust formats.
  • January 2025: A U.S. food manufacturer acquired a frozen pizza and baking company, expanding its presence in the multibillion-dollar domestic frozen pizza market and strengthening its foodservice and private-label capabilities.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Current Sensor Market Size, Demands, Growth Analysis, Industry Report 2026-2034

United States Current Sensor Market Size, Demands, Growth Analysis, Industry Report 2026-2034

IMARC Group has recently released a new research study titled “United States Current Sensor Market Report by Type (Open Loop, Closed Loop), Current Sensing Technology (Hall Effect, Current Transformer, Flux Gate, Rogowski Coil), Sensing Method (Direct Current Sensing, Indirect Current Sensing), Application (Motor Drive, Converter and Inverter, Battery Management, Uninterrupted Power Supply (UPS) and Switched-Mode Power Supply (SMPS), Starter and Generators, Grid Infrastructure, and Others), End Use (Automotive, Consumer Electronics, Industrial, Healthcare, Telecom, Renewable Energy, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Current Sensor Market Size & Share 2026-2034

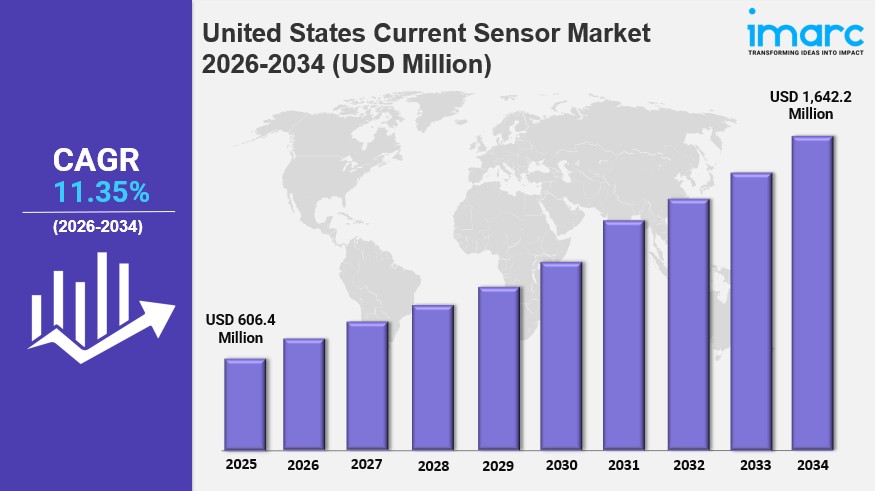
The United States current sensor market size reached USD 606.4 Million in 2025 and is projected to reach USD 1,642.2 Million by 2034, expanding at a CAGR of 11.35% during 2026-2034. The market is propelled by the growing need to safeguard equipment and prevent electrical fires or accidents, alongside rising demand for accurate current sensing across automotive, industrial, and consumer electronics applications.

Growth in 2026 is further reinforced by the increasing use of current sensors in electric vehicle (EV) charging infrastructure to regulate the current supplied to EV batteries and ensure safe, efficient charging. The rising focus on power management and network infrastructure optimization in the telecommunication sector, along with advancements in power electronics applications such as inverters and converters, continues to strengthen the United States current sensor market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 606.4 Million
  • Projected Market Size (2034): USD 1,642.2 Million
  • Growth Rate: CAGR of 11.35% (2026-2034)

Explore Opportunities in the United States Current Sensor Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-current-sensor-market/requestsample

Key Growth Drivers and Trends in the United States Current Sensor Market

Growth in the United States current sensor market is being driven by rising integration across diverse end-use sectors, notably within automotive, consumer electronics, industrial, healthcare, telecom, and renewable energy. Organizations are increasingly deploying current sensors to detect overcurrent conditions, short circuits, and electrical faults while enabling real-time monitoring of power usage. The escalating demand for current sensors to prevent damage, fires, or hazards in electronic devices is positively influencing the market, with current sensing increasingly regarded as essential infrastructure rather than an optional safety feature.

One of the leading United States current sensor market trends is the growing use of current sensors in electric vehicle (EV) and hybrid electric vehicle (HEV) applications, particularly for battery management and motor control. In parallel, manufacturers are advancing hall effect, current transformer, flux gate, and rogowski coil technologies to improve sensing accuracy across direct and indirect current sensing methods. Additionally, the rising adoption of current sensors in environmental monitoring systems and their expanding role in optimizing energy efficiency are creating new avenues for the market.

Another key factor supporting United States current sensor market growth is sustained investment in power electronics and grid infrastructure modernization. Advancements in inverters and converters are requiring more accurate current sensing for efficient energy conversion, while the telecommunications sector is increasingly relying on current sensors for power management and network infrastructure optimization. Growing demand for uninterrupted power supply (UPS) and switched-mode power supply (SMPS) systems, along with expanding motor drive and starter and generator applications, is further reinforcing the market outlook.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20166&flag=C

United States Current Sensor Industry Segmentation Insights

Breakup by Type:

  • Open Loop: Favored for its cost effectiveness, simplicity, and applicability across a wide variety of applications, remaining a widely adopted choice in the market.
  • Closed Loop: Offers higher accuracy and stability, supporting applications that demand precise current measurement.

Breakup by Current Sensing Technology:

  • Hall Effect: Preferable because of its high feasibility, low power consumption, small size, and ease of integration into electronic circuits.
  • Current Transformer: Widely used for measuring alternating current in industrial and grid infrastructure applications.
  • Flux Gate: Supports high-precision current sensing in demanding industrial and automotive environments.
  • Rogowski Coil: Enables accurate current measurement without direct electrical contact, suited to high-current applications.

Breakup by Sensing Method:

  • Direct Current Sensing: Involves measuring current directly within the circuit path for immediate, precise readings.
  • Indirect Current Sensing: Utilizes magnetic field detection to measure current without direct circuit contact, improving safety and flexibility.

Breakup by Application:

  • Motor Drive: Uses current sensors for precise control and protection of motor systems across industrial and automotive applications.
  • Converter and Inverter: Requires accurate current sensing for efficient energy conversion in power electronics applications.
  • Battery Management: Leverages current sensors for accurate current sensing solutions supporting EV and HEV battery management and motor control.
  • Uninterrupted Power Supply (UPS) and Switched-Mode Power Supply (SMPS): Relies on current sensors to maintain power quality and system reliability.
  • Starter and Generators: Utilizes current sensors to monitor and regulate current flow in starting and power generation systems.
  • Grid Infrastructure: Supports power quality assessment and fault detection across electrical networks.
  • Others: Includes additional application areas across specialized industrial and commercial use cases.

Breakup by End Use:

  • Automotive: Benefits from rising EV charging infrastructure and increasing demand for accurate battery and motor control sensing.
  • Consumer Electronics: Integrates current sensors to safeguard devices and optimize power efficiency.
  • Industrial: Deploys current sensors extensively for equipment protection, fault detection, and process monitoring.
  • Healthcare: Uses current sensors to ensure the safe and reliable operation of sensitive medical equipment.
  • Telecom: Applies current sensors for power management and network infrastructure optimization.
  • Renewable Energy: Supports current monitoring in solar, wind, and other renewable power generation and storage systems.
  • Others: Comprises additional end-use sectors experiencing gradual growth in current sensor adoption.

Breakup by Region:

  • Northeast: Benefits from a strong concentration of industrial, telecom, and healthcare end users adopting current sensing solutions.
  • Midwest: Anchored by a significant automotive and industrial manufacturing base driving current sensor demand.
  • South: Supported by expanding renewable energy investment and growing industrial and consumer electronics activity.
  • West: Benefits from a robust technology and EV ecosystem, alongside growing renewable energy and grid infrastructure investment.

Key Challenges and Growth Opportunities in the United States Current Sensor Market

The United States current sensor market faces challenges including the need for continued advancement in sensing accuracy and miniaturization to meet the evolving requirements of automotive, industrial, and consumer electronics applications. Ensuring cost-effective integration of current sensors into increasingly compact electronic systems, while maintaining reliability across demanding operating environments, also remains an ongoing consideration for manufacturers.

Despite these challenges, the market offers considerable growth opportunities driven by the expanding EV charging infrastructure, rising investment in grid modernization, and growing demand for renewable energy integration. Advancements in power electronics applications, such as inverters and converters, are creating lucrative opportunities for industry investors, while the increasing focus on energy conservation and efficiency across industries is expected to create substantial opportunities for long-term growth in the United States current sensor market.

Competitive Landscape

The United States current sensor market is competitive, with established sensor manufacturers and emerging technology providers focusing on improving sensing accuracy, miniaturization, and integration across hall effect, current transformer, flux gate, and rogowski coil technologies to strengthen their market position. Companies are increasingly investing in research and development to address the rising demand for current sensing solutions in EV charging, battery management, and grid infrastructure applications, while forming strategic partnerships to expand their presence across automotive, industrial, telecom, and renewable energy end-use sectors.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
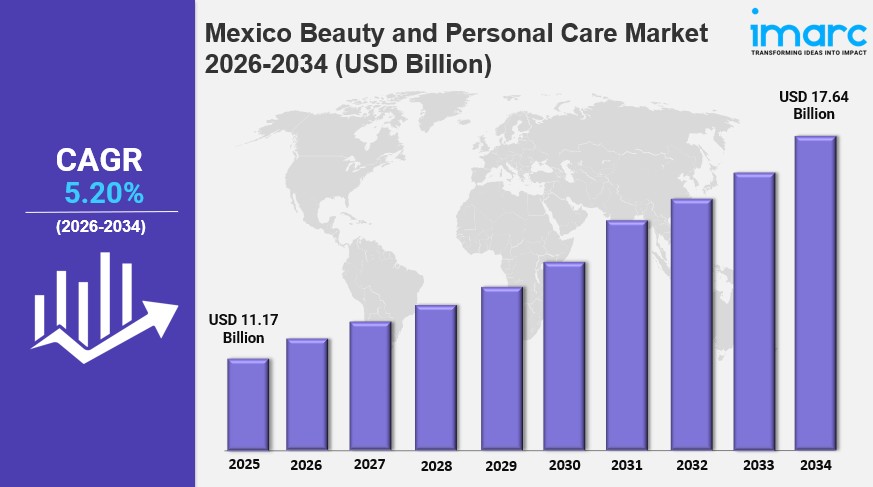
Mexico Beauty and Personal Care Market Size Worth USD 17.64 Billion by 2034 | CAGR: 5.20%: IMARC Group

Mexico Beauty and Personal Care Market Size Worth USD 17.64 Billion by 2034 | CAGR: 5.20%: IMARC Group

IMARC Group has recently released a new research study titled “Mexico Beauty and Personal Care Market Size, Share, Trends and Forecast by Product Type, Category, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Beauty and Personal Care Market Size & Share 2026-2034

The Mexico beauty and personal care market size reached USD 11.17 Billion in 2025 and is projected to reach USD 17.64 Billion by 2034, expanding at a CAGR of 5.20% during 2026-2034. The market is propelled by increasing consumer awareness about skincare and personal grooming, a growing middle-class population with higher disposable income, and the influence of social media and beauty influencers.

The cultural emphasis on appearance and wellness, coupled with rapid urbanization, drives demand for both premium and mass-market beauty products, while e-commerce expansion and the entry of international brands through strategic partnerships continue to reshape the Mexico beauty and personal care market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 11.17 Billion
  • Projected Market Size (2034): USD 17.64 Billion
  • Growth Rate: CAGR of 5.20% (2026-2034)

Explore Opportunities in the Mexico Beauty and Personal Care Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-beauty-personal-care-market/requestsample

Key Growth Drivers and Trends in the Mexico Beauty and Personal Care Market

Growth in the Mexico beauty and personal care market is being driven by rising disposable income and middle-class expansion, as increasing incomes enable consumers to transition from basic personal hygiene products to premium skincare, haircare, and cosmetic formulations. Urban households demonstrate growing willingness to invest in quality beauty products that deliver visible results and align with self-care and wellness priorities, supported by employment growth across service and manufacturing sectors.

One of the leading Mexico beauty and personal care market trends is digital transformation and social commerce growth, as e-commerce platforms and social commerce channels reshape consumer purchasing behaviors. Influencer marketing through Instagram, TikTok, and YouTube significantly impacts product discovery and brand loyalty among millennials and Gen Z consumers. The February 2025 launch of TikTok Shop in Mexico has enabled beauty brands to achieve double-digit sales increases through promotional livestreams and user-generated content strategies.

Another key factor supporting Mexico beauty and personal care market growth is rising demand for clean and sustainable beauty products, as consumers increasingly prioritize natural, organic, and cruelty-free formulations along with recyclable packaging and eco-friendly production methods. In February 2025, Mexican skincare brand Aora partnered with rePurpose Global to launch a plastic-free skincare initiative, becoming certified as a plastic-negative brand using recyclable materials like tin and wood in its packaging.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=22200&flag=C

Mexico Beauty and Personal Care Industry Segmentation Insights

Breakup by Product Type:

  • Skin Care: Dominates the market with a share of 27% in 2025, driven by increasing consumer focus on preventive skincare routines, anti-aging solutions, and growing preference for natural ingredients.
  • Facial Care: Supports targeted treatments addressing specific facial skin concerns and routines.
  • Lip Care: Covers lip balms and treatment products supporting daily personal care needs.
  • Body Care: Includes lotions, creams, and treatments supporting overall skin health and hydration.
  • Foot and Hand Care: Encompasses specialized care products for hands and feet.
  • Oral Care: Supports dental hygiene products used as part of daily grooming routines.
  • Hair Care: Covers shampoos, conditioners, and styling products supporting hair health and grooming.
  • Perfumes and Fragrances: Includes fragrance products supported by strong gifting and personal expression demand.
  • Deodorants: Represents a staple personal care category with consistent daily-use demand.
  • Bath and Shower: Covers cleansing products used in daily hygiene routines.
  • Color Cosmetics: Includes makeup products benefiting from social media trends and beauty influencer culture.

Breakup by Category:

  • Mass: Leads the market with a share of 74% in 2025, owing to widespread accessibility through supermarkets and convenience stores, affordability, and trusted household brands.
  • Premium: Represents a growing segment as consumers increasingly trade up to enhanced formulations and international brands.

Breakup by Distribution Channel:

  • Supermarkets/Hypermarkets: Represents the largest segment with a market share of 37% in 2025, reflecting consumer preference for one-stop shopping and competitive pricing.
  • Specialty/Beauty Stores: Offers curated assortments and personalized service for beauty-conscious consumers.
  • Convenience/Grocery Stores: Provides accessible everyday purchasing options for personal care essentials.
  • Pharmacies/Drugstores: Supports demand for dermatologically tested and health-oriented personal care products.
  • Online Retail Stores: Growing rapidly through e-commerce platforms and social commerce integration.
  • Others: Includes additional retail formats supporting beauty and personal care distribution.

Breakup by Region:

  • Central Mexico: Represents the leading regional market with a 41% share in 2025, anchored by Mexico City’s high-income households and sophisticated retail infrastructure.
  • Northern Mexico: Benefits from strong urbanization and cross-border consumer influences.
  • Southern Mexico: Represents an emerging market with growing beauty consciousness and retail access.
  • Others: Includes additional regional markets contributing to national beauty and personal care demand.

Key Challenges and Growth Opportunities in the Mexico Beauty and Personal Care Market

The Mexico beauty and personal care market faces challenges including the proliferation of counterfeit products and gray market distribution, economic uncertainty and price sensitivity affecting consumer spending, and rising raw material costs alongside evolving regulatory compliance requirements from COFEPRIS.

Despite these challenges, the market offers considerable growth opportunities driven by continued international brand expansion, nearshoring of manufacturing facilities, and growing preference for natural and organic formulations. Expansion of e-commerce, social commerce, and inclusive beauty offerings are expected to create substantial opportunities for long-term growth in the Mexico beauty and personal care market.

Competitive Landscape

The Mexico beauty and personal care market exhibits a moderately concentrated competitive structure featuring established multinational corporations alongside emerging local brands. Major international players leverage global expertise, extensive brand portfolios, and sophisticated distribution networks, while local manufacturers differentiate through culturally relevant formulations, competitive pricing, and deep understanding of regional consumer needs.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
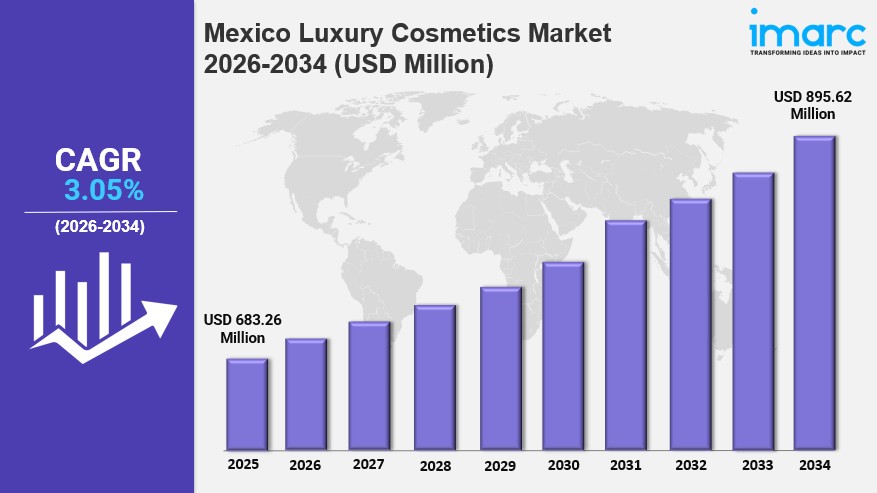
Mexico Luxury Cosmetics Market Size to Hit USD 895.62 Million in 2034 | Grow CAGR by 3.05%

Mexico Luxury Cosmetics Market Size to Hit USD 895.62 Million in 2034 | Grow CAGR by 3.05%

IMARC Group has recently released a new research study titled “Mexico Luxury Cosmetics Market Size, Share, Trends and Forecast by Product Type, Type, Distribution Channel, End User, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Luxury Cosmetics Market Size & Share 2026-2034

The Mexico luxury cosmetics market size reached USD 683.26 Million in 2025 and is projected to reach USD 895.62 Million by 2034, expanding at a CAGR of 3.05% during 2026-2034. The growth of the luxury cosmetics market is driven by rising disposable incomes among affluent Mexican consumers, increasing demand for premium skincare formulations, and growing preference for sustainable and clean beauty products.

Digital transformation through e-commerce platforms and influencer marketing continues to accelerate sales, while consumers seek personalized, high-quality formulations and exclusive brand experiences offered through specialty retail channels, collectively expanding the Mexico luxury cosmetics market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 683.26 Million
  • Projected Market Size (2034): USD 895.62 Million
  • Growth Rate: CAGR of 3.05% (2026-2034)

Explore Opportunities in the Mexico Luxury Cosmetics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-luxury-cosmetics-market/requestsample

Key Growth Drivers and Trends in the Mexico Luxury Cosmetics Market

Growth in the Mexico luxury cosmetics market is being driven by rising affluence and premium consumption patterns, as the expansion of Mexico’s affluent and upper-middle-class population enhances purchasing power for premium beauty products. Consumers are demonstrating a growing preference for quality over quantity, investing in high-end skincare and cosmetics offering superior formulations and brand prestige. In 2025, Maribel Yébenes launched in Mexico at El Palacio de Hierro during the Beauty Festival, hosting a sold-out event introducing its advanced aesthetic and luxury beauty protocols.

One of the leading Mexico luxury cosmetics market trends is digital transformation and omnichannel shopping experiences, as e-commerce platforms equipped with augmented reality try-on tools and AI-powered skincare consultations revolutionize how affluent consumers discover and purchase high-end beauty products. In October 2025, Estée Lauder launched its products on Amazon Premium Beauty in Mexico, expanding nationwide access to prestige skincare, makeup, and fragrance for consumers in urban and remote regions.

Another key factor supporting Mexico luxury cosmetics market growth is rising demand for sustainable and clean beauty formulations, as high-end buyers increasingly seek brands offering eco-friendly packaging, cruelty-free formulations, and naturally derived ingredients, particularly among millennial and Generation Z consumers. In February 2025, Aora MÉXICO partnered with rePurpose Global to become the first luxury beauty brand in Mexico certified Plastic Negative, removing nine times more plastic waste than used.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=31763&flag=C

Mexico Luxury Cosmetics Industry Segmentation Insights

Breakup by Product Type:

  • Skincare: Dominates the market with a share of 37.82% in 2025, driven by growing skin health awareness, anti-aging concerns, demand for dermatology-backed products, and social media-influenced multi-step routines.
  • Haircare: Supports premium hair treatment and styling products catering to beauty-conscious consumers.
  • Makeup: Includes prestige color cosmetics benefiting from social media trends and influencer marketing.
  • Fragrances: Encompasses luxury perfumes and scent products supported by strong brand heritage and gifting demand.

Breakup by Type:

  • Conventional: Leads the market with a share of 70.65% in 2025, owing to established brand trust, wide availability, proven efficacy, and competitive pricing appealing to a broad consumer base.
  • Organic: Growing steadily as consumers increasingly prioritize naturally derived and sustainably sourced formulations.

Breakup by Distribution Channel:

  • Specialty and Monobrand Stores: Represents the largest segment with a market share of 46.51% in 2025, driven by curated assortments, personalized service, expert consultations, and exclusive experiences.
  • Supermarkets and Hypermarkets: Provides broad accessibility for premium beauty products across general retail channels.
  • Online Stores: Growing rapidly through e-commerce platforms offering AR try-on tools and personalized recommendations.
  • Others: Includes travel retail, department stores, and additional distribution formats.

Breakup by End User:

  • Female: Dominates the market with a share of 88.9% in 2025, owing to higher beauty consciousness, extensive skincare and makeup routines, social media trends, and cultural emphasis on personal grooming.
  • Male: Represents a smaller but growing segment as male grooming awareness continues to rise.

Breakup by Region:

  • Central Mexico: Dominates the national luxury cosmetics market, anchored by Mexico City, with the largest consumer base and highest purchasing power concentration.
  • Northern Mexico: Represents a significant market characterized by higher income levels and strong urbanization in cities like Monterrey and Tijuana.
  • Southern Mexico: Presents emerging growth opportunities as regional awareness and purchasing power gradually increase.
  • Others: Includes Pacific Coast, Bajío, and Yucatan Peninsula regions contributing through accelerating urbanization and rising beauty consciousness.

Key Challenges and Growth Opportunities in the Mexico Luxury Cosmetics Market

The Mexico luxury cosmetics market faces challenges including premium price sensitivity amid economic uncertainty, the prevalence of counterfeit products and gray market competition undermining brand integrity, and complex regulatory compliance requirements governing cosmetics registration, labeling, and safety standards.

Despite these challenges, the market offers considerable growth opportunities driven by expanding premium retail infrastructure, rising domestic brand sophistication, and increasing penetration of international luxury brands. Strategic investments in e-commerce capabilities, sustainable product development, and personalized customer experiences are expected to support long-term growth in the Mexico luxury cosmetics market.

Competitive Landscape

The Mexico luxury cosmetics market exhibits a moderately consolidated competitive structure, with established multinational beauty corporations competing alongside premium regional players and emerging domestic brands. Market leaders maintain competitive positioning through extensive distribution networks, substantial marketing investments, continuous product innovation, and strong brand heritage, while premium players differentiate through sustainability, natural ingredients, or dermatological expertise.

Recent Developments in the Mexico Luxury Cosmetics Market

  • May 2025: Charlotte Tilbury entered the Mexico luxury cosmetics market, launching its complete makeup, skincare, and fragrance range in Sephora Mexico, with counters planned at two El Palacio de Hierro stores and a travel retail concession at Mexico City Airport, marking its first Latin American expansion.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302