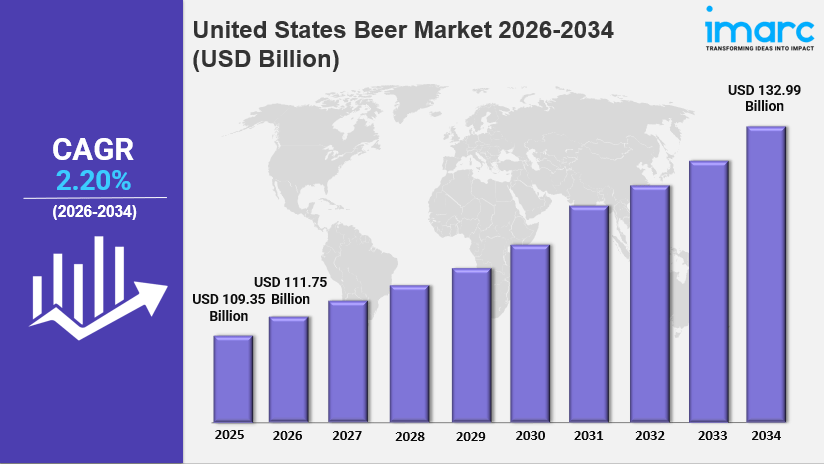
IMARC Group has recently released a report titled “United States Beer Market Size, Share, Trends and Forecast by Product Type, Packaging, Production, Alcohol Content, Flavor, Distribution Channel, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
United States Beer Market Size and Forecast 2026–2034
The United States beer market size increased from USD 109.35 Billion in 2025 to USD 111.75 Billion in 2026 and is projected to reach USD 132.99 Billion by 2034, exhibiting a CAGR of 2.20% during 2026–2034. The market is growing due to changing consumer preferences towards craft and flavored beers, rising disposable incomes, and the proliferation of microbreweries and brewpubs.
In 2026, the United States beer market growth is being supported by premiumization, with consumers trading up to premium lagers, craft IPAs, and imported specialty beers, alongside the mainstreaming of low-alcohol and non-alcoholic variants and the development of direct-to-consumer e-commerce channels. Standard lager dominates the product mix at 46.8% in 2025, glass packaging leads at 41.6%, and the West commands a 29.6% regional share, reflecting California’s craft culture and premium demand.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 109.35 Billion
- Market Size (2026): USD 111.75 Billion
- Projected Size (2034): USD 132.99 Billion
- Growth Rate: CAGR of 2.20%
- Largest Region (2025): West (29.6%)
- Second Region (2025): South (27.8%)
- Leading Product Type (2025): Standard Lager (46.8%)
- Leading Packaging (2025): Glass (41.6%)
Explore Opportunities in the United States Beer Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-beer-market/requestsample
United States Beer Market Growth: Key Trends and Market Insights
The United States beer market growth is supported by the craft beer and premiumization trend, as consumers increasingly prefer unique, locally produced, and artisanal varieties. Over 9,700 craft breweries were operating in the United States, generating sustained demand for specialty and premium segments that command higher retail price points. Beer’s strong association with sports events, concerts, and music festivals, along with the expanding network of microbreweries and brewpubs, continues to drive high-frequency consumption occasions and brewery tourism.
Key United States beer market trends include non-alcoholic beer becoming a mainstream category, as the sober-curious movement and brewing technology advances allow premium positioning; Blue Moon Non-Alcoholic and Heineken 0.0 both entered the top non-alcoholic beverage rankings within their first year of launch. The market is also growing in value terms through premiumization despite volume pressures from health consciousness, while sustainability credentials, such as Molson Coors’ commitment of USD 85 million to eliminate plastic six-pack rings, are becoming a key purchase driver among younger consumers.
The regulatory easing of direct-to-consumer alcohol shipping in over 40 states is opening a new high-margin channel for craft brewers, supported by subscription clubs, limited-edition releases, and digital marketing and loyalty programs. These evolving trends are expected to create opportunities for brewers as revenue mix shifts toward higher-value premium and craft categories through 2034.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=4662&flag=C
United States Beer Market Segmentation Analysis
The United States beer market is segmented by product type, packaging, production, alcohol content, flavor, distribution channel, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.
Breakup by Product Type
- Standard Lager: Leads with a 46.8% share in 2025, owing to widespread appeal, an accessible price point, and the brand strength of Budweiser, Coors Light, and Miller Lite.
- Premium Lager: Holds a 24.6% share in 2025, capturing the premiumization trend as consumers trade up to brands such as Heineken, Corona, and Stella Artois.
- Specialty Beer: Accounts for 20.4% in 2025 and is the fastest-growing product segment (~3.2% CAGR through 2034), driven by craft brewery expansion, IPAs, stouts, and sour ales.
- Others: Represents 8.2% in 2025, including malt beverages and rapidly growing non-alcoholic variants.
Breakup by Packaging
- Glass: Dominates at 41.6% in 2025, preferred for premium, craft, and imported beers where bottle presentation signals quality.
- Metal Can: Holds 34.8% in 2025, supported by sustainability advantages, portability, and growing craft brewery adoption.
- PET Bottle: Accounts for 15.6% in 2025, serving value and convenience segments, with a projected CAGR of ~3.5% through 2034.
- Others: Represents 8.0% in 2025, including kegs and innovative packaging emerging in hospitality channels.
Breakup by Production
- Macro-Brewery: The leading production category in 2025, benefiting from scale, national distribution, and cost efficiency.
- Micro-Brewery: Supported by the craft movement, local loyalty, and taproom and tourism demand.
- Others: Includes brewpubs and other production formats.
Breakup by Alcohol Content
- High: The leading category in 2025, covering traditional-strength beers.
- Low: Growing with health-conscious consumers seeking low-calorie and low-alcohol options.
- Alcohol-Free: A fast-expanding category driven by the sober-curious movement and premium non-alcoholic launches.
Breakup by Flavor
- Unflavored: The leading category in 2025, anchored by traditional lagers and ales.
- Flavored: Benefits from consumer interest in innovation and experimental profiles.
Breakup by Distribution Channel
- Supermarkets and Hypermarkets: The leading channel in 2025, offering broad availability and large-format retail reach.
- On-Trades: Includes bars, restaurants, stadiums, and taprooms, where glass and draft formats are prominent.
- Specialty Stores: Serve craft, import, and premium beer demand.
- Convenience Stores: Provide accessible, high-frequency purchase occasions.
- Others: Includes e-commerce and direct-to-consumer channels.
Breakup by Region
- West: Commands the largest share at 29.6% in 2025, driven by California’s craft breweries, Pacific Northwest premium demand, and Colorado’s craft scene.
- South: Holds 27.8% in 2025, supported by high-volume consumption in Texas, Florida, and Georgia, sports events, and outdoor culture.
- Midwest: Accounts for 23.4% in 2025, anchored by heritage brewing in Chicago, St. Louis, and Milwaukee.
- Northeast: Represents 19.2% in 2025, with premium urban craft demand in New York City and Boston.
Key Challenges and Growth Opportunities in the United States Beer Market
The United States beer market faces several challenges that could affect its growth, including a health consciousness and moderation trend among Millennials and Gen Z that pressures mainstream standard lager volumes, competition from wine, spirits, hard seltzers, and ready-to-drink cocktails, and commodity input cost volatility across barley, hops, aluminum, and glass. The three-tier distribution system and varying state alcohol laws also create compliance complexity, particularly for small craft producers.
Despite these challenges, the market offers significant growth opportunities driven by the mainstreaming of non-alcoholic beer, direct-to-consumer e-commerce channels, and continued premiumization and craft beer innovation. Brewers investing in premium portfolios, zero-alcohol variants, sustainable packaging, and digital engagement will be well positioned to strengthen their competitive advantage through 2034.
Competitive Landscape
The United States beer market is moderately concentrated, with Anheuser-Busch InBev and Molson Coors commanding a combined estimated 60–65% volume share, while Constellation Brands leads the premium import segment. Key players include Anheuser-Busch InBev, Molson Coors Beverage Company, Constellation Brands, Boston Beer Company, Heineken USA, Pabst Brewing Company, and Diageo Beer Company USA. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.
Market participants are investing in premium and craft portfolios, non-alcoholic offerings, sustainability initiatives, and digital distribution platforms. Modelo Especial overtook Bud Light as the top-selling U.S. beer brand by dollar value in 2023, underscoring Constellation’s premium import strength, while consolidation through craft acquisitions continues to reshape the competitive structure.
Latest News and Developments
- March 2026: Constellation Brands entered into an agreement to acquire the remaining stake in HOPWTR, a fast-growing premium non-alcoholic beverage brand, taking full ownership after its initial investment in 2021.
- May 2025: Anheuser-Busch announced a USD 300 million investment to expand and modernize its manufacturing operations across the United States, focusing on facility upgrades, technology, and workforce development.
- March 2022: Molson Coors committed USD 85 million to eliminate plastic six-pack rings from its North American brands by the end of 2025.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

