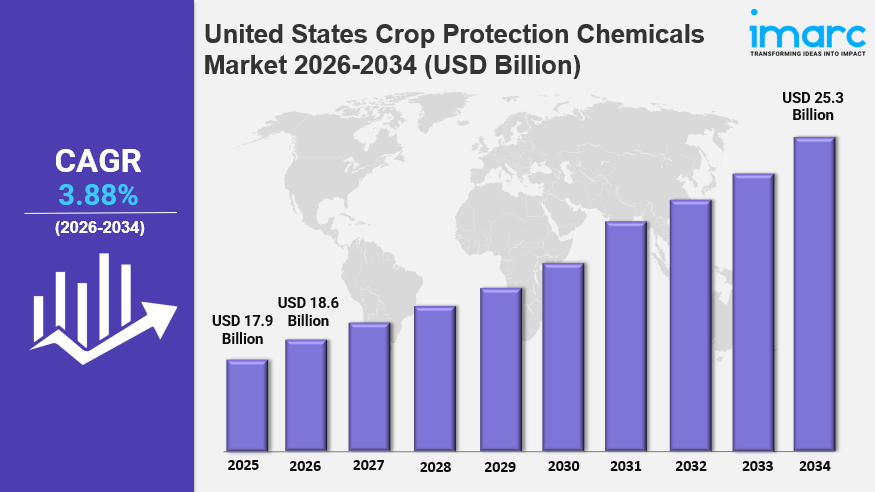
IMARC Group has recently released a report titled “United States Crop Protection Chemicals Market Size, Share, Trends, and Forecast by Type, Origin, Application, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
United States Crop Protection Chemicals Market Size and Forecast 2026–2034
The United States crop protection chemicals market size grew from USD 17.9 Billion in 2025 to USD 18.6 Billion in 2026, and is projected to reach USD 25.3 Billion by 2034, exhibiting a CAGR of 3.88% during 2026–2034. The United States crop protection chemicals market share is led by the Midwest, which held a significant share in 2025. Growth is being driven by increasing agricultural productivity, advanced farming practices, genetically modified crops, rising pest resistance, and climate variability.
Market expansion is further supported by growing food demand associated with population growth, encouraging farmers to increase their use of herbicides, insecticides, and fungicides. The adoption of precision agriculture, including GPS-guided equipment and remote sensing, enables more targeted chemical application. Meanwhile, genetically modified corn, soybean, and cotton varieties, alongside regulatory and R&D investments in lower-toxicity formulations, are reinforcing long-term market growth through 2034.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 17.9 Billion
- Market Size (2026): USD 18.6 Billion
- Projected Size (2034): USD 25.3 Billion
- Growth Rate: CAGR of 3.88%
Explore Opportunities in the United States Crop Protection Chemicals Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-crop-protection-chemicals-market/requestsample
United States Crop Protection Chemicals Market Growth: Key Trends and Market Insights
The United States crop protection chemicals market trends are increasingly influenced by population growth, precision agriculture adoption, and technological innovation. Rising food demand is encouraging farmers to improve crop yields and protect harvests from pests, diseases, and weeds, supporting consistent demand for crop protection solutions.
The United States crop protection chemicals market growth is also being supported by the expanding adoption of precision farming technologies, including GPS mapping, drone-based spraying, and variable-rate application. These technologies enable farmers to apply crop protection inputs more efficiently while reducing waste and improving productivity.
Continued innovation is further strengthening market expansion, with manufacturers and regulators focusing on effective, environmentally responsible formulations. The development of broad-spectrum and resistance-management solutions is supporting improved efficacy, safety, and sustainability while helping the industry respond to evolving agricultural and environmental requirements.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20483&flag=C
United States Crop Protection Chemicals Market Segmentation Analysis
The United States crop protection chemicals market is segmented by type, origin, application, and region, offering a comprehensive view of demand drivers, product preferences, and regional dynamics across the country.
Breakup by Type
- Herbicides: Hold the leading share at 43.7% in 2025, supported by the vast scale of commercial farming and the high prevalence of weed-related crop loss, reinforced by wider adoption of herbicide-tolerant GM crops.
- Insecticides: Remain essential for managing recurring pest pressure across major row crops, particularly as unpredictable weather patterns raise the risk of pest outbreaks.
- Fungicides: Continue to gain traction as growers seek protection against foliar and soil-borne diseases that threaten yield and quality.
- Others: Include nematicides, rodenticides, and plant growth regulators used in targeted crop-protection programs.
Breakup by Origin
- Synthetic: Leads the market with a 78.3% share in 2025, owing to its proven effectiveness, broad-spectrum action, cost-efficiency, and compatibility with genetically modified crop varieties.
- Bio-based: Gaining ground as growers and regulators favor lower-toxicity, environmentally responsible alternatives alongside conventional chemistries.
Breakup by Application
- Grains and Cereals: Lead the market with a 38.9% share in 2025, reflecting the vast cultivation area and critical role of corn, wheat, and rice in domestic consumption, animal feed, and exports.
- Pulse and Oilseeds: Benefit from steady demand for protein and oil crops requiring consistent pest and disease management.
- Fruits and Vegetables: See growing chemical usage tied to quality-sensitive, high-value horticultural production.
- Commercial Crops: Cotton and other cash crops continue to drive targeted herbicide and insecticide demand.
- Others: Cover turf, ornamentals, and additional specialty applications.
Breakup by Region
- Midwest: Dominates the market, underpinned by large-scale corn, soybean, and wheat cultivation, widespread adoption of GM seeds, and strong uptake of precision farming technologies.
- South: Supported by diverse cropping patterns and sustained demand for pest and weed management across row and specialty crops.
- West: Driven by high-value fruit, vegetable, and nut production requiring intensive crop protection.
- Northeast: A smaller but steady contributor, supported by diversified and specialty agriculture.
Key Challenges and Growth Opportunities in the United States Crop Protection Chemicals Market
The market faces challenges including tightening regulatory scrutiny from the EPA, growing resistance among target weeds and pests that reduces the efficacy of established chemistries, and the need to balance high-performance synthetic solutions with rising demand for sustainable, lower-toxicity alternatives.
Despite these challenges, the market offers significant growth opportunities driven by rising food demand, expanding precision agriculture adoption, and continued investment in R&D for resistance-management and eco-friendly formulations. Companies pursuing agri-tech partnerships, digital integration, and biological product pipelines are well positioned to strengthen their competitive position through 2034.
Competitive Landscape
The United States crop protection chemicals market is highly competitive, with major companies such as Bayer AG, Corteva Agriscience, Syngenta AG, BASF SE, and FMC Corporation dominating through extensive product portfolios and nationwide distribution networks. Leading players are investing heavily in R&D to develop eco-friendly and resistance-management solutions, including biologicals and precision-targeted chemicals, while pursuing mergers, acquisitions, and agri-tech collaborations to enhance digital integration and application efficiency. Regional players and startups are also emerging in niche segments such as biopesticides, as evolving EPA standards continue to shape competitive dynamics. The report provides a comprehensive analysis of the competitive landscape, including detailed company profiles and Porter’s Five Forces analysis.
Latest News and Developments
- June 2025: Corteva confirmed the release of its Forcivo fungicide, combining three active ingredients to combat foliar diseases such as tar spot and southern rust in corn and soybeans, pending EPA registration.
- May 2025: ADAMA Ltd. secured US registration for Temper More, a herbicide built on its proprietary formulation technology aimed at controlling herbicide-resistant weeds.
- April 2025: Syngenta disclosed three new foliar-applied insecticide products — Incipio, Vertento, and Zivalgo — for in-season insect control, pending EPA approval.
- March 2025: ADAMA US introduced Maxentis SC, a dual-active fungicide for maize, soybean, and wheat growers targeting major crop diseases.
- January 2025: FMC launched two new herbicides, Keenali Complete and Keenali GR, powered by its Dodylex active ingredient, with staggered rollout for rice growers through 2028.
Author: IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

