IMARC Group has recently released a report titled “United States Olive Oil Market Size, Share, Trends and Forecast by Type, Distribution Channel, Application, and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
United States Olive Oil Market Size and Forecast 2026–2034
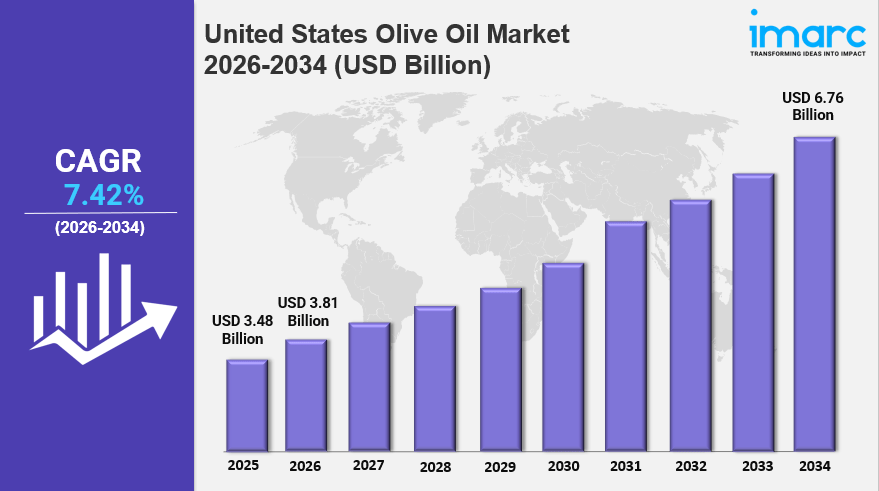
The United States olive oil market size increased from USD 3.48 Billion in 2025 to USD 3.81 Billion in 2026, and is projected to reach USD 6.76 Billion by 2034, growing at a CAGR of 7.42% during 2026–2034. Rising health consciousness among consumers, the surging popularity of the Mediterranean diet, and expanding applications of olive oil across food, cosmetics, and pharmaceutical sectors are key growth drivers.
The United States olive oil market share is led by the West region, which accounted for 34.2% in 2025, while extra virgin olive oil represented 48.7% of type demand. The food and beverage segment dominated applications with a 76.5% share. Growing premiumization, demand for authentic Mediterranean and single-origin varieties, and increasing domestic production in California are further supporting market expansion.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 3.48 Billion
- Market Size (2026): USD 3.81 Billion
- Projected Size (2034): USD 6.76 Billion
- Growth Rate: CAGR of 7.42%
Explore Opportunities in the United States Olive Oil Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-olive-oil-market/requestsample
United States Olive Oil Market Overview
Olive oil is a premium edible oil extracted from fresh olives, predominantly imported from Mediterranean countries including Spain, Italy, Greece, and Tunisia, with at least 97% of the US supply derived from imports. The market ecosystem spans producers and exporters in Mediterranean growing regions, import distributors, domestic California producers, food manufacturers, and retail and foodservice channels serving household, commercial, cosmetic, and pharmaceutical applications. Rising per-capita health expenditure, growing awareness of cardiovascular disease prevention, and the mainstreaming of the Mediterranean dietary pattern are primary growth catalysts, with the US having overtaken Spain to become the world’s second-largest olive oil consumer for the first time in 2023.
Market Drivers
- Rising Health Consciousness: Olive oil’s documented cardiovascular benefits are driving consistent consumer trading-up from conventional cooking oils, with a large majority of Americans expecting to cook as much or more in the year ahead, sustaining retail demand for premium varieties.
- Mediterranean Diet Popularity: Endorsed by leading nutrition organizations and consistently ranked among the healthiest dietary patterns, the Mediterranean diet has elevated olive oil from a specialty product to a household staple across income brackets.
- Expanding Foodservice Sector: Foodservice and restaurant channels account for roughly 40% of bulk olive oil purchases in the US, with major chains reformulating menus around olive oil as a core cooking ingredient.
- E-Commerce Growth: Online retail is expanding rapidly as a distribution channel for premium olive oil, giving consumers access to specialty, organic, and single-origin varieties not typically stocked by conventional supermarkets.
United States Olive Oil Market Growth: Key Trends and Market Insights
The United States olive oil market growth is being supported by increasing consumer awareness of healthy dietary choices and the nutritional benefits associated with olive oil. Consumers are increasingly incorporating olive oil into everyday cooking, salad dressings, marinades, and other food preparations as interest in heart-healthy and natural ingredients continues to rise. Growing awareness of Mediterranean dietary patterns is also encouraging demand for high-quality olive oil, particularly among health-conscious consumers seeking products perceived as natural, minimally processed, and rich in beneficial compounds.
The United States olive oil market trends are increasingly characterized by premiumization and rising consumer preference for extra virgin olive oil. Consumers are showing greater interest in authentic Mediterranean products, single-origin varieties, traceability, quality certifications, and distinctive flavor profiles. Extra virgin olive oil accounted for 48.7% of type demand in 2025, reflecting its strong position within the market. The food and beverage segment also remained the leading application, accounting for 76.5% share, supported by the widespread use of olive oil across households, restaurants, food manufacturers, and other foodservice establishments.
Another important factor supporting market development is the expansion of domestic olive oil production, particularly in California, alongside increasing availability of imported premium products. The West region led the market with a 34.2% share in 2025, benefiting from established production capabilities and strong consumer demand. Rising consumption, product diversification, premium offerings, and growing interest in authentic and single-origin oils are expected to create further opportunities for producers, retailers, and foodservice businesses across the United States.
United States Olive Oil Market Segmentation Analysis
The United States olive oil market is segmented by type, distribution channel, application, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.
Breakup by Type
- Extra Virgin Olive Oil: Leads the market with a 48.7% share in 2025 and the fastest growth at an 8.8% CAGR, reflecting premium positioning driven by superior nutritional composition, higher polyphenol content, and authentic flavor.
- Virgin Olive Oil: Holds an 18.9% share, valued for its purity and cold-press processing without chemical refinement, suited to moderate-temperature cooking and finishing dishes.
- Refined Olive Oil: Accounts for 14.6% of the market, primarily serving food manufacturing and commercial foodservice where a neutral flavor and higher smoke point are preferred.
- Olive Pomace Oil and Others: Round out the type segment, serving industrial and value-focused cooking applications.
Breakup by Application
- Food and Beverage: Dominates with a 76.5% share in 2025, spanning household retail cooking oil, restaurant and foodservice use, food manufacturing for dressings and marinades, and snack production.
- Cosmetics: Accounts for 11.8% of demand, reflecting olive oil’s growing use in premium skincare, hair care, and beauty formulations valued for emollient and antioxidant properties.
- Pharmaceuticals: Holds a 7.9% share, growing as olive oil is increasingly incorporated into supplement formulations, topical products, and pharmaceutical-grade excipients.
- Others: Cover additional industrial and specialty uses of olive oil.
Breakup by Distribution Channel
- Supermarkets and Hypermarkets: Remain the primary channel for mainstream olive oil purchases, offering broad accessibility and everyday convenience.
- Online Stores: A fast-growing channel enabling access to specialty, organic, and single-origin varieties through curated digital platforms and subscriptions.
- Convenience Stores and Others: Support broader distribution reach, particularly for everyday and value-tier products.
Breakup by Region
- West – 34.2%: Led by California’s domestic production, high per-capita consumption, and strong demand for organic and specialty olive oils.
- Northeast – 25.6%: Supported by urban gourmet food culture, specialty retailers, EVOO demand, and Mediterranean restaurant presence.
- South – 22.4%: Experiencing strong consumption growth, expanding Mediterranean cuisine, and well-developed Gulf Coast import networks.
- Midwest – 17.8%: Showing rapid growth through supermarket distribution, increasing availability, and rising private-label olive oil adoption.
Competitive Landscape
The United States olive oil market is moderately fragmented, with the top five players — Deoleo, Gallo Worldwide, Cargill Incorporated, Ybarra, SOVENA, and California Olive Ranch, Inc. — collectively holding approximately 40–50% of total market revenue in 2025. Deoleo leads the market through its Bertolli, Carbonell, and Carapelli brands, maintaining a steady market share through its Mediterranean sourcing network. Gallo Worldwide focuses on premium and organic EVOO positioning, while Cargill leverages its agricultural commodity scale to supply refined and bulk olive oil to food manufacturers and foodservice operators. California Olive Ranch continues to build market share through domestic production, freshness positioning, and traceability. A diverse mix of Mediterranean export brands, California producers, specialty importers, and private-label retailers accounts for the remaining share, sustaining a competitive landscape that rewards both scale and quality differentiation. The report provides a comprehensive analysis of the competitive landscape, including detailed profiles of all major companies operating in the market.
Author: IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

