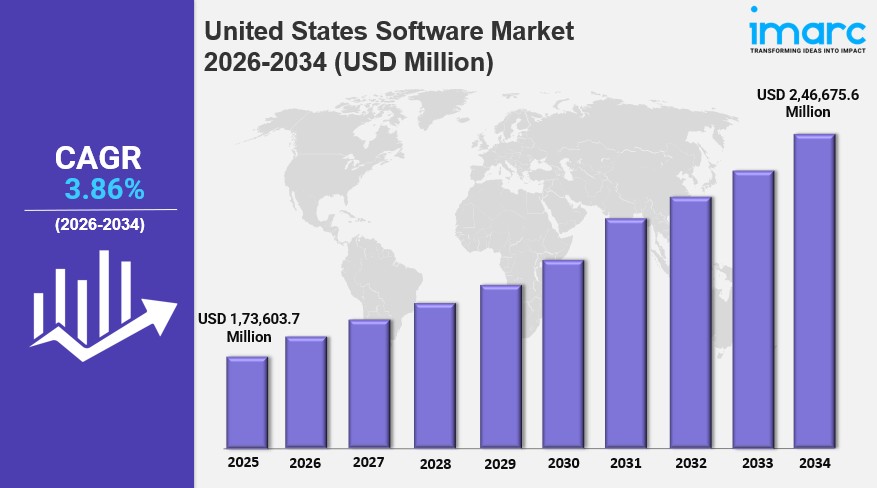
IMARC Group has recently released a new research study titled “United States Software Market Report by Type (Application Software, System Infrastructure Software, Development and Deployment Software, Productivity Software), Deployment Mode (On-premises, Cloud-based), Enterprise Size (Small and Medium-sized Enterprises, Large Enterprises), Industry Vertical (IT and Telecom, BFSI, Retail, Government/Public Sector, Energy and Utilities, Healthcare, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
United States Software Market Size & Share 2026-2034
The United States software market size reached USD 1,73,603.7 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 2,46,675.6 Million by 2034, exhibiting a growth rate (CAGR) of 3.86% during 2026–2034. The growing demand in remote healthcare, patient management, and medical data analysis, increasing shift from on-premises software solutions to cloud-based services, and rising popularity of low-code and no-code development platforms represent some of the key factors driving the market.
The industry is further fueled by digital transformation, cloud computing adoption, increasing demand for automation, and artificial intelligence investment, which together drive enterprise modernization and underpin growth in scalable, intelligent technology infrastructures.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Base Year Market Size (2025): USD 173,603.7 Million
- Forecast Market Size (2034): USD 246,675.6 Million
- Growth Rate: CAGR of 3.86% (2026-2034)
Explore Opportunities in the United States Software Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-software-market/requestsample
Key Growth Drivers and Trends in the United States Software Market
Growth in the United States software market is being driven by the rapid and swift uptake of cloud-native software architecture, which is reshaping the software development environment as technologies such as containerization, microservices, and serverless computing allow companies to develop scalable and elastic applications optimized for fast-changing environments. Organizations across industries are increasingly betting on platforms that can deploy, observe, and manage workloads in real-time efficiently, with software vendors concentrating on providing cloud-first offerings that reflect the agile and dispersed nature of current IT infrastructures.
One of the leading United States software market trends is the incorporation of artificial intelligence within mainstream software platforms, remaking user experience, decision-making, and operational capabilities. AI-based software products, ranging from predictive analytics to natural language processing and machine learning, are increasingly integrated into enterprise applications to maximize performance and provide intelligent automation, most notably in industries such as healthcare, finance, and logistics. In May 2025, OpenAI released a research preview of Codex, an AI software engineering agent capable of writing code, debugging, running tests, and answering questions, with plans to revolutionize enterprise-scale software development processes.
Another key factor supporting market growth is the increased focus on software compliance and security, as developers and businesses integrate security protocols and compliance models natively into the software development lifecycle through DevSecOps to enable proactive risk management. This responds to both internal data governance needs and external regulatory compliance requirements including GDPR, HIPAA, and CCPA, with companies increasingly adopting security-oriented software applications to uphold user trust and prevent financial fines.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=19069&flag=C
United States Software Industry Segmentation Insights
Breakup by Type:
- Application Software: Covers ERP, CRM, SCM, enterprise collaboration, enterprise content management, education software, and other business applications.
- System Infrastructure Software: Includes network management systems, storage software, and security software supporting core IT operations.
- Development and Deployment Software: Encompasses enterprise data management, business analytics and reporting tools, application servers, integration middleware, and data quality tools.
- Productivity Software: Includes office software, creative software, and other tools supporting individual and team productivity.
Breakup by Deployment Mode:
- On-premises: Serves organizations requiring direct infrastructure control and data residency compliance.
- Cloud-based: Gaining wider adoption due to scalability, remote accessibility, and reduced infrastructure overhead.
Breakup by Enterprise Size:
- Small and Medium-sized Enterprises: Increasingly adopting cloud-based and subscription software models to access enterprise-grade capabilities cost-effectively.
- Large Enterprises: Drives substantial software investment across complex, multi-department digital transformation initiatives.
Breakup by Industry Vertical:
- IT and Telecom: A leading vertical driving continuous software innovation and infrastructure modernization.
- BFSI: Adopts software extensively for digital banking, risk management, and regulatory compliance.
- Retail: Utilizes software for e-commerce, inventory management, and customer experience platforms.
- Government/Public Sector: Invests in software for citizen services, data management, and cybersecurity infrastructure.
- Energy and Utilities: Applies software for grid management, asset monitoring, and operational efficiency.
- Healthcare: Growing rapidly with demand in remote healthcare, patient management, and medical data analysis software.
- Others: Includes additional industry verticals adopting software solutions across diverse use cases.
Breakup by Region:
- Northeast: Supported by dense concentrations of financial services and enterprise software adoption.
- Midwest: Benefits from steady industrial and manufacturing software demand.
- South: A growing region supported by expanding technology hubs and business relocation trends.
- West: Leads with concentration of major technology companies and software innovation centers.
Key Challenges and Growth Opportunities in the United States Software Market
The United States software market faces challenges including ongoing data privacy issues, complex regulatory requirements, and persistent cybersecurity attacks that require continuous investment in secure software development practices.
Despite these challenges, the market offers considerable growth opportunities driven by pressure to move toward intelligent automation, edge computing, and vertical-specific SaaS solutions. Continued expansion of cloud-native architectures, AI-infused capabilities, and platform-as-a-service models is expected to support long-term growth in the United States software market.
Competitive Landscape
The United States software market is highly competitive among international and national vendors, with differentiation based on innovation velocity, integration expertise, cybersecurity level, and industry-specific tailoring to address a wide range of enterprise needs. Companies are investing heavily in AI-infused capabilities, cloud-native architectures, and compliance-focused offerings to differentiate their solutions across the enterprise software landscape.
Recent Developments in the United States Software Market
- May 2025: OpenAI released a research preview of Codex, an AI software engineering agent capable of writing code, debugging, running tests, and answering questions, built on the codex-1 model and made available to ChatGPT Pro, Team, and Enterprise customers.
- March 2025: OneTrust launched an AI-driven Privacy Breach Response Agent designed with Microsoft Security Copilot, automating data analysis, regulatory mapping, and compliance measures to boost organizational efficiency in handling privacy incidents.
- July 2025: Rune Technologies debuted its AI-fueled military logistics platform, TyrOS, and raised $24 million in Series A funding, with the edge-deployed platform using deep learning to optimize supply chains, with pilot programs underway in the U.S. Army and Marine Corps.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
 Market Outlook
