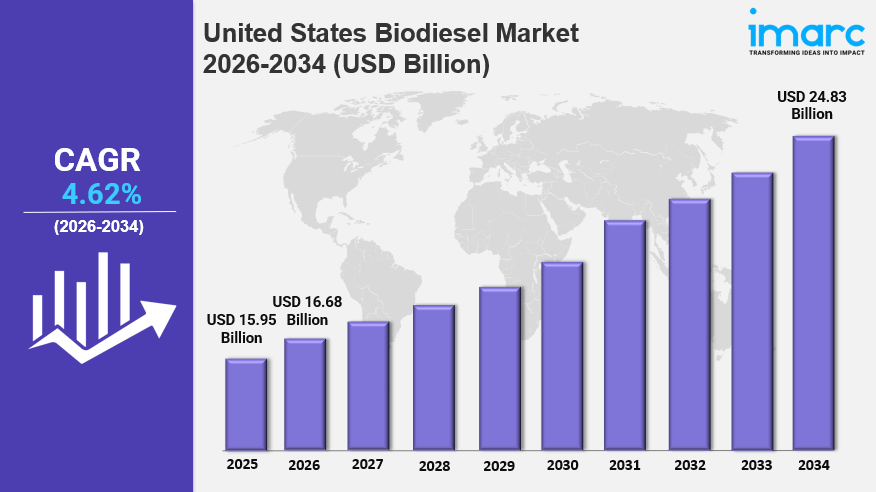
IMARC Group has recently released a report titled “United States Biodiesel Market Size, Share, Trends and Forecast by Feedstock, Application, Type, Production Technology, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
United States Biodiesel Market Size and Forecast 2026–2034
The United States biodiesel market size increased from USD 15.95 Billion in 2025 to USD 16.68 Billion in 2026 and is projected to reach USD 24.83 Billion by 2034, exhibiting a CAGR of 4.62% during 2026–2034. The market is growing due to strong support from the federal Renewable Fuel Standard (RFS), abundant domestic soybean oil supply, and rising fleet decarbonization efforts. Expanding renewable diesel capacity and low-carbon fuel standard incentives are further strengthening the market outlook.
In 2026, the United States biodiesel market growth is being driven by the Environmental Protection Agency’s proposed biomass-based diesel volume of 5.61 Billion gallons for 2026, the Section 45Z Clean Fuel Production Credit, which took effect in January 2025 and has been extended through 2029, and the expansion of state low-carbon fuel programs, including New Mexico’s Clean Transportation Fuel Program, which began implementation in April 2026. Rising adoption of B5 to B20 blends among trucking and municipal fleets, along with growing use in standby and backup power, is further broadening demand. After growing from USD 12.72 Billion in 2020, the market is expected to reach approximately USD 19.98 Billion by 2030.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 15.95 Billion
- Market Size (2026): USD 16.68 Billion
- Projected Size (2034): USD 24.83 Billion
- Growth Rate: CAGR of 4.62%
Explore Opportunities in the United States Biodiesel Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-biodiesel-market/requestsample
United States Biodiesel Market Growth: Key Trends and Market Insights
The United States biodiesel market growth is supported by biodiesel’s shift from a niche additive to a core compliance fuel blended into the national diesel pool under the RFS. Falling soybean oil prices, fleet sustainability targets, and tightening biomass-based diesel obligations are lifting blending volumes, while state low-carbon fuel programs reinforce demand across on-road, off-road, and stationary applications. According to the U.S. Energy Information Administration, biodiesel and renewable diesel together met about 9% of on-road diesel demand in 2024.
Key United States biodiesel market trends include a shift toward lower-carbon-intensity feedstocks such as used cooking oil, distillers corn oil, and tallow, which earn higher Section 45Z and Low Carbon Fuel Standard (LCFS) credit values, the co-location of new projects with expanded soybean crushing capacity across Iowa, North Dakota, and the Mid-South, and the convergence of biodiesel with renewable diesel and sustainable aviation fuel (SAF) at multi-product biorefineries. Producers are also adopting continuous-flow reactors, solid catalysts, advanced feedstock pretreatment, and digital traceability platforms to improve yields and meet 45Z and LCFS reporting requirements.
Large logistics operators and municipal fleets are embedding B20 to B100 blends into ESG reporting and signing multi-year supply agreements, strengthening long-term offtake visibility. Vegetable oils, fuel, and the West region are expected to expand faster than the overall market through 2034, supported by soybean processing capacity and B20 fleet adoption, while the Midwest is projected to be the fastest-growing region.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2722&flag=C
United States Biodiesel Market Segmentation Analysis
The United States biodiesel market is segmented by feedstock, application, type, production technology, and region, offering a comprehensive view of feedstock sourcing, end-use demand, blending patterns, and regional dynamics across the country.
Breakup by Feedstock
- Vegetable Oils: Leads with a 47.6% share in 2025, anchored by domestic soybean crushing infrastructure and abundant soybean oil supply.
- Animal Fats: Holds a 32.4% share, covering tallow, choice white grease, poultry fat, and yellow grease from meatpacking and food service, which earn lower carbon-intensity scores.
- Others: Accounts for the remaining 20.0%, including used cooking oil, distillers corn oil, and other waste-derived feedstocks.
Breakup by Application
- Fuel: Dominates with a 68.3% share in 2025, driven by compliance blending into the on-road diesel pool and adoption of B5 to B20 blends across trucking and municipal fleets.
- Power Generation: Holds an 18.7% share, concentrated in standby generators, data center backup, microgrids, and remote off-grid power.
- Others: Represents the remaining 13.0%, including marine, rail, agricultural, and home-heating uses.
Breakup by Type
- B100: Pure biodiesel, whose use is limited in northern winter conditions by higher cloud and pour points compared with petroleum diesel.
- B20: The leading type in 2025, widely adopted by fleets to reduce scope-1 emissions without engine modifications.
- B10: A lower blend supporting broad compatibility with existing diesel engines and fuel infrastructure.
- B5: The lowest blend level, widely used for routine compliance blending into the diesel pool.
Breakup by Production Technology
- Conventional Alcohol Trans-Esterification: The leading production technology in 2025, converting vegetable oils, animal fats, and recycled cooking oils with methanol and a catalyst into methyl esters and glycerin.
- Pyrolysis: An alternative thermal conversion pathway covered within the report.
- Hydro Heating: An alternative hydro-based conversion pathway covered within the report.
Breakup by Region
- West: Commands the leading market share of 34.2% in 2025, driven by premium credit pricing under California’s LCFS, active programs in Oregon and Washington, and strong fleet decarbonization commitments.
- Midwest: Holds a 27.8% share and is the fastest-growing region through 2034, supported by proximity to soybean crushing and animal-fat rendering capacity and dense biorefinery clusters in Iowa, Minnesota, Missouri, and Illinois.
- South: Accounts for 22.6% of the market, supported by expanding soybean processing investments, growing trucking demand, and port-based export options.
- Northeast: Holds a 15.4% share, supported by Bioheat home-heating-oil mandates, urban municipal fleet adoption, and developing state low-carbon fuel programs.
Key Challenges and Growth Opportunities in the United States Biodiesel Market
The United States biodiesel market faces several challenges that could affect its growth, including high feedstock cost volatility that can compress producer margins, competition from renewable diesel for the same fats and oils feedstocks, the lapse of the legacy USD 1 per gallon blender tax credit at the end of 2024, RIN price volatility and regulatory uncertainty, and cold-weather performance constraints that limit high-blend use in northern climates.
Despite these challenges, the market offers significant growth opportunities driven by waste and used cooking oil pathways that earn premium low-carbon pricing, co-production of sustainable aviation fuel, continued benefits from the Section 45Z production credit, and the expansion of state low-carbon fuel programs. Under-penetrated applications such as Bioheat in the Northeast, off-road agriculture and construction equipment, marine bunker fuel, and rail switching are expected to open additional demand pools. Vertically integrated operators and waste-feedstock specialists are best positioned to capture the largest share of value through 2034.
Competitive Landscape
The United States biodiesel market is moderately fragmented, with a handful of large vertically integrated producers operating at national scale alongside numerous regional and specialty producers. Key companies operating in the market include Chevron Corporation, ADM, Louis Dreyfus Company, Cargill, Incorporated, and Western Iowa Energy, LLC. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.
Feedstock procurement depth, biorefinery scale, and LCFS pathway approvals form the primary competitive advantages, with the top five producers estimated to hold approximately 50–60% of operating capacity in 2025. Barriers to entry include EPA RFS producer registration and access to long-term feedstock contracts, while consolidation is being driven by capital intensity and the shift toward renewable diesel and SAF co-production.
Latest News and Developments
- April 2026: New Mexico began implementing its Clean Transportation Fuel Program, a low-carbon fuel standard aimed at reducing road fuel carbon intensity by 20% within this decade, marking the first such initiative beyond the West Coast.
- August 2025: Chevron confirmed that its Geismar, Louisiana renewable fuels plant began production following an expansion that raised capacity from 7,000 to 22,000 barrels per day, lifting annual renewable diesel output from approximately 90 Million gallons to 340 Million gallons.
- June 2025: Louis Dreyfus Company announced plans to reopen its Burns Harbor grain export facility in Portage, Indiana, supporting feedstock and origination flows for its Claypool, Indiana biodiesel plant.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

