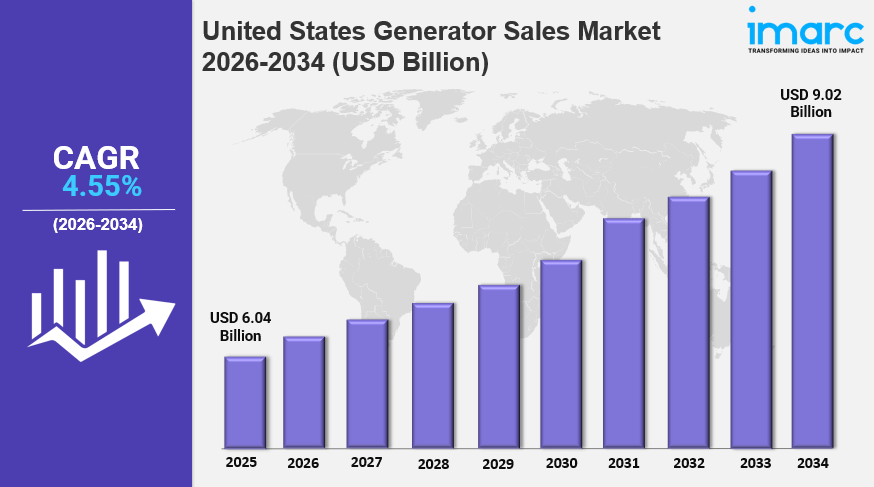
IMARC Group has recently released a new research study titled “United States Generator Sales Market Size, Share, Trends and Forecast by Power Rating, Fuel Type, Application, End Use Industry, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
United States Generator Sales Market Size & Share 2026-2034
The United States generator sales market size reached USD 6.04 Billion in 2025 and is projected to reach USD 9.02 Billion by 2034, expanding at a CAGR of 4.55% during 2026-2034. In 2026, the market continues to gain momentum, driven by the increasing frequency and severity of power outages caused by extreme weather events, aging grid infrastructure requiring reliable backup solutions, and rapid industrialization across key sectors.
Growth in 2026 is further reinforced by rising electricity demand from data centers, commercial establishments, and industrial facilities, along with technological advancements in generator efficiency and the expansion of the construction sector. These dynamics are expected to strengthen the United States generator sales market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 6.04 Billion
- Projected Market Size (2034): USD 9.02 Billion
- Growth Rate: CAGR of 4.55% (2026-2034)
- Leading Power Rating: Above 750 kVA (34% share in 2025)
- Leading Fuel Type: Diesel (60% share in 2025)
- Leading Application: Standby Load (41% share in 2025)
- Leading End Use Industry: Industrial (39% share in 2025)
- Leading Region: South (32% share in 2025)
Explore Opportunities in the United States Generator Sales Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-generator-sales-market/requestsample
Key Growth Drivers and Trends in the United States Generator Sales Market
Growth in the United States generator sales market is being driven primarily by the increasing frequency and severity of power outages from extreme weather events such as hurricanes, wildfires, ice storms, and heatwaves. According to reports, the average longest U.S. power outage increased from 8.1 hours in 2022 to 12.8 hours by mid-2025, compelling residential, commercial, and industrial users to invest in reliable backup power.
One of the leading United States generator sales market trends is the aging electrical grid, with substantial portions of transmission lines and transformers approaching or exceeding their intended operational lifespans. In 2025, Avangrid announced a USD 20 Billion plan to modernize and expand U.S. grid infrastructure through 2030. The rapid expansion of AI-driven data centers is also adding to electricity demand and accelerating the adoption of generators for both primary and backup power. In April 2025, Generac launched five new high-capacity standby generators (2.25 to 3.25 MW) for hyperscale, colocation, enterprise, and edge data centers, and in January 2026 it acquired a new facility in Sussex, Wisconsin, to expand manufacturing of commercial and industrial generators.
Another key factor supporting United States generator sales market growth is the integration of smart technologies and the rise of hybrid systems. Modern generators increasingly feature IoT-enabled sensors and connectivity for real-time monitoring, remote diagnostics, and predictive maintenance, as seen in Generac’s Mobile Link app for home standby generators. Hybrid generator systems that combine conventional fuel with renewable energy and battery storage are also gaining traction; Aggreko’s natural gas battery system in the Permian Basin reduced generator running times from 167 to 6 hours and lowered fuel expenses by as much as 96%.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21137&flag=C
United States Generator Sales Industry Segmentation Insights
Breakup by Power Rating:
- Below 75 kVA: Smaller generators used for residential, small commercial, and portable applications.
- 75-375 kVA: Mid-range generators used for commercial buildings and light industrial applications.
- 375-750 kVA: Higher-capacity generators used for larger commercial and industrial facilities.
- Above 750 kVA: The leading segment with a 34% share in 2025, driven by heavy industrial applications, large-scale manufacturing facilities, and hyperscale data centers requiring megawatt-level backup power.
Breakup by Fuel Type:
- Diesel: The leading segment with a 60% share in 2025, owing to its reliability, high power density, wide availability, and proven performance in critical applications across industrial and commercial sectors.
- Gas: Natural gas and other gas-fueled generators, including mobile units suited to oil, gas, and remote applications.
- Others: Includes other fuel types and hybrid configurations.
Breakup by Application:
- Continuous Load: Generators that supply continuous primary power to facilities and sites.
- Peak Load: Generators used to meet peak demand and supplement grid supply.
- Standby Load: The leading segment with a 41% share in 2025, driven by emergency power supply needs in healthcare organizations, data centers, and telecom operations.
Breakup by End Use Industry:
- Industrial: The leading segment with a 39% share in 2025, covering utilities/power generation, oil and gas, chemicals and petrochemicals, mining and metals, manufacturing, marine, construction, and others.
- Commercial: Covers IT and telecom, healthcare, data centers, and others, where uninterrupted power is critical to operations.
- Residential: Home standby and portable generators, with growing adoption in regions prone to extended outages.
Breakup by Region:
- Northeast: One of the major regional markets analyzed in the report.
- Midwest: One of the major regional markets analyzed in the report.
- South: The leading region with a 32% share in 2025, supported by hurricane exposure along the Gulf Coast and Atlantic seaboard, a concentrated oil and gas industry, expanding data center investment, and major metropolitan areas such as Houston, Dallas, Atlanta, and Miami.
- West: One of the major regional markets analyzed in the report.
Key Challenges and Growth Opportunities in the United States Generator Sales Market
The United States generator sales market faces challenges including high initial capital investment and installation costs, stringent environmental regulations and emissions standards, and growing competition from alternative backup power technologies such as battery energy storage systems, fuel cells, and renewable microgrids. Skilled labor shortages for installation and maintenance and varying state-level regulatory requirements also complicate adoption.
Despite these challenges, the market offers considerable growth opportunities in high-capacity generators for data centers, healthcare facilities, and critical infrastructure, as well as in premium offerings built on fuel efficiency, emissions reduction, smart monitoring, and hybrid and renewable-integrated systems. Growing residential adoption in outage-prone regions and rising investment in backup power by commercial and industrial users are also expected to support long-term growth.
Competitive Landscape
The United States generator sales market is moderately consolidated, with established global manufacturers competing alongside regional distributors and specialized solution providers. Players compete on product reliability, technological innovation, fuel efficiency, emissions performance, and comprehensive after-sales service networks, supported by extensive distribution and dealer relationships. Companies such as Generac, Aggreko, Rolls-Royce, GE Vernova, and Baseline Energy Services have recently announced product launches and capacity expansions, and strategic partnerships between generator manufacturers and technology providers are creating differentiated offerings with advanced monitoring and predictive maintenance. The IMARC report examines the competitive landscape along with profiles of the key players.
Recent Developments in the United States Generator Sales Market
- January 2026: Generac acquired a new facility in Sussex, Wisconsin, to expand manufacturing of commercial and industrial generators, supporting data center growth and backup power capacity.
- October 2025: Rolls-Royce introduced the 20V4000 mtu gas generator for North American data centers, delivering 2.8 MW full output with a 45-second ramp-up and supporting both primary and backup power.
- August 2025: Aggreko launched its 400 kW Tier 4 Final diesel generator in North America, offering lower emissions, strict noise compliance, and reduced operating costs for industrial and construction applications. GE Vernova also announced a USD 41 Million investment to expand steam and gas generator assembly and testing capacity at its Schenectady facility.
- June 2025: Baseline Energy Services introduced the NexGen 400, a 400 kW natural gas mobile generator with smart engine technology, ultra-low emissions, and remote monitoring, scalable up to 15 MW for oil, gas, and remote applications.
- April 2025: Generac launched five new high-capacity standby generators (2.25 to 3.25 MW) tailored for hyperscale, colocation, enterprise, and edge data centers.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

