Author: Deepak Mishra

North America Advertising Market Size, Share, Industry Overview, Trends and Forecast 2026-2034

North America Advertising Market Size, Share, Industry Overview, Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “North America Advertising Market Size, Share, Trends and Forecast by Segment, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

North America Advertising Market Size & Share 2026-2034

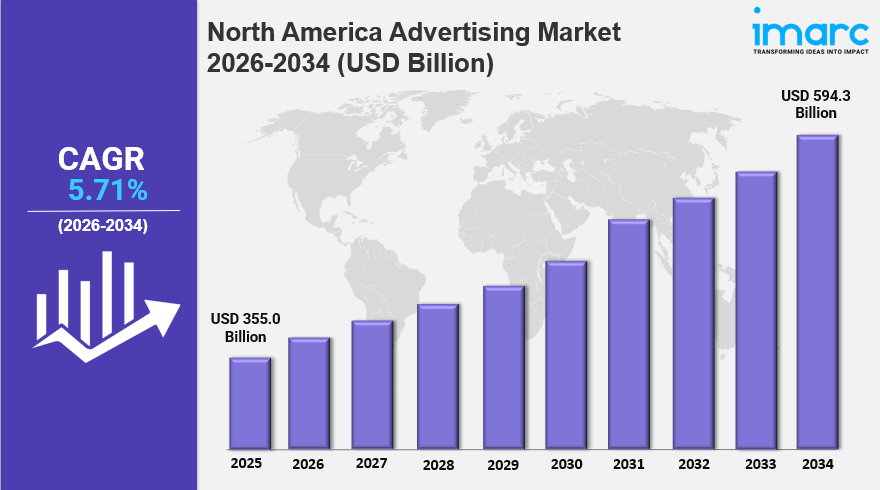
The North America advertising market size reached USD 355.0 Billion in 2025 and is projected to reach USD 594.3 Billion by 2034, expanding at a CAGR of 5.71% during 2026-2034. In 2026, the market continues to gain momentum, shaped by the growing adoption of digital skills that improve content development, user involvement, and overall advertisement efficiency, along with the increasing adoption of OTT channels and streaming services.

Growth in 2026 is further reinforced by the rise of influencer marketing, growing demand for personalization and hyper-targeting, and the expansion of retail and e-commerce platforms. Streaming services allow flexibility to enhance ad formats and target a wider audience. These dynamics are expected to strengthen the North America advertising market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 355.0 Billion
  • Projected Market Size (2034): USD 594.3 Billion
  • Growth Rate: CAGR of 5.71% (2026-2034)

Explore Opportunities in the North America Advertising Market: Download the IMARC Sample Report: https://www.imarcgroup.com/north-america-advertising-market/requestsample

Key Growth Drivers and Trends in the North America Advertising Market

Growth in the North America advertising market is being driven primarily by the growing adoption of digital skills. As more professionals gain digital marketing expertise, companies can use tools such as social media analysis, search engine optimization (SEO), programmatic advertising, and data analytics to reach specific audiences and optimize campaigns in real time. Government agencies are also backing digital skills: in January 2025, the National Telecommunications and Information Administration (NTIA) of the Department of Commerce proposed awarding over USD 369 Million to 41 entities to support digital skills and inclusion initiatives in communities nationwide.

One of the leading North America advertising market trends is the expansion of retail and e-commerce platforms. As more people shop online, retailers are turning to digital ads, and social media platforms have become key advertising channels that allow targeted ads and direct selling. The rise of omnichannel retail also means brands need to advertise across multiple formats, from websites to in-store promotions. Statistics Canada data shows that retail trade e-commerce sales reached USD 4,113,782 in November 2024.

Another key factor supporting North America advertising market growth is the rise of streaming services and over-the-top (OTT) platforms. OTT platforms provide detailed viewer data that lets brands target audiences by interests, demographics, and viewing habits, while ad-supported streaming gives brands a chance to reach viewers with fewer distractions than traditional TV. According to the IMARC report, the United States OTT market is set to reach USD 371.9 Billion by 2032.

Influencer marketing and personalization are also supporting growth. Influencers connect brands with highly engaged niche audiences in more authentic and relatable ways, while data analytics, machine learning (ML), and artificial intelligence (AI) let advertisers tailor ads to individual preferences and behaviors, improving ad performance and return on investment (ROI).

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1778&flag=C

North America Advertising Industry Segmentation Insights

Breakup by Segment:

  • Television Advertising: The largest segment. TV offers wide reach across diverse audiences, especially older demographics, and credibility with established brands. Sectors such as automotive, retail, food and beverage (F&B), and entertainment rely heavily on TV for large-scale, mass-exposure campaigns.
  • Print Advertising: Advertising placed in newspapers, magazines, and other print publications.
  • Radio Advertising: Audio advertising delivered through radio broadcasts.
  • Outdoor Advertising: Advertising displayed in public spaces, such as billboards and signage.
  • Internet Advertising: Digital advertising across websites, search, and social media platforms, supported by programmatic advertising, data analytics, and e-commerce growth.
  • Mobile Advertising: Advertising delivered through smartphones and other mobile devices, including geo-targeted and on-the-go ads.
  • Cinema Advertising: Advertising shown in movie theaters before and during film screenings.

Breakup by Region:

  • United States: The leading market, noted for its large and diverse economy, advanced technology, established media infrastructure, and strong digital ecosystem, including major streaming platforms. It has a highly competitive advertising industry and consistently sets trends with creative, high-budget campaigns.
  • Canada: A key regional market, where e-commerce growth and the testing of new ad-supported streaming services are supporting advertising demand.

Key Challenges and Growth Opportunities in the North America Advertising Market

The North America advertising market faces challenges including the need to adapt to changing user behaviors and new technologies, the shift of audiences from traditional media to digital and streaming platforms, and the need to balance personalized targeting with user privacy.

Despite these challenges, the market offers considerable growth opportunities driven by the rise of influencer marketing, demand for personalization and hyper-targeting, the expansion of retail and e-commerce platforms, and the growth of streaming services and OTT platforms. Rising smartphone usage also lets companies reach users with geo-targeted and on-the-go ads.

Competitive Landscape

The North America advertising market is competitive, with key players developing services and products to meet strong demand. Large companies increasingly rely on highly targeted ads based on user data, while traditional media outlets such as TV networks and print publications remain important for reaching mass audiences. Advertising agencies work with brands on creative campaigns across platforms, and influencers and celebrities help brands connect with younger audiences on social media. In May 2024, Netflix developed a new advertising technology platform as its ad-supported services nearly doubled their user base, planning to test it in Canada in 2024 and introduce its service in the US by the end of the second quarter of 2025. The IMARC report provides a comprehensive analysis of the competitive landscape, with detailed profiles of all major companies.

Recent Developments in the North America Advertising Market

  • January 2025: Amazon Prime revealed its plan to start featuring ads in the US. Prime members who wish to keep an ad-free experience for movies and TV shows will need to pay an extra USD 2.99. Amazon stated that it intends to have significantly fewer ads than traditional television and other streaming services.
  • January 2025: Meta Platforms will start test-launching advertisements on its Threads social media platform with select brands in the US and Japan. Image advertisements will appear in the Threads home feed, positioned between content posts for a limited number of users.
  • January 2025: WHSmith, a British retailer, aims to introduce a retail media advertising network that will enable advertisers to reach consumers at its 347 sites throughout the US and Canada, such as airports, train stations, and holiday destinations.
  • October 2024: DirecTV intended to launch a free ad-supported streaming service named MyFree DirecTV on November 15 in the US. The FAST service aims to feature both linear and on-demand content, with more channels anticipated during 2025, and will be available online, through mobile devices, and on certain smart TVs and streaming platforms.
  • September 2024: Life360, Inc. unveiled its advertising platform in the United States, using the firm’s family insights and location information to provide privacy-focused advertising targeting that links millions of active families with brands, items, and services.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Canada 3PL Market Outlook 2026-2034 | Market to Hit USD 36,361.2 Million by 2034

Canada 3PL Market Outlook 2026-2034 | Market to Hit USD 36,361.2 Million by 2034

IMARC Group has recently released a new research study titled “Canada 3PL Market Report by Mode (Roadways, Railways, Waterways, Airways), Services (Dedicated Contract Carriage (DCC)/Freight Forwarding, Domestic Transportation Management (DTM), International Transportation Management (ITM), Warehousing and Distribution, Value Added Logistics Services (VALs)), End Use (Automotive, Manufacturing, Chemical, Retail, Healthcare and Pharmaceuticals, Construction, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Canada 3PL Market Size & Share 2026-2034

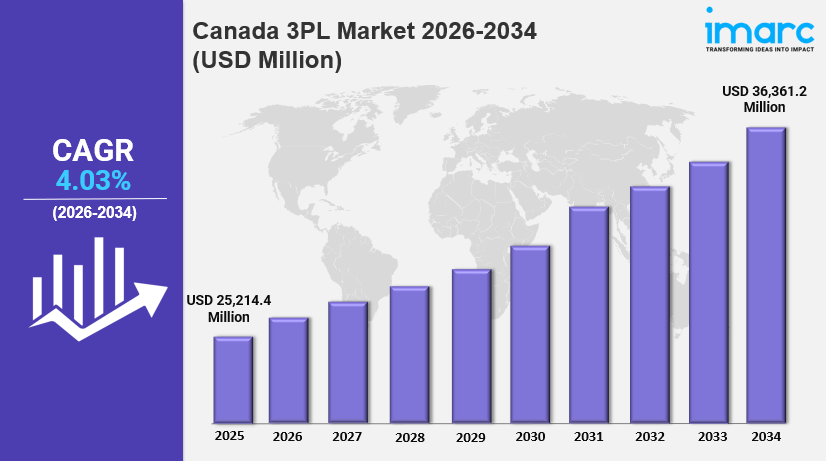
The Canada 3PL market size reached USD 25,214.4 Million in 2025 and is projected to reach USD 36,361.2 Million by 2034, expanding at a CAGR of 4.03% during 2026-2034. In 2026, the market continues to gain momentum, shaped by e-commerce growth, rising demand for efficient supply chain management, advancements in technology, and the growing need for cost-effective logistics solutions.

Growth in 2026 is further reinforced by rapid globalization, the expansion of trade agreements, and greater outsourcing by manufacturers and retailers across distribution, transportation, and warehousing. These dynamics are expected to strengthen the Canada 3PL market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 25,214.4 Million
  • Projected Market Size (2034): USD 36,361.2 Million
  • Growth Rate: CAGR of 4.03% (2026-2034)

Explore Opportunities in the Canada 3PL Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-3pl-market/requestsample

Key Growth Drivers and Trends in the Canada 3PL Market

Growth in the Canada 3PL market is being driven primarily by the rapid expansion of e-commerce, which increases demand for efficient logistics and fulfillment and prompts businesses to rely on 3PL providers to manage supply chains and meet expectations for fast, reliable delivery. According to the International Trade Administration, Canada had over 27 million e-commerce users in 2022, equal to 75% of the population, and this share is expected to reach 77.6% in 2025. Retail e-commerce sales are estimated to total US$ 40.3 billion by 2025, and digital wallets are estimated to account for 27% of online payments by 2025. Retailers are investing in digital platforms to reach consumers spread across a vast landmass and to compete with sites such as Amazon Canada.

One of the leading Canada 3PL market trends is the adoption of advanced technologies such as IoT, AI, and automation, which improve tracking, inventory management, and route optimization. 3PL providers using these technologies can offer enhanced services. In April 2024, Oracle launched updated AI capabilities in its Oracle Fusion Cloud Supply Chain & Manufacturing platform to help companies improve operational efficiency, including risk prediction and inventory visibility. Digital transformation is becoming central to improving supply chain resilience, optimizing asset use, and increasing transparency across complex logistics networks.

Another key factor supporting Canada 3PL market growth is rising focus on sustainability, cold-chain shipping, and omnichannel fulfillment, which align with changing consumer expectations and regulatory pressures and influence technology investment and service design. Heightened cross-border trade with the United States and the need for scalable, cost-effective last-mile delivery further support demand for third-party logistics services.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=23996&flag=C

Canada 3PL Industry Segmentation Insights

Breakup by Mode:

  • Roadways: Trucking and road-based freight services that move goods across Canada’s cities, provinces, and border crossings.
  • Railways: Rail freight services suited to moving bulk and long-distance cargo across the country.
  • Waterways: Marine and inland shipping services linked to ports and international trade.
  • Airways: Air freight services for time-sensitive and high-value shipments.

Breakup by Services:

  • Dedicated Contract Carriage (DCC)/Freight Forwarding: Dedicated transport capacity and freight forwarding arrangements provided to specific customers.
  • Domestic Transportation Management (DTM): Management of the movement of goods within Canada, including carrier selection and routing.
  • International Transportation Management (ITM): Management of cross-border and overseas shipments, including customs and trade documentation.
  • Warehousing and Distribution: Storage, order processing, and distribution services supporting e-commerce and retail fulfillment.
  • Value Added Logistics Services (VALs): Additional services such as packaging, labeling, kitting, and other customized supply chain support.

Breakup by End Use:

  • Automotive: Logistics support for vehicle manufacturing, parts supply, and distribution.
  • Manufacturing: Outsourced transportation, warehousing, and supply chain management for manufacturers.
  • Chemical: Specialized handling, storage, and transport of chemical products.
  • Retail: Fulfillment, warehousing, and last-mile delivery for retailers and e-commerce businesses.
  • Healthcare and Pharmaceuticals: Temperature-sensitive and regulated logistics for medical and pharmaceutical products.
  • Construction: Logistics for construction materials and equipment.
  • Others: Includes other industries not captured in the categories above.

Breakup by Region:

  • Ontario: Canada’s major commercial and industrial province, including the Toronto area, with extensive logistics and distribution activity.
  • Quebec: A large provincial market with strong manufacturing and distribution networks.
  • Alberta: A province whose economy supports demand for transportation and warehousing services.
  • British Columbia: A province with major port and trade gateways on the Pacific coast.
  • Others: Includes the remaining provinces and territories.

Key Challenges and Growth Opportunities in the Canada 3PL Market

The Canada 3PL market faces challenges including growing operating expenses, manpower shortages, and infrastructure deficiencies that confront providers.

Despite these challenges, the market offers considerable growth opportunities in rural expansion, logistics for small and medium-sized enterprises (SMEs), and last-mile development. There is also strong potential for digital expansion and value-added services that match changing customer and industry requirements.

Competitive Landscape

The Canada 3PL market features international and domestic participants competing on service integration, geographic scope, and digital capability. Providers with sophisticated fulfillment, last-mile capabilities, and data-driven insights are gaining an advantage, particularly in metropolitan centers and in industries such as retail, manufacturing, and pharmaceuticals. The IMARC report examines the competitive landscape, including market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant, along with profiles of the major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Sports Betting Market 2026: Size, Share, Trends, Growth and Forecast to 2034

United States Sports Betting Market 2026: Size, Share, Trends, Growth and Forecast to 2034

IMARC Group has recently released a new research study titled “United States Sports Betting Market Report by Platform (Offline, Online), Betting Type (Fixed Odds Wagering, Exchange Betting, Live/In Play Betting, Pari-Mutuel, eSports Betting, and Others), Sports Type (Football, Basketball, Baseball, Horse Racing, Cricket, Hockey, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Sports Betting Market Size & Share 2026-2034

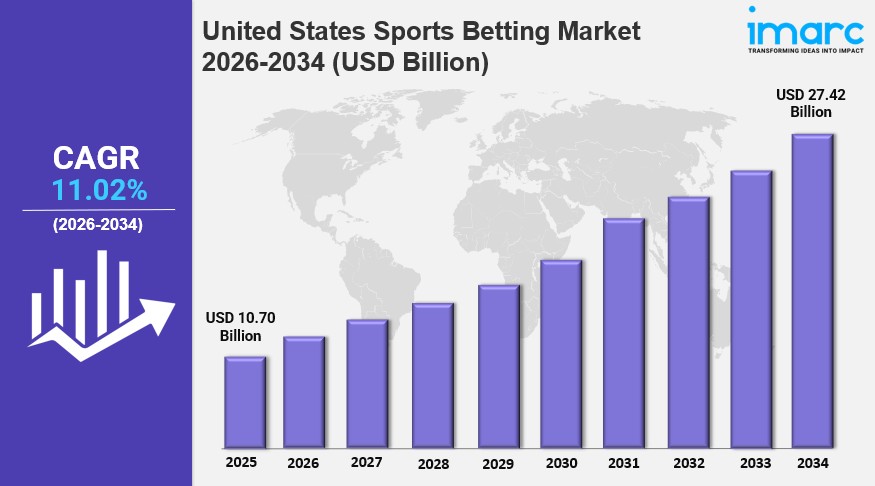
The United States sports betting market size reached USD 10.70 Billion in 2025 and is projected to reach USD 27.42 Billion by 2034, expanding at a CAGR of 11.02% during 2026-2034. In 2026, the market continues to gain momentum, shaped by supportive government initiatives for legalization, the growing number of annual sports events and leagues, and expanding partnerships with major sports leagues.

Growth in 2026 is further reinforced by the rising accessibility of mobile and online betting platforms and the integration of betting services with sports content. These dynamics are expected to strengthen the United States sports betting market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 10.70 Billion
  • Projected Market Size (2034): USD 27.42 Billion
  • Growth Rate: CAGR of 11.02% (2026-2034)
  • Leading Platform: Offline
  • Leading Betting Type: Live/In Play Betting
  • Leading Sports Type: Football
  • Leading Region: South

Explore Opportunities in the United States Sports Betting Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-sports-betting-market/requestsample

Key Growth Drivers and Trends in the United States Sports Betting Market

Growth in the United States sports betting market is being driven primarily by the expansion of legalization across multiple states. As more states enact legislation, access to sports betting is reaching a broader population, creating new revenue streams and encouraging further investment. Supportive government initiatives for legalization are a major catalyst. In July 2024, DraftKings Inc. announced the launch of its online sportsbook in Washington, D.C., pending licensure and regulatory approvals. The growing number of annual sports events and leagues across the country is also fueling the market.

One of the leading United States sports betting market trends is the increasing accessibility of mobile and online betting. Mobile and online platforms make wagering more convenient, enable real-time engagement, and widen user bases, especially as more states legalize these options. In July 2024, BetMGM introduced its mobile sports betting app across Washington, D.C., expanding access beyond its previous Nationals Park radius, with the aim of improving user experience and supporting local job creation and tax revenue.

Another key factor supporting United States sports betting market growth is the rise of partnerships with major sports leagues and platforms. Collaborations between betting operators and sports organizations enhance brand visibility and credibility, and integrate betting with sports content to engage a broader audience. In March 2024, ESPN BET launched its mobile and web sports betting platform in North Carolina, the first new state launch under ESPN’s partnership with PENN Entertainment. The integration of blockchain technology with betting apps to automate real-time data is another factor supporting the market.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=5949&flag=C

United States Sports Betting Industry Segmentation Insights

Breakup by Platform:

  • Offline: The largest segment, led by casinos such as MGM Resorts and retail sportsbooks that offer in-person betting experiences alongside online options.
  • Online: Mobile and web-based betting platforms offering convenience, real-time engagement, and wider access as more states legalize online wagering.

Breakup by Betting Type:

  • Fixed Odds Wagering: Bets placed at odds set in advance by the operator, with the payout known when the wager is made.
  • Exchange Betting: Peer-to-peer wagering in which bettors set or take odds against one another.
  • Live/In Play Betting: The leading segment, allowing real-time wagers during events and offering dynamic in-game options across sports.
  • Pari-Mutuel: A pooled wagering system, common in horse racing, where payouts are shared among winning bettors.
  • eSports Betting: Wagering on competitive video game events and tournaments.
  • Others: Includes other betting formats not captured in the categories above.

Breakup by Sports Type:

  • Football: The leading segment, driven by the popularity of the NFL and college football and by heavy wagering during the NFL season.
  • Basketball: Betting on professional and college basketball games and tournaments.
  • Baseball: Betting on professional baseball, supported by its long season and large number of games.
  • Horse Racing: Betting on races, often through pari-mutuel pools.
  • Cricket: Betting on cricket matches and tournaments.
  • Hockey: Betting on professional and amateur hockey games.
  • Others: Includes other sports and events not captured in the categories above.

Breakup by Region:

  • Northeast: A region with a long-established betting presence and dense, urban sports audiences.
  • Midwest: A region with strong professional and college sports followings supporting betting participation.
  • South: The leading region, supported by early adoption of legalized betting, favorable regulatory frameworks, strong sports culture, and quick uptake of mobile platforms, as seen in Louisiana’s rapid mobile growth after launch.
  • West: A large and diverse region where betting access and participation vary with state-level regulation.

Key Challenges and Growth Opportunities in the United States Sports Betting Market

The United States sports betting market faces challenges from inconsistent state-level regulations, which create barriers for platforms that want to operate nationwide.

Despite this challenge, the market offers considerable growth opportunities. Establishing more uniform laws or federal guidelines would enable consistent user experiences across states and continue to strengthen the market over the forecast period. Further state legalization, wider adoption of mobile platforms, and deeper partnerships with sports leagues and platforms are also expected to support long-term growth.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the United States sports betting market, covering market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant. Detailed profiles of all major companies are also included. Operators active in the market include DraftKings, BetMGM, ESPN BET (in partnership with PENN Entertainment), and casino operators such as MGM Resorts.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Automotive Plastics Market Size, Share, Growth, Trends Analysis, Report 2026-2034

Mexico Automotive Plastics Market Size, Share, Growth, Trends Analysis, Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Automotive Plastics Market Size, Share, Trends and Forecast by Vehicle Type, Material, Application, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Automotive Plastics Market Size & Share 2026-2034

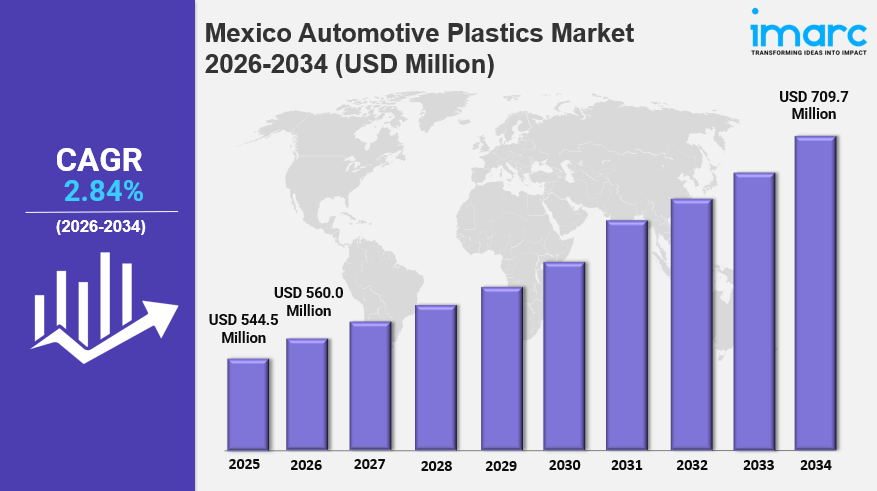
The Mexico automotive plastics market size reached USD 544.5 Million in 2025 to USD 560.0 Million in 2026 and is projected to reach USD 709.7 Million by 2034, growing at a CAGR of 2.84% during 2026-2034. Rising demand for lightweight plastic parts that make vehicles more fuel efficient and minimize carbon emissions is a key driver of growth.

Expanding domestic and export-oriented automotive production and the heightened shift toward electric vehicles (EVs) and hybrid vehicles (HEVs) are further expanding the Mexico automotive plastics market share and are expected to support demand throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 544.5 Million
  • Market Size (2026): USD 560.0 Million
  • Projected Market Size (2034): USD 709.7 Million
  • Growth Rate: CAGR of 2.84% (2026-2034)

Explore Opportunities in the Mexico Automotive Plastics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-automotive-plastics-market/requestsample

Key Growth Drivers and Trends in the Mexico Automotive Plastics Market

Growth in the Mexico automotive plastics market is driven by the increasing adoption of lightweight materials to improve fuel efficiency. Strict environmental standards such as Corporate Average Fuel Economy (CAFE) and Mexico’s commitment to global climate goals are pushing automakers to substitute heavier metal parts with engineering plastics such as polypropylene, acrylonitrile butadiene styrene (ABS), and polycarbonate across interior, exterior, and under-the-hood uses, while tier-one suppliers collaborate with polymer manufacturers on high-end plastic composites.

One of the leading Mexico automotive plastics market trends is the expansion of domestic and export-oriented vehicle production. Mexico is becoming a strategic production center, and its closeness to the U.S. market and the USMCA trade pact make it an important export base for North American automotive supply chains. Plastic suppliers are setting up local manufacturing capacity and technical facilities and working jointly with original equipment manufacturers (OEMs) on light-weighting solutions.

Another key factor is rising demand for electric and hybrid vehicles. Specialized plastics are used to insulate high-voltage systems, reduce vehicle weight, and improve thermal management in battery housings, cable insulation, charging infrastructure, and lightweight structural parts, while government incentives are accelerating EV adoption and driving innovation in recyclable and bio-based plastic alternatives.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33427&flag=C

Mexico Automotive Plastics Industry Segmentation Insights

The report categorizes the Mexico automotive plastics market by vehicle type, material, application, and region, with forecasts at the country and regional levels for 2026-2034.

Breakup by Vehicle Type:

  • Conventional and Traditional Vehicles: Use plastics to replace heavier metal parts and improve fuel efficiency and design flexibility.
  • Electric Vehicles: Rely on specialized plastics for high-voltage insulation, battery housings, thermal management, and weight reduction.

Breakup by Material:

  • Polyethylene (PE): One of the materials covered in the report.
  • Polypropylene (PP): A key engineering plastic used to replace heavier metal parts.
  • Polyvinyl Chloride (PVC): One of the materials covered in the report.
  • Acrylonitrile Butadiene Styrene (ABS): A key engineering plastic offering durability and ease of molding.
  • Polyurethane (PU): One of the materials covered in the report.
  • Polymethyl Methacrylate (PMMA): One of the materials covered in the report.
  • Polycarbonate (PC): A key engineering plastic offering weight savings and corrosion resistance.
  • Polyamide: One of the materials covered in the report.
  • Others: Includes the remaining automotive plastic materials.

Breakup by Application:

  • Powertrain: Plastic components used in powertrain systems.
  • Electrical Components: Includes cable insulation and high-voltage system components, particularly for EVs.
  • Interior Furnishings: Interior plastic parts that support lower production costs and simpler assembly.
  • Exterior Furnishings: Exterior plastic parts that support lightweight design and better vehicle appearance.
  • Under the Hood: Plastics used in engine and under-the-hood parts.
  • Chassis: Lightweight plastic structural components.

Breakup by Region:

  • Northern Mexico: One of the major regional markets analyzed in the report.
  • Central Mexico: One of the major regional markets analyzed in the report.
  • Southern Mexico: One of the major regional markets analyzed in the report.
  • Others: Covers the remaining regions of the country.

Key Challenges and Growth Opportunities in the Mexico Automotive Plastics Market

The market is shaped by the need to balance weight, performance, and price in plastic components, and by pressure to meet strict fuel-economy and emissions standards. Suppliers must also invest in local manufacturing capacity, technical facilities, and collaboration with OEMs to stay competitive.

The market offers considerable opportunities, including growing production of electric and hybrid vehicles, rising output for export under the USMCA, and innovation in recyclable and bio-based plastics aligned with circular economy objectives.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the Mexico automotive plastics market, covering market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant, along with detailed profiles of all major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Sneaker Market Size to Reach USD 40.1 Billion, at a 4.63% CAGR by 2034

United States Sneaker Market Size to Reach USD 40.1 Billion, at a 4.63% CAGR by 2034

IMARC Group has recently released a new research study titled “United States Sneaker Market Size, Share, Trends, and Forecast by Product Type, Category, Price Point, Distribution Channel, End User, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Sneaker Market Size & Share 2026-2034

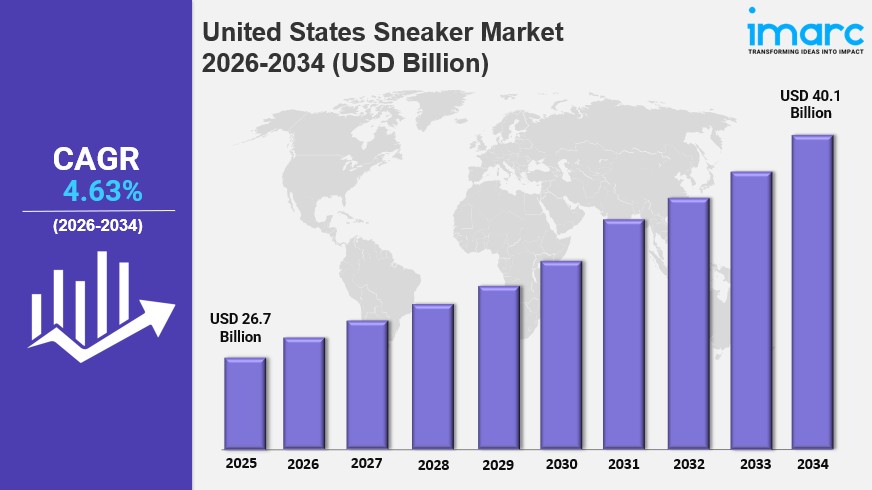
The United States sneaker market size reached USD 26.7 Billion in 2025 and is projected to reach USD 40.1 Billion by 2034, expanding at a CAGR of 4.63% during 2026-2034. In 2026, the market continues to gain momentum, shaped by shifting fashion trends, increased health consciousness, and a growing preference for casual and athleisure wear.

Growth in 2026 is further reinforced by collaborations between brands, celebrities, and athletes, rising e-commerce adoption, and the strength of sneaker culture among youth. These dynamics are expected to strengthen the United States sneaker market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 26.7 Billion
  • Projected Market Size (2034): USD 40.1 Billion
  • Growth Rate: CAGR of 4.63% (2026-2034)

Explore Opportunities in the United States Sneaker Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-sneaker-market/requestsample

Key Growth Drivers and Trends in the United States Sneaker Market

Growth in the United States sneaker market is being driven primarily by the rise of athleisure and changing workplace norms. Sneakers have become essential everyday wear rather than purely athletic gear, as consumers seek stylish, comfortable footwear that suits active lifestyles and relaxed dress codes. IMARC Group reports that the athleisure market reached USD 95.2 Billion in 2024 and is expected to grow at a CAGR of 7.26% from 2025 to 2033, while the casualization of workplace attire has normalized sneakers in office settings.

One of the leading United States sneaker market trends is the influence of celebrity collaborations and exclusive launches. These partnerships generate hype, drive demand, and build brand loyalty through limited-edition releases. For instance, in June 2025, NBA star Devin Booker unveiled the ‘Iridescent’ colorway of his Nike Book 1 sneakers, with an official launch scheduled for July 2025. The allure of exclusivity and limited availability also boosts resale value and reinforces sneaker culture.

Another key factor supporting United States sneaker market growth is innovation, sustainability, and digital reach. Brands are adopting recycled materials and ethical manufacturing practices, as seen in Koio’s first sneaker, launched in April 2023 and made to be 99% biodegradable, and Gabriela Hearst’s ‘Ohio’ sneakers, launched in March 2025 with 30% recycled rubber soles. Meanwhile, e-commerce and direct-to-consumer models make it easier to access new launches, while social media and influencer marketing shape trends and consumer interest. Technological innovations such as smart features, lightweight materials, and custom designs further enhance appeal.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20404&flag=C

United States Sneaker Industry Segmentation Insights

Breakup by Product Type:

  • Low-Top Sneakers: Versatile, lightweight designs with year-round appeal, expected to capture the largest share of the market.
  • Mid-Top Sneakers: Balance the flexibility of low-tops with added ankle support, popular among active lifestyle consumers.
  • High-Top Sneakers: Connected to basketball culture, streetwear, and retro fashion, offering superior ankle support and bold design.

Breakup by Category:

  • Branded: Sneakers from established brands such as Nike, Adidas, and New Balance, expected to hold the largest share due to consumer trust and consistent innovation.
  • Private Label: Retailer-owned sneaker lines gaining traction through competitive pricing, improved quality, and exclusive availability.

Breakup by Price Point:

  • Luxury: Premium, fashion-forward sneakers, including designer collaborations, favored by millennials and Gen Z as status symbols.
  • Economic: Affordable, functional sneakers serving price-sensitive shoppers such as students, working-class individuals, and budget-conscious families.

Breakup by Distribution Channel:

  • Specialty Stores: Curated selections, expert staff, and tailored experiences, expected to dominate the market.
  • Supermarkets and Hypermarkets: High foot traffic, wide assortment, and competitive pricing for economic and entry-level sneakers.
  • Brand Outlets: Offer branded products at discounted prices, including past-season models and outlet-only collections.
  • Online Stores: E-commerce platforms and direct-to-consumer channels that simplify access to new launches and personalized experiences.
  • Others: Includes other retail formats and channels.

Breakup by End User:

  • Men: Expected to hold a major share, driven by lifestyle, sports, and fashion influences, including popular basketball and running shoes.
  • Women: A rapidly expanding segment driven by athleisure, fitness routines, and gender-specific designs and inclusive sizing.
  • Kids: A strong segment supported by repeat purchases as children outgrow shoes, with demand peaking during back-to-school and holiday seasons.

Breakup by Region:

  • Northeast: Driven by urban culture, fashion-forward consumers, a thriving resale market, and a preference for premium and limited-edition releases.
  • Midwest: Supported by interest in health and fitness, basketball and running culture, and price sensitivity that boosts economic and private-label sneakers.
  • South: Driven by warm weather, a growing youth population, strong sports and music culture, and trendsetting hubs such as Atlanta, Houston, and Miami.
  • West: Led by innovation, sustainability, and fitness culture, with early adopters and strong demand for performance and trail-ready sneakers.

Key Challenges and Growth Opportunities in the United States Sneaker Market

The United States sneaker market faces challenges including rising price sensitivity amid inflationary pressures and economic uncertainty, as well as intensifying competition from private-label offerings, emerging brands, and sneaker resale marketplaces that are reshaping consumer access and pricing dynamics.

Despite these challenges, the market offers considerable growth opportunities driven by the continued rise of athleisure, rising health consciousness, celebrity and athlete collaborations, sustainable and eco-friendly product innovation, and expanding e-commerce and direct-to-consumer models. Growing demand for women’s and kids’ sneakers and for personalized experiences is also expected to support long-term growth.

Competitive Landscape

The United States sneaker market is highly competitive and is dominated by global brands such as Nike, Adidas, Puma, and New Balance, which use extensive R&D, celebrity endorsements, and limited-edition releases to maintain market leadership. Emerging players such as Allbirds and On are gaining traction through sustainability, innovation, and direct-to-consumer models, while resale marketplaces such as StockX and GOAT are reshaping consumer access. The IMARC report examines the competitive landscape along with profiles of key players including Adidas AG, Columbia Sportswear Company, ECCO Sko A/S, New Balance Inc., Nike Inc., Puma SE, Reebok International Limited (Authentic Brands Group LLC), Skechers USA Inc., and Under Armour Inc.

Recent Developments in the United States Sneaker Market

  • June 2025: Patta unveiled a new partnership with Nike with ‘The New Wave’ line of sneakers, incorporating the ‘Wave’ design into the Air Max 90, with the ‘Cyber’ and ‘Sapphire’ colorways released so far.
  • May 2025: DICK’S Sporting Goods announced plans to acquire Foot Locker, aiming to leverage its sneaker expertise and portfolio of brands including Champs Sports, WSS, atmos, and Kids Foot Locker.
  • April 2025: Under Armour launched the UA Echo, a sneaker blending street culture into sportswear.
  • March 2025: Nike launched the Air Max Dn8, which uses Dynamic Air technology for cushioning and comfort.
  • January 2025: Reebok released the ‘Engine A,’ its latest performance basketball sneaker.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Medical Aesthetics Market: Size, Share, Trends and Forecast 2026-2034

Mexico Medical Aesthetics Market: Size, Share, Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “Mexico Medical Aesthetics Market Size, Share, Trends and Forecast by Product, Application, End User, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Medical Aesthetics Market Size & Share 2026-2034

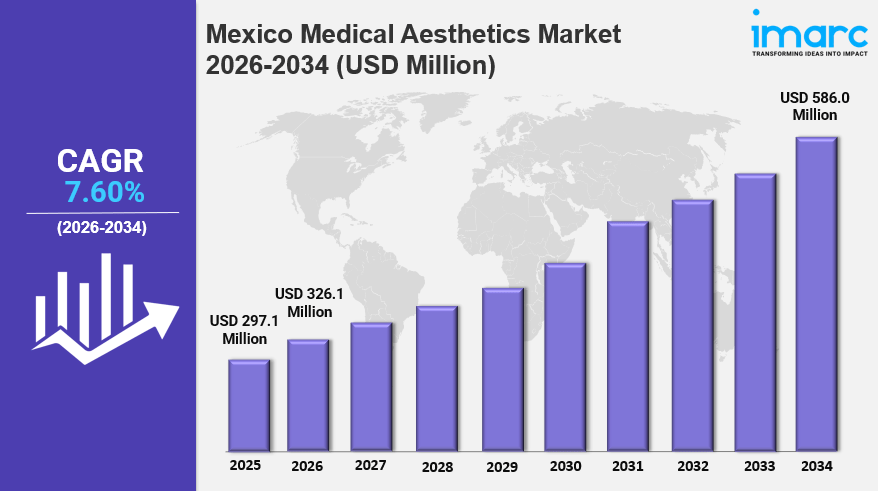
The Mexico medical aesthetics market size increased from USD 297.1 Million in 2025 to USD 326.1 Million in 2026 and is projected to reach USD 586.0 Million by 2034, expanding at a CAGR of 7.60% during 2026-2034. In 2026, the market continues to gain momentum, driven by increasing demand for minimally invasive procedures, rising awareness about aesthetic treatments, and a growing number of private clinics offering advanced services.

The market is segmented by product (devices and aesthetic implants), application (surgical and non-surgical), end user (hospitals and clinics, and medical spas and beauty centers), and region (Northern, Central, and Southern Mexico, and others). Technological advancements and a growing focus on enhancing physical appearance are expected to strengthen the Mexico medical aesthetics market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 297.1 Million
  • Market Size (2026): USD 326.1 Million
  • Projected Market Size (2034): USD 586.0 Million
  • Growth Rate: CAGR of 7.60% (2026-2034)

Explore Opportunities in the Mexico Medical Aesthetics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-medical-aesthetics-market/requestsample

Key Growth Drivers and Trends in the Mexico Medical Aesthetics Market

Growth in the Mexico medical aesthetics market is being driven primarily by growing demand for minimally invasive procedures. Consumers are increasingly choosing non-surgical treatments such as Botox, dermal fillers, chemical peels, and laser therapies, which offer quick results, shorter recovery times, and fewer health complications. The appeal of subtle, natural-looking improvements is especially strong among working professionals and younger consumers, amplified by social media and aesthetic influencers.

One of the leading Mexico medical aesthetics market trends is rising aesthetic awareness and cultural acceptance. Aesthetic procedures are becoming more normalized, with digital platforms, influencers, and medical tourism driving interest among both men and women. Younger generations view cosmetic enhancement as a form of self-expression and personal care, and aesthetic medicine is increasingly linked to self-confidence and mental well-being. Clinics are responding with customized, lifestyle-oriented treatments that encourage first-time users and repeat procedures.

Another key factor supporting Mexico medical aesthetics market growth is the expansion of private clinics and medical tourism. Private aesthetic clinics and specialized dermatology centers have grown significantly, particularly in Mexico City, Monterrey, and Guadalajara. Patients from the U.S., Canada, and Central America travel to Mexico for cost-effective cosmetic procedures, supported by trained professionals, advanced technologies, and competitive pricing.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33894&flag=C

Mexico Medical Aesthetics Industry Segmentation Insights

Breakup by Product:

  • Devices: Covers aesthetic devices used in medical aesthetic procedures.
  • Aesthetic Implants: Covers implants used in aesthetic and cosmetic procedures.

Breakup by Application:

  • Surgical: Covers surgical aesthetic procedures.
  • Non-Surgical: Covers minimally invasive treatments such as Botox, dermal fillers, chemical peels, and laser therapies.

Breakup by End User:

  • Hospitals and Clinics: Includes hospitals, private aesthetic clinics, and specialized dermatology centers.
  • Medical Spas and Beauty Centers: Covers medical spas and beauty centers offering aesthetic treatments.

Breakup by Region:

  • Northern Mexico: Covered in the report’s regional breakup, which includes Monterrey as a key city for private aesthetic clinics.
  • Central Mexico: Covered in the report’s regional breakup, which includes Mexico City and Guadalajara as key cities for private aesthetic clinics.
  • Southern Mexico: Covered in the report’s regional breakup.
  • Others: Includes the remaining regions of Mexico.

Key Opportunities and Market Dynamics in the Mexico Medical Aesthetics Market

The Mexico medical aesthetics market offers considerable opportunities from the rising popularity of non-surgical treatments, which are driving service expansion at clinics and dermatology centers in both urban and emerging regions. Medical tourism from the U.S., Canada, and Central America, combined with the availability of trained professionals, advanced technologies, and competitive pricing, positions Mexico as a key destination for aesthetic medicine.

Cultural acceptance of aesthetic procedures, customized and lifestyle-oriented treatment offerings, and growing healthcare infrastructure are expected to support first-time and repeat demand, helping the market grow steadily through 2034.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the Mexico medical aesthetics market, featuring major players such as AbbVie Inc. (Allergan Aesthetics), Galderma S.A., Merz Pharma GmbH & Co. KGaA, Bausch Health Companies Inc., and Johnson & Johnson. These companies offer a broad range of aesthetic solutions, including botulinum toxin products, dermal fillers, skin rejuvenation technologies, and non-invasive cosmetic treatments.

Other notable participants include Candela Corporation, Cynosure LLC, InMode Ltd., Lumenis Ltd., and Sisram Medical Ltd. (Alma Lasers), which focus on energy-based aesthetic devices, laser treatments, skin tightening, and body contouring technologies. The report evaluates market structure, key player positioning, winning strategies, competitive benchmarking, and company profiles to provide insights into the competitive dynamics and strategic developments shaping the Mexico medical aesthetics market.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Argentina Data Center Market Size, Share, Demand, Forecast, Report 2026-2034

Argentina Data Center Market Size, Share, Demand, Forecast, Report 2026-2034

IMARC Group has recently released a new research study titled “Argentina Data Center Market Size, Share, Trends and Forecast by Component, Type, Enterprise Size, End User, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Argentina Data Center Market Size & Share 2026-2034

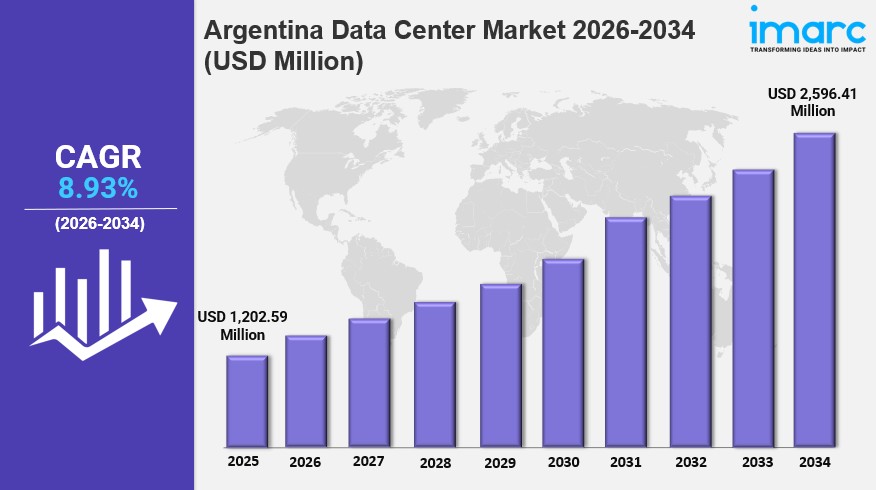
The Argentina data center market size reached USD 1,202.59 Million in 2025 and is projected to reach USD 2,596.41 Million by 2034, expanding at a CAGR of 8.93% during 2026-2034. In 2026, the market continues to gain momentum, propelled by digital transformation and cloud computing demand, the expansion of 5G networks and telecom infrastructure, and government policies supporting innovation and data security.

Growth in 2026 is further reinforced by businesses requiring scalable, secure infrastructure, rising data creation across finance, retail, healthcare, and government, and growing investment from local and global operators. These dynamics are expected to strengthen the Argentina data center market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 1,202.59 Million
  • Projected Market Size (2034): USD 2,596.41 Million
  • Growth Rate: CAGR of 8.93% (2026-2034)

Explore Opportunities in the Argentina Data Center Market: Download the IMARC Sample Report: https://www.imarcgroup.com/argentina-data-center-market/requestsample

Key Growth Drivers and Trends in the Argentina Data Center Market

Growth in the Argentina data center market is being driven by rising demand for digital transformation and cloud computing. As companies shift operations to digital platforms, they need scalable, adaptable, and dependable IT infrastructure, and cloud computing lets them store and analyze large volumes of data without managing costly on-site facilities. Sectors such as finance, retail, healthcare, and government rely heavily on real-time data, while tightening regulatory pressure on data privacy and security is pushing organizations toward compliant, secure data solutions.

One of the leading Argentina data center market trends is government support for data infrastructure development. Policies aimed at improving broadband connectivity, encouraging digital innovation, and strengthening data security are encouraging investment, while regulatory frameworks for data privacy and compliance give companies confidence to invest. Tax benefits, including tax reductions for tech firms, and the encouragement of public-private partnerships are attracting both local and global investors.

Another key factor supporting Argentina data center market growth is telecommunications network upgrades and the 5G rollout. Faster, more dependable 5G networks enable applications such as IoT, self-driving cars, intelligent cities, and augmented reality, all of which generate large volumes of real-time data. Telecom Argentina’s initiative to establish 750 operational 5G sites by 2025 and to upgrade its 16 data centers for AI and business applications highlights the demand, and its Pacheco data center, with a 10MW capacity, showcases the scale of investment required.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=43849&flag=C

Argentina Data Center Industry Segmentation Insights

Breakup by Component:

  • Solution: Covers the core data center infrastructure, including IT, power, cooling, and storage systems that support cloud and enterprise workloads.
  • Services: Includes the design, integration, management, and support services that keep data centers secure, available, and compliant.

Breakup by Type:

  • Colocation: Allows enterprises to host IT infrastructure in shared facilities, avoiding the cost of building and operating their own sites.
  • Hyperscale: Large-scale facilities built to support cloud computing and high-volume data processing needs.
  • Edge: Smaller facilities placed closer to users to support low-latency applications enabled by 5G, IoT, and smart cities.
  • Others: Includes additional data center types serving specialized requirements.

Breakup by Enterprise Size:

  • Large Enterprises: Drive demand for high-capacity, secure, and compliant infrastructure to support large-scale digital operations.
  • Small and Medium Enterprises: Increasingly adopt cloud and colocation services to access scalable IT infrastructure without heavy upfront investment.

Breakup by End User:

  • BFSI: Relies on real-time data processing, security, and regulatory compliance for banking, financial, and insurance operations.
  • IT and Telecom: Driven by 5G rollout, network upgrades, and growing demand for data processing and storage.
  • Government: Supported by public digitalization initiatives and the need for secure data infrastructure.
  • Energy and Utilities: Demand supported by the digitalization of operations and the need for reliable data management.
  • Others: Includes additional end-user industries such as retail and healthcare.

Breakup by Region:

  • Buenos Aires Region: The primary hub for data center activity, home to major carrier-neutral campuses and new capacity investments.
  • Litoral Region: Supported by industrial and agribusiness activity and growing regional digital demand.
  • Northern Region: Emerging demand driven by expanding connectivity and regional digitalization.
  • Cordoba Region: Supported by a strong technology and services base and a growing digital economy.
  • Cuyo Region: Growing demand linked to regional industry and improving broadband connectivity.
  • Patagonia Region: Emerging opportunities tied to regional industry and energy sector digitalization.

Key Challenges and Growth Opportunities in the Argentina Data Center Market

The Argentina data center market faces challenges including the high cost of building and operating advanced facilities, the need to meet evolving data privacy and security regulations, and the requirement to maintain reliable power and connectivity as capacity scales. Competition among local and global operators also shapes investment decisions and pricing.

Despite these challenges, the market offers considerable growth opportunities driven by rising cloud adoption, the expansion of 5G and broadband networks, and growing demand for AI and intensive workloads. Government incentives, public-private partnerships, and continued capacity investment, including modular and scalable facilities, are expected to create substantial long-term opportunities.

Competitive Landscape

The Argentina data center market features telecom operators, colocation providers, and regional hosting firms investing in new and expanded capacity. Companies such as Telecom Argentina, Cirion Technologies, and G2K are building out facilities to meet rising demand for cloud, AI, and enterprise workloads, while partnerships, carrier-neutral campuses, and modular designs continue to shape the competitive environment.

Recent Developments in the Argentina Data Center Market

  • August 2025: Cirion Technologies expanded its BUE1 data center in Buenos Aires, adding over 2MW of capacity and around 160 racks to support AI and intensive workloads. The company aims to make the facility the leading carrier-neutral campus in Buenos Aires, as part of a broader Latin America growth strategy that includes new data centers in Sao Paulo, Rio de Janeiro, and Quito.
  • October 2024: Latin American hosting firm G2K announced plans to build a 10MW data center in Buenos Aires with a USD 20 million investment. The 3,000 sqm facility was scheduled to launch in 2025 and is designed to be modular and scalable to meet future demand.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Cosmetics Market Size, Trends, Growth and Forecast 2026-2034

United States Cosmetics Market Size, Trends, Growth and Forecast 2026-2034

IMARC Group has recently released a new research study titled “United States Cosmetics Market Size, Share, Trends and Forecast by Product Type, Category, Gender, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Cosmetics Market Size & Share 2026-2034

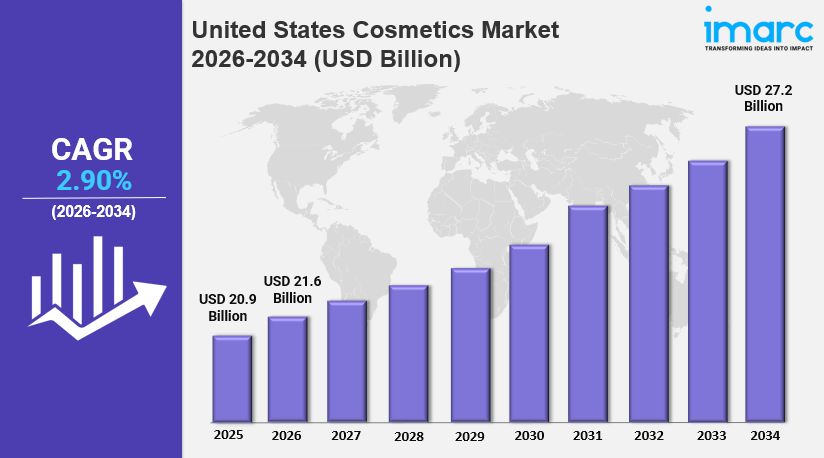
The United States cosmetics market size reached USD 20.9 Billion in 2025, grew to USD 21.6 Billion in 2026, and is projected to reach USD 27.2 Billion by 2034, expanding at a CAGR of 2.90% during 2026-2034. In 2026, the market continues to gain momentum, propelled by the shift toward sustainability, technological advancements in personalized beauty, and the growing influence of social media and digital platforms.

Growth in 2026 is further reinforced by consumers increasingly preferring eco-friendly and cruelty-free products, rising disposable incomes, growing self-care awareness, and an expanding male grooming segment. These dynamics are shaping consumer purchasing behavior and are expected to strengthen the United States cosmetics market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 20.9 Billion
  • Market Size (2026): USD 21.6 Billion
  • Projected Market Size (2034): USD 27.2 Billion
  • Growth Rate: CAGR of 2.90% (2026-2034)

Explore Opportunities in the United States Cosmetics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-cosmetics-market/requestsample

Key Growth Drivers and Trends in the United States Cosmetics Market

Growth in the United States cosmetics market is being driven by rising consumer awareness of personal grooming and beauty enhancement, particularly among millennials and Gen Z. An April 2024 industry survey reported that 72% of U.S. male consumers aged 18 to 34 incorporate makeup into their grooming routines, and nearly half of all U.S. male consumers use cosmetic products. Demand for clean, organic, and cruelty-free products, the influence of social media and celebrity endorsements, and advances in anti-aging and skin-repair formulations further support the market, alongside customized and inclusive beauty products and multifunctional products that save time. Rising incomes also allow consumers to invest in premium brands: per capita disposable income in the United States was USD 51,624.60 as of 2024, up from USD 49,000 in 2019.

One of the leading United States cosmetics market trends is the demand for sustainable and clean beauty products. In June 2024, Herbivore Botanicals announced a strategic shift to prioritize clinical efficacy and sustainability, in line with a 2024 McKinsey report showing that 50% of U.S. and U.K. consumers consider clinical effectiveness a top purchasing factor, while about 20% prioritize natural or clean ingredients. Vegan, cruelty-free, and eco-friendly formulations, biodegradable packaging, and transparent labeling are increasingly influencing purchases. Seasonal demand is also notable: in November 2024, prestige beauty sales grew 7% to USD 22.8 Billion and mass-market sales rose 2%, with prestige lip products up 21% in dollar sales.

Another key factor supporting United States cosmetics market growth is the reliance on digital platforms and e-commerce. U.S. consumers spent a record USD 1.3 Trillion online in 2023, including USD 389.2 Billion in the fourth quarter alone, and social media tutorials, reviews, and influencer recommendations are shaping buying behavior. Augmented reality (AR) virtual try-ons, subscription services, and digital-first beauty brands are improving the online shopping experience and expanding market reach.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=11698&flag=C

United States Cosmetics Industry Segmentation Insights

IMARC Group provides an analysis of the key trends in each segment of the United States cosmetics market, along with forecasts at the country and regional levels for 2026-2034. The market has been categorized by product type, category, gender, distribution channel, and region.

Breakup by Product Type:

  • Skin and Sun Care Products: Driven by rising awareness of skincare routines and sun protection, with demand for solutions addressing aging, hydration, and sensitivity, SPF-infused products, and natural, dermatologist-approved formulations.
  • Hair Care Products: A cornerstone of the market, supported by personalized solutions for hair loss, scalp care, and texture-specific needs, demand for chemical-free and organic options, and products such as dry shampoos, leave-in treatments, and at-home coloring kits.
  • Deodorants and Fragrances: Supported by personal hygiene needs and the view of fragrance as a lifestyle accessory, with a trend toward natural, hypoallergenic, and eco-conscious formulations.
  • Makeup and Color Cosmetics: Covered in the report as a distinct product type.
  • Others: Covers remaining cosmetic product types.

Breakup by Category:

  • Conventional: Continues to dominate due to wide availability, long-standing consumer trust, proven ingredients, competitive prices, and strong retail access.
  • Organic: Rapidly gaining traction as consumers prioritize natural, eco-friendly, and cruelty-free ingredients and align with the wellness movement.

Breakup by Gender:

  • Men: Expanding rapidly as norms around grooming evolve, with rising demand for moisturizers, cleansers, anti-aging products, beard oils, and shaving creams.
  • Women: The largest and most dominant segment, driving a significant portion of overall sales across skincare, makeup, and haircare, with growing focus on natural, clean, and cruelty-free formulations.
  • Unisex: Gaining traction as younger generations prioritize inclusive, gender-neutral, minimalistic, and versatile products.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Offer wide accessibility, product variety across premium and affordable options, in-store promotions, and the chance to test products in person.
  • Specialty Stores: Offer curated, high-quality, niche, premium, and organic lines, with personalized service and a platform for emerging brands.
  • Pharmacies: A trusted outlet for over-the-counter and dermatologically tested skincare and beauty products, with growing pharmacy-based beauty consultations.
  • Online Stores: Covered in the report as a distinct distribution channel.
  • Others: Covers remaining distribution channels.

Breakup by Region:

  • Northeast: High population density and strong consumer spending power, with New York, Boston, and Philadelphia as influential beauty and fashion hubs and rising demand for luxury and clean beauty.
  • Midwest: An expanding consumer base and rising disposable income, with growing interest in drugstore and luxury beauty, and Chicago as a key retail and distribution hub.
  • South: Demand supported by cultural diversity and a large population, with Texas, Florida, and Georgia as key drivers and climate-specific demand for sun protection and anti-aging products.
  • West: A trendsetting region led by California, with Los Angeles considered a global beauty capital, strong wellness-driven beauty trends, and a hotspot for emerging brands.

Key Challenges and Growth Opportunities in the United States Cosmetics Market

The United States cosmetics market faces challenges from high competition, regulatory issues, increasing raw material prices, counterfeit goods, and changing consumer demands for transparency and sustainability.

Despite this, the market offers considerable growth opportunities in AI-driven personalization, sustainable packaging, direct-to-consumer (D2C) business models, men’s grooming expansion, and catering to Gen Z through affordable, sustainable, and technology-enabled products.

Competitive Landscape

The United States cosmetics market is characterized by intense competition across skincare, makeup, haircare, and fragrance. Companies are investing in clean beauty, cruelty-free, and sustainable product lines, while e-commerce platforms and social media marketing allow new and smaller brands to challenge established players. Competitive strategies include celebrity endorsements, product diversification, and influencer partnerships. In November 2024, L’Oreal USA celebrated the 2024 For Women in Science winners, awarding USD 60,000 grants to five female postdoctoral scientists; the initiative has given more than USD 5 Million in funding to over 100 women scientists since 2003. Some of the major players in the market include:

  • Beiersdorf
  • Coty Inc.
  • Estee Lauder Companies
  • Godrej
  • Kao Corporation
  • L’Oreal
  • Procter & Gamble
  • Revlon
  • Shiseido Company
  • Unilever

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Taiwan Private Equity Market Size, Growth, Trends & Outlook 2026-2034

Taiwan Private Equity Market Size, Growth, Trends & Outlook 2026-2034

IMARC Group has recently released a new research study titled “Taiwan Private Equity Market Size, Share, Trends and Forecast by Fund Type and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Taiwan Private Equity Market Size & Share 2026-2034

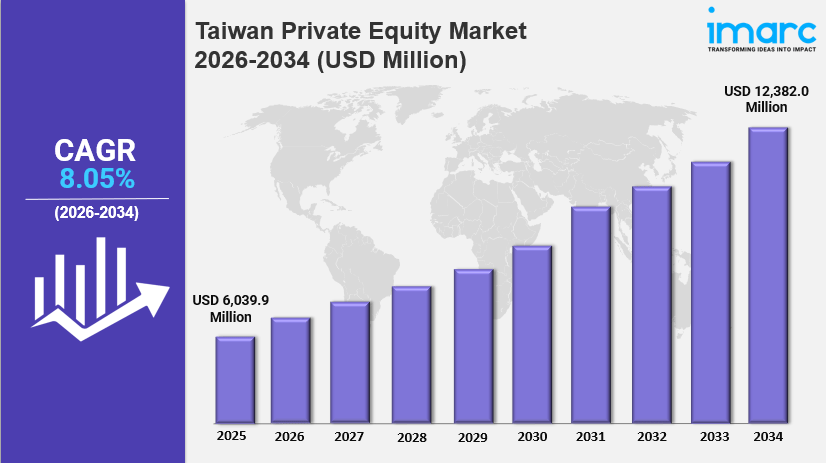
The Taiwan private equity market size reached USD 6,039.9 Million in 2025 and is projected to reach USD 12,382.0 Million by 2034, expanding at a CAGR of 8.05% during 2026-2034. In 2026, the market continues to gain momentum, propelled by green energy regulations, robust AI and semiconductor clusters, regulatory liberalization, and expanding biotech innovation.

Growth in 2026 is further reinforced by capital flowing toward technology-driven and industrial projects, even as cautious geopolitics and softer deal volumes introduce risk. These dynamics, alongside signs of revival, are expected to strengthen the Taiwan private equity market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 6,039.9 Million
  • Projected Market Size (2034): USD 12,382.0 Million
  • Growth Rate: CAGR of 8.05% (2026-2034)

Explore Opportunities in the Taiwan Private Equity Market: Download the IMARC Sample Report: https://www.imarcgroup.com/taiwan-private-equity-market/requestsample

Key Growth Drivers and Trends in the Taiwan Private Equity Market

Growth in the Taiwan private equity market is being driven by an increased focus on technology and innovation. Taiwan’s vibrant tech ecosystem, centered on semiconductor manufacturing, AI, and green technology, is attracting private equity firms that concentrate on innovative start-ups and growing IT enterprises. A 2025 Pictet Alternative Advisors survey found that 68% of private equity general partners expect AI to reduce business costs, with over 60% reporting increased revenue in portfolio companies, although data quality and cybersecurity remain barriers.

One of the leading Taiwan private equity market trends is the rise of investments in emerging technologies such as 5G, AI, and electric vehicles, which offer substantial development prospects. Taiwan’s continued importance in the global tech supply chain is drawing in both domestic and foreign investors seeking exposure to these growth areas.

Another key factor supporting Taiwan private equity market growth is cross-border investment and regional expansion. Taiwan-based private equity firms are diversifying into Southeast Asia, targeting consumer products, healthcare, and logistics businesses that benefit from Taiwan’s manufacturing strengths. Regulatory liberalization is also helping, as seen in the Financial Supervisory Commission’s rule, effective February 24, 2025, allowing foreign institutional investors to appoint one primary and up to three secondary custodians to improve investment efficiency and attract international capital.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=40839&flag=C

Taiwan Private Equity Market Segmentation Insights

Breakup by Fund Type:

  • Buyout: Covers funds acquiring controlling stakes in established companies, supported by institutional commitments to global buyout strategies.
  • Venture Capital (VCs): Covers funds backing innovative start-ups and growing technology companies across semiconductors, AI, 5G, and green technology.
  • Real Estate: Covers funds investing in property assets and real estate-related opportunities.
  • Infrastructure: Covers funds investing in long-term assets, with institutional investors such as Taiwanese insurers allocating capital to infrastructure strategies.
  • Others: Includes additional private equity fund strategies.

Breakup by Region:

  • Northern Taiwan: Covered as a major regional market in the report.
  • Central Taiwan: Covered as a major regional market in the report.
  • Southern Taiwan: Covered as a major regional market in the report.
  • Eastern Taiwan: Covered as a major regional market in the report.

Key Challenges and Growth Opportunities in the Taiwan Private Equity Market

The Taiwan private equity market faces challenges including cautious geopolitics, a decline in deal volume, and barriers to technology adoption within portfolio companies, such as data quality and cybersecurity concerns.

Despite these challenges, the market offers considerable growth opportunities driven by Taiwan’s AI and semiconductor clusters, green energy regulations, regulatory liberalization, and expanding biotech innovation. Cross-border expansion into Southeast Asia and growing institutional demand for alternative assets are expected to create substantial long-term opportunities.

Competitive Landscape

The Taiwan private equity market is competitive, with domestic firms, global managers, and institutional investors vying for technology-driven and industrial opportunities. Secondary market activity, institutional fund commitments, and cross-border investments by Taiwan-based firms continue to reshape the competitive environment, with global secondaries firms such as StepStone expanding their role in Asia.

Recent Developments in the Taiwan Private Equity Market

  • May 2025: StepStone Group emerged as the buyer of Taiwan Life Insurance’s private equity portfolio, a major secondary market transaction reflecting strong demand from global secondaries firms and Taiwanese insurers’ efforts to rebalance their private asset holdings.
  • January 2024: Taiwan’s Fubon Life Insurance committed USD 300 Million to global buyout and infrastructure private equity funds, aiming to boost its alternative-asset allocation through partnerships with managers across multiple strategies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Canada Logistics Market Size, Share & Growth Report 2034

Canada Logistics Market Size, Share & Growth Report 2034

IMARC Group has recently released a new research study titled “Canada Logistics Market Size, Share, Trends and Forecast by Model Type, Transportation Mode, End Use, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Canada Logistics Market Size & Share 2026-2034

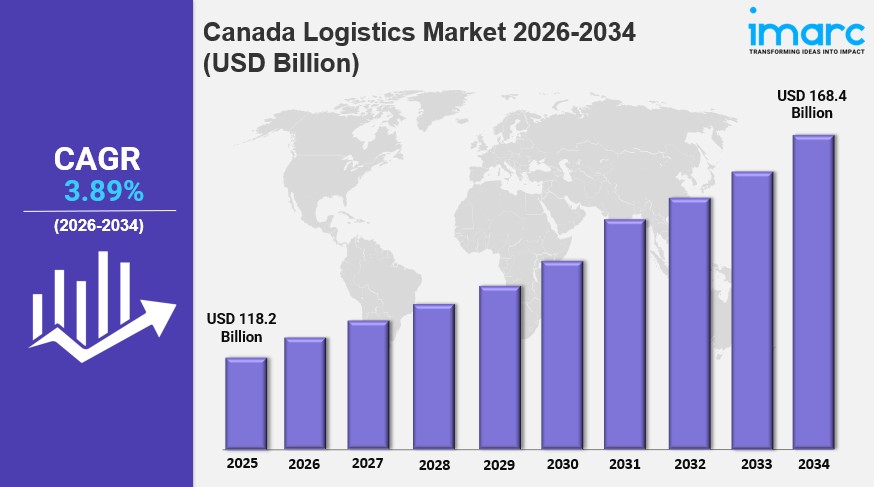
The Canada logistics market size reached USD 118.2 Billion in 2025 and is projected to reach USD 168.4 Billion by 2034, expanding at a CAGR of 3.89% during 2026-2034. In 2026, the market continues to gain momentum, fueled by e-commerce expansion, technological advancements, growing cross-border trade, and infrastructure spending.

Growth in 2026 is further reinforced by rising demand for effective supply chain solutions and sustainable operations, which consolidate operations and service delivery. These dynamics are expected to strengthen the Canada logistics market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 118.2 Billion
  • Projected Market Size (2034): USD 168.4 Billion
  • Growth Rate: CAGR of 3.89% (2026-2034)

Explore Opportunities in the Canada Logistics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-logistics-market/requestsample

Key Growth Drivers and Trends in the Canada Logistics Market

Growth in the Canada logistics market is being driven by the integration of advanced technologies. Logistics providers are using Artificial Intelligence (AI), Internet of Things (IoT), and machine learning to streamline route planning, track shipments in real time, and forecast demand variations. AI programs scan large volumes of data to identify optimal delivery routes based on traffic flow and weather patterns, while IoT offers real-time monitoring of goods, improving transparency and customer experience. In June 2025, UniUni, a tech-enabled logistics company based in Richmond, BC, was named “Last Mile Company of the Year” by SupplyTech Breakthrough. It uses AI-driven routing, robotic sorting, and real-time tracking, operates in over 500 North American cities, and reaches 80% of Canada’s population.

One of the leading Canada logistics market trends is the expansion of e-commerce and last-mile delivery solutions. Rapid e-commerce growth, particularly in urban areas, and customer demand for faster delivery are pushing logistics firms to improve last-mile efficiency. Firms are adopting micro-fulfillment centers, smaller warehouses located closer to consumers that enable rapid shipping, while drones and delivery robots are being used to speed up delivery and reduce its cost, making the sector more responsive and versatile.

Another key factor supporting Canada logistics market growth is rising cross-border trade and infrastructure spending, alongside demand for sustainable operations. Providers integrating fulfillment, delivery, returns, and real-time tracking, supported by smart routing and electric vehicles, are enhancing speed, efficiency, and environmental performance across the supply chain.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=37490&flag=C

Canada Logistics Industry Segmentation Insights

Breakup by Model Type:

  • 2 PL: Second-party logistics, in which providers supply core transportation or asset-based services such as moving goods between locations.
  • 3 PL: Third-party logistics, covering outsourced warehousing, fulfillment, delivery, and returns, as offered by providers such as GoBolt.
  • 4 PL: Fourth-party logistics, in which providers manage and integrate the entire supply chain, including technology and partners, on behalf of clients.

Breakup by Transportation Mode:

  • Roadways: Supports last-mile and long-haul movement of goods across Canada, with AI-driven routing and delivery innovation improving efficiency.
  • Seaways: Supports cross-border and international trade through ports and maritime shipping.
  • Railways: Moves bulk and long-distance freight across Canada’s vast geography.
  • Airways: Serves time-sensitive and high-value shipments that require fast delivery.

Breakup by End Use:

  • Manufacturing, Automotive and Construction: Rely on logistics for the inbound flow of materials and components and the outbound delivery of finished goods and heavy equipment.
  • Consumer Goods, Retail and Food and Beverages: Driven by e-commerce growth, demand for faster delivery, and the need for responsive, temperature-sensitive supply chains.
  • IT Hardware and Telecom: Depend on secure, time-critical transport and tracking of high-value equipment.
  • Healthcare: Supported by supply chain efficiency tools such as Tecsys’ smart electronic shelf labels for hospital inventory management.
  • Chemicals and Oil and Gas: Require specialized, compliant handling and transport for bulk and hazardous materials.
  • Others: Covers additional industries relying on logistics services.

Breakup by Region:

  • Ontario: A major regional market, analyzed in the report alongside the country’s other key provinces.
  • Quebec: A key regional market covered in the report.
  • Alberta: A significant regional market covered in the report.
  • British Columbia: A key regional market, home to tech-enabled logistics players such as UniUni, based in Richmond.
  • Others: Covers the remaining provinces and territories contributing to logistics demand.

Key Challenges and Growth Opportunities in the Canada Logistics Market

The Canada logistics market faces challenges including the cost of investing in new technologies and infrastructure, the complexity of serving a vast geography with dispersed population centers, and rising expectations for faster, more reliable, and more sustainable delivery.

Despite these challenges, the market offers considerable growth opportunities driven by e-commerce expansion, cross-border trade, and infrastructure spending. Continued adoption of AI, IoT, micro-fulfillment, and low-emission delivery solutions is expected to create substantial long-term opportunities.

Competitive Landscape

The Canada logistics market is competitive, with established providers and technology-led challengers such as GoBolt and UniUni investing in AI-driven routing, real-time tracking, and sustainable delivery. Market structure, key player positioning, top winning strategies, and company evaluation are central to how the competitive environment continues to evolve, as providers differentiate through technology and service quality.

Recent Developments in the Canada Logistics Market

  • June 2025: GoBolt, a Toronto-based 3PL and last-mile logistics provider, was named “Overall Logistics Solution Provider of the Year” by the 2025 SupplyTech Breakthrough Awards. Recognized for sustainable, tech-driven solutions, GoBolt integrates fulfillment, delivery, returns, and real-time tracking, with smart routing and electric vehicles enhancing speed, efficiency, and environmental impact.
  • June 2025: Tecsys Inc. launched ESL+, a smart electronic shelf label for hospital inventory management. Integrated with Tecsys’ Elite™ Point of Use platform, ESL+ enhances supply chain efficiency through real-time tracking, programmable restock features, and visual alerts, streamlining workflows and reducing waste.
  • June 2025: UniUni, a tech-enabled logistics company based in Richmond, BC, was named “Last Mile Company of the Year” by SupplyTech Breakthrough, using AI-driven routing, robotic sorting, and real-time tracking to optimize last-mile delivery across 500+ North American cities.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302