Author: Deepak Mishra

Mexico Protein Bar Market Size Trends & Growth Report 2026-2034

Mexico Protein Bar Market Size Trends & Growth Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Protein Bar Market Size, Share, Trends and Forecast by Source, Type, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Protein Bar Market Size & Share 2026-2034

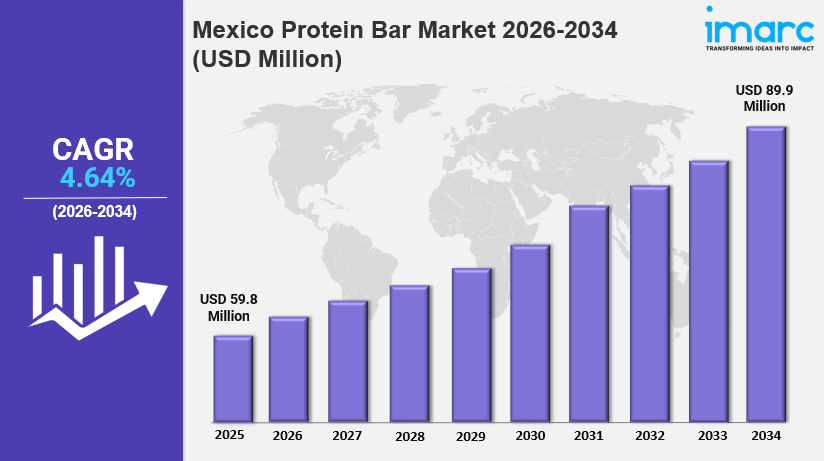
The Mexico protein bar market size reached USD 59.8 Million in 2025 and is projected to reach USD 89.9 Million by 2034, expanding at a CAGR of 4.64% during 2026-2034. In 2026, the market continues to gain momentum, propelled by rising health consciousness, growing demand for convenient, high-protein snacks, increasing adoption of plant-based diets, and an expanding urban population.

Growth in 2026 is further reinforced by a surge in fitness and sports culture, innovations in clean-label ingredients, and improved distribution across retail and e-commerce channels. These dynamics are expected to strengthen the Mexico protein bar market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 59.8 Million
  • Projected Market Size (2034): USD 89.9 Million
  • Growth Rate: CAGR of 4.64% (2026-2034)

Explore Opportunities in the Mexico Protein Bar Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-protein-bar-market/requestsample

Key Growth Drivers and Trends in the Mexico Protein Bar Market

Growth in the Mexico protein bar market is being driven by increasing health and wellness awareness. Consumers are seeking dense, functional snacks that support balanced diets and active lifestyles, and protein bars have become an optimal solution for working professionals, sports enthusiasts, and students looking for convenient, on-the-go nutrition. Valued for protein content as well as long-lasting energy, fullness, and muscle recovery, protein bars are expected to broaden their penetration across urban and semi-urban areas, driving product diversification and flavors suited to local tastes.

One of the leading Mexico protein bar market trends is flavor and ingredient innovation. Producers are experimenting with plant-based proteins, natural sweeteners, and superfood additions, while ingredients such as chocolate, nuts, and fruit blends add sensory appeal. Clean-label, allergen-free, and vegan versions are on the rise, supporting more customized nutrition and helping protein bars become a mainstream healthy snacking option.

Another key factor supporting Mexico protein bar market growth is the expansion of modern retail and e-commerce channels. Grocery stores, convenience stores, and health-oriented retailers are devoting more shelf space to functional snacks, while online marketplaces and delivery subscription platforms make it easy to compare ingredients, nutritional content, and flavors. Together with urbanization, rising disposable incomes, and changing lifestyles, improved distribution networks are expected to underpin market penetration and the launch of new product variants.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33315&flag=C

Mexico Protein Bar Industry Segmentation Insights

Breakup by Source:

  • Plant-Based: Gaining traction with the rising adoption of plant-based diets, with vegan, clean-label, and allergen-free formulations built on plant protein blends.
  • Animal-Based: Remains a key segment, using proteins such as milk protein to deliver high protein content for fitness and muscle recovery.

Breakup by Type:

  • Sports Nutrition Bar: Targets athletes and fitness enthusiasts seeking protein for energy, muscle repair, and recovery, supported by Mexico’s growing fitness and sports culture.
  • Meal Replacement Bar: Serves busy consumers looking for filling, nutritionally balanced options that support weight management and on-the-go eating.
  • Others: Includes additional functional and snack bar formats serving diverse nutrition needs.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Offer broad assortment and growing shelf space for functional snacks, giving consumers greater visibility and choice.
  • Convenience Stores: Support impulse and on-the-go purchases, expanding access to protein bars in urban areas.
  • Specialty Stores: Health-oriented retailers that cater to consumers seeking premium, clean-label, and specialized nutrition products.
  • Online Stores: Growing quickly through e-commerce marketplaces and subscription platforms that make it easy to compare ingredients, nutrition, and flavors.
  • Others: Includes additional retail and direct channels serving protein bar consumers.

Breakup by Region:

  • Northern Mexico: One of the major regional markets, analyzed in the report alongside the country’s other key regions.
  • Central Mexico: A major regional market with large urban populations driving demand for convenient, health-focused snacks.
  • Southern Mexico: A key regional market where expanding retail and online access can support wider availability of protein bars.
  • Others: Covers the remaining regions contributing to protein bar demand.

Key Challenges and Growth Opportunities in the Mexico Protein Bar Market

The Mexico protein bar market faces challenges as consumer expectations rise for quality, taste, and clean-label ingredients, requiring brands to continually refine formulations while managing costs in a competitive category.

Despite these challenges, the market offers considerable growth opportunities. Increased demand for healthier snacks creates room for innovation, new flavors, and plant-based options, and convenient access through modern retail and e-commerce, together with changing consumer attitudes toward functional nutrition, is expected to keep the market growing.

Competitive Landscape

The Mexico protein bar market is competitive, with several brands launching new flavors, functional attributes, and upgraded packaging. New retail growth and online platforms are widening distribution, boosting visibility and availability, while firms concentrate on product differentiation and tactical placement to gain greater market share.

Recent Developments in the Mexico Protein Bar Market

  • June 2025: RXBAR launched its High Protein line along with a new Lemon Honey Cashew Butter flavor in Mexico, featuring 18g of protein and simple, recognizable ingredients. Gluten-free and plant-based, the bars cater to health-conscious consumers.
  • October 2024: Glanbia Nutritionals showcased a range of health and wellness prototypes tailored for the Latin American market at the Food Tech Summit & Expo in Mexico City, including “Prot-Pops”, crunchy extruded protein snacks made with a minimum of 75% milk protein base.
  • October 2024: Axiom Foods announced the expansion of its Vegotein™ N pea protein production to North American facilities, aiming to process over 2,000 metric tons annually and planning to double capacity within 12 months. The expansion includes Mexico, giving local manufacturers a reliable source of high-quality, neutral-tasting pea protein.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Peanut Butter Market Size to Hit USD 2.4 Billion by 2034 | Growth at 3.33% CAGR

United States Peanut Butter Market Size to Hit USD 2.4 Billion by 2034 | Growth at 3.33% CAGR

IMARC Group has recently released a new research study titled “United States Peanut Butter Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Peanut Butter Market Size & Share 2026-2034

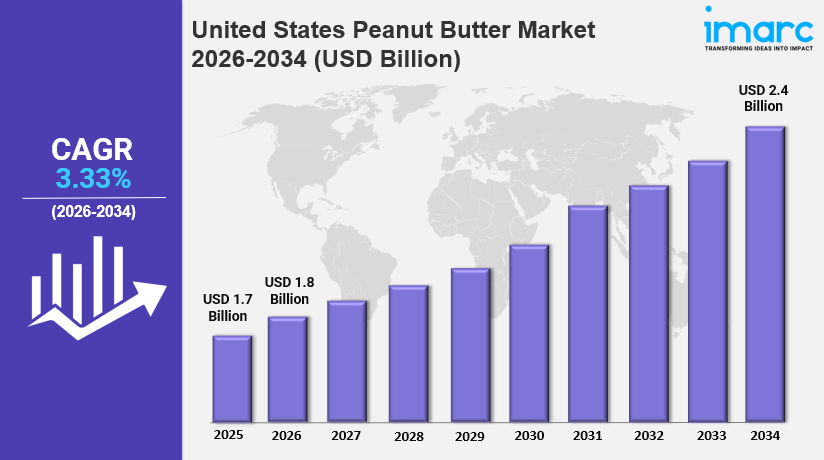
The United States peanut butter market size increased from USD 1.7 Billion in 2025 to USD 1.8 Billion in 2026 and is projected to reach USD 2.4 Billion by 2034, expanding at a CAGR of 3.33% during 2026-2034. In 2026, the market continues to gain momentum, fueled by increasing consumer interest in nutritious, protein-rich foods and the versatility of peanut butter across various meal occasions.

Growth in 2026 is further reinforced by rising demand for clean-label products, innovative packaging formats, and evolving dietary preferences. Strong distribution through retail and online channels, along with expanding usage in both sweet and savory recipes, is expected to strengthen the United States peanut butter market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 1.7 Billion
  • Market Size (2026): USD 1.8 Billion
  • Projected Market Size (2034): USD 2.4 Billion
  • Growth Rate: CAGR of 3.33% (2026-2034)

Explore Opportunities in the United States Peanut Butter Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-peanut-butter-market/requestsample

Key Growth Drivers and Trends in the United States Peanut Butter Market

Growth in the United States peanut butter market is being driven primarily by changing consumer preferences and a heightened emphasis on health and wellness. As individuals look for nutritious and protein-rich food options, peanut butter has become more popular for its natural properties and health benefits. In May 2024, Jif introduced its Peanut Butter & Chocolate Flavored Spread, its first significant flavor innovation in almost ten years, with 50% less sugar than popular hazelnut spreads.

One of the leading United States peanut butter market trends is cross-category integration. Peanut butter is no longer just a traditional breakfast spread; it is a popular ingredient in baked goods, protein bars, smoothies, savory sauces, and ready-to-eat meals, driving demand in both retail and foodservice. In March 2025, Justin’s announced plans to launch new products such as Classic Crunchy Peanut Butter and Peanut Caramel Nougat Chocolate Candy Bars, along with frozen Sandos in collaboration with Rudi’s Rocky Mountain Bakery.

Another key factor supporting United States peanut butter market growth is the shift toward clean-label and natural products, alongside alternative formats that drive convenience-led growth. Shoppers increasingly prefer peanut butter made with only a few ingredients, mainly peanuts and salt, without artificial preservatives, added sugars, or hydrogenated oils, while squeezable pouches, resealable snack packs, and single-serve containers address the need for on-the-go usability and portion control.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=11604&flag=C

United States Peanut Butter Industry Segmentation Insights

Breakup by Product Type:

  • Crunchy Peanut Butter: Valued for its texture and used widely as a spread and ingredient, with steady demand across the South and other regions.
  • Smooth Peanut Butter: The largest product type, holding 59.7% of the market in 2024, driven by its easy spreadability, consistent texture, and appeal across all age groups, including children and busy professionals.
  • Others: Includes flavored and specialty varieties such as organic, high-protein, and chocolate-flavored spreads.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: The leading channel with around 53.3% of market share in 2024, allowing shoppers to compare brands, sizes, and flavors in one place, often with promotional discounts and strong in-store visibility.
  • Convenience Stores: Serve quick, on-the-go purchases, supported by single-serve and resealable formats.
  • Online Stores: A growing channel for niche, organic, and direct-to-consumer brands, widening access to a broader audience.
  • Others: Includes other retail formats and channels through which peanut butter is sold.

Breakup by Region:

  • Northeast: Consistent demand fueled by health-conscious consumers seeking natural and organic options, with urban centers embracing clean-label and specialty varieties.
  • Midwest: A substantial share driven by high household consumption and strong brand loyalty, with a preference for traditional smooth peanut butter and stable demand from bulk purchases at large retailers and discount chains.
  • South: Notable growth bolstered by cultural familiarity and broad consumption across age groups, with steady demand for both smooth and crunchy varieties and rising interest in low-sugar and protein-rich options.
  • West: A vibrant market shaped by lifestyle and health trends, where consumers favor organic, plant-based, and clean-label products that foster niche and premium brands.

Key Challenges and Growth Opportunities in the United States Peanut Butter Market

The United States peanut butter market faces challenges including intense competition among established brands and new entrants, and the growing popularity of cost-effective private-label products in major retail stores. Allergen concerns around peanuts and the need for continuous innovation to maintain customer loyalty also shape brand strategies.

Despite these challenges, the market offers considerable growth opportunities driven by rising health awareness, demand for plant-based protein, and the versatility of peanut butter in various meals. Product innovation, clean-label formulations, convenient ready-to-use formats, and the growth of e-commerce and direct-to-consumer sales are expected to support long-term growth.

Competitive Landscape

The United States peanut butter market is competitive, with both well-established brands and new entrants. Companies strive to attract consumers through high product quality, competitive pricing, innovative packaging, and health-oriented formulations. Niche products such as organic, flavored, and high-protein options help newer brands carve out their own space, while private-label brands are gaining popularity by offering cost-effective choices. Health-focused claims, sustainability messaging, and e-commerce and direct-to-consumer channels are becoming vital for brand positioning and reach.

Recent Developments in the United States Peanut Butter Market

  • May 2025: Ferrero announced its first-ever Nutella flavor variation, Nutella Peanut, blending peanut butter with its classic hazelnut spread and set for 2026 release. Ferrero invested USD 75 Million to expand its Illinois plant, adding the first U.S. Nutella production line.
  • March 2025: Drumstick launched its first-ever peanut butter sundae cones nationwide with the “We Love Peanut Butter” 8-pack, featuring peanut butter and chocolate peanut butter flavors.
  • February 2025: Honey Stinger introduced a new range of organic peanut butter energy waffles in three flavors: plain peanut butter, peanut butter chocolate, and peanut butter strawberry.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Electric Bus Market Size, Share & Forecast Report 2034

United States Electric Bus Market Size, Share & Forecast Report 2034

IMARC Group has recently released a new research study titled “United States Electric Bus Market Report by Propulsion Type (Battery Electric Vehicle (BEV), Fuel Cell Electric Vehicle (FCEV), Plug-in Hybrid Electric Vehicle (PHEV)), Battery Type (Lithium-ion Battery, Nickel-Metal Hydride Battery (NiMH), and Others), Length (Less than 9 Meters, 9-14 Meters, Above 14 Meters), Range (Less than 200 Miles, More than 200 Miles), Battery Capacity (Up to 400 kWh, Above 400 kWh), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Electric Bus Market Size & Share 2026-2034

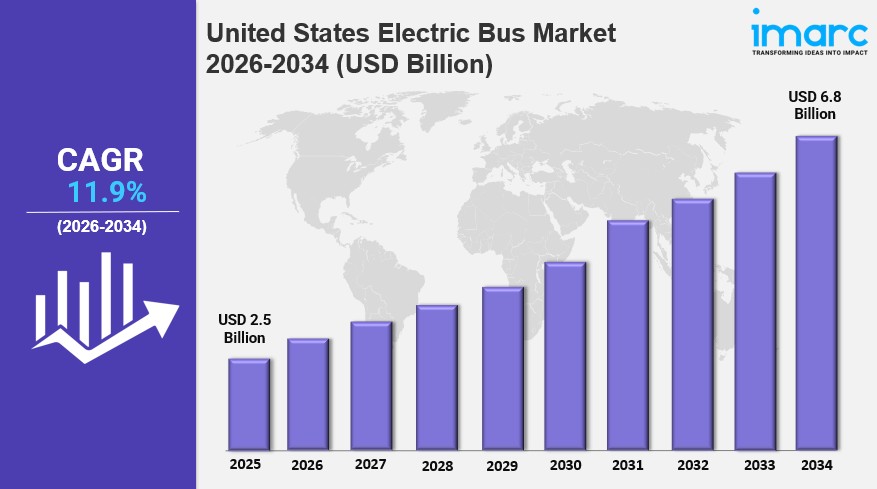
The United States electric bus market size reached USD 2.5 Billion in 2025 and is projected to reach USD 6.8 Billion by 2034, expanding at a CAGR of 11.9% during 2026-2034. In 2026, the market continues to gain momentum, propelled by growing environmental concerns, stricter emission control regulations, expanding charging infrastructure, and continuous advances in battery and electric drive technologies.

Growth in 2026 is further reinforced by government initiatives and subsidies for zero-emission buses, falling lithium-ion battery costs, and the lower operating and maintenance costs of electric buses compared with diesel models. These dynamics are expected to strengthen the United States electric bus market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 2.5 Billion
  • Projected Market Size (2034): USD 6.8 Billion
  • Growth Rate: CAGR of 11.9% (2026-2034)

Explore Opportunities in the United States Electric Bus Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-electric-bus-market/requestsample

Key Growth Drivers and Trends in the United States Electric Bus Market

Growth in the United States electric bus market is being driven by the need to curb greenhouse gas emissions and urban air pollution from diesel buses. According to Environment America, replacing all diesel-powered transit buses in the country with electric buses could reduce greenhouse gas emissions by more than 2 million tons per year. Regulatory and funding support is reinforcing this shift: in March 2024, the U.S. Environmental Protection Agency released a final rule setting stricter greenhouse gas limits for heavy-duty vehicles for model years 2028-2032, and in November 2023, the Federal Highway Administration announced USD 5 Billion under its Low or No Emission Vehicle Program to replace transit buses with zero-emission models.

One of the leading United States electric bus market trends is the growth of charging infrastructure and grid technology. The United States reached nearly 128,000 EV charging stations in 2022, while fast-charging and vehicle-to-grid (V2G) technologies are improving operational efficiency. In July 2023, Blue Bird launched its next-generation Vision electric school bus supporting 80 kW fast charging, and in May 2024, Oakland Unified School District became the first major U.S. school district to fully electrify its school bus system with V2G technology, using a fleet of 74 electric buses delivered by Zum.

Another key factor supporting United States electric bus market growth is the adoption of hydrogen fuel cell mobility for long-range, high-demand routes. According to Calstart, about 6,100 new full-size zero-emission transit buses entered service in the United States in 2023, a 12% increase over 2022, while the number of fuel cell electric buses surged by more than 75%. In April 2024, BAE Systems announced it would supply its next-generation electric drive system to GILLIG for a new hydrogen fuel cell bus line.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=6239&flag=C

United States Electric Bus Industry Segmentation Insights

Breakup by Propulsion Type:

  • Battery Electric Vehicle (BEV): Powered entirely by batteries recharged from the grid, producing zero tailpipe emissions and playing a key role in reducing urban air pollution.
  • Fuel Cell Electric Vehicle (FCEV): Uses hydrogen fuel cells to generate electricity, emitting only water vapor and suiting long-range and high-demand routes.
  • Plug-in Hybrid Electric Vehicle (PHEV): Combines an internal combustion engine with a rechargeable battery, offering flexibility for longer ranges and reducing range anxiety.

Breakup by Battery Type:

  • Lithium-ion Battery: Preferred for its high energy density, lighter weight, and compact size, enabling longer distances on a single charge.
  • Nickel-Metal Hydride Battery (NiMH): Offers stability and safety with lower risk of thermal runaway, though with lower energy density and shorter range than lithium-ion.
  • Others: Includes additional battery chemistries serving specialized needs.

Breakup by Length:

  • Less than 9 Meters: Smaller buses suited to inner-city routes, narrow streets, shuttle services, and last-mile connectivity.
  • 9-14 Meters: The standard city bus for most U.S. public transit systems, serving regular urban and suburban routes with moderate passenger volumes.
  • Above 14 Meters: Designed for high-capacity routes, including busy urban corridors, intercity services, and Bus Rapid Transit (BRT) systems.

Breakup by Range:

  • Less than 200 Miles: Typically used for urban routes with frequent stops, including inner-city transit, school buses, and shuttle services.
  • More than 200 Miles: Used for intercity and longer urban routes and BRT systems, handling higher daily mileage with less frequent recharging.

Breakup by Battery Capacity:

  • Up to 400 kWh: Used for shorter urban and suburban routes, with lower purchase and operating costs and less charging infrastructure investment.
  • Above 400 kWh: Supports longer routes and higher-capacity needs, offering greater operational flexibility for intercity and BRT applications.

Breakup by Region:

  • Northeast: Supported by aggressive clean energy policies and incentives, including subsidies, tax credits, and grants for transitioning to electric buses.
  • Midwest: Driven by government initiatives, public awareness, and public-private partnerships supporting zero-emission transit and school bus deployment.
  • South: Shaped by state-level policies and regulations on clean energy and transportation infrastructure that influence adoption rates.
  • West: Led by states such as California, which have numerous air quality and climate change mitigation policies driving the shift to electric buses.

Key Challenges and Growth Opportunities in the United States Electric Bus Market

The United States electric bus market faces challenges including high initial costs, inadequate charging infrastructure, battery degradation, and the significant time required to charge buses.

Despite these challenges, the market offers considerable growth opportunities as ongoing research and development in battery technology improves energy density, charging speed, and overall efficiency, which are expected to lower costs and enhance performance over time. Lower operating costs, reduced maintenance, and lower fuel costs compared with diesel buses continue to encourage transit agencies to shift to electric fleets.

Competitive Landscape

The United States electric bus market is competitive, with bus manufacturers such as Blue Bird and GILLIG, electric drive suppliers such as BAE Systems, and service providers such as Zum advancing zero-emission portfolios for transit and school fleets. Companies are investing in battery technology, fast charging, V2G capabilities, and hydrogen fuel cell platforms, while partnerships with transit agencies and school districts continue to shape the competitive environment.

Recent Developments in the United States Electric Bus Market

  • May 2024: The Metropolitan Transportation Authority (MTA) launched new electric buses on Queens, Brooklyn, and Staten Island routes, fitted with charging stations to ensure sufficient power for charging.
  • May 2024: Zum delivered a fleet of 74 electric school buses with bidirectional chargers to Oakland Unified School District, which became the first major U.S. school district to fully electrify its school bus system with V2G technology.
  • April 2024: The U.S. Environmental Protection Agency (EPA) announced the commencement of its 2024 Clean Heavy-Duty Vehicles Grant Program to assist the transition of school buses, trucks, and other heavy-duty vehicles to zero-emission models.
  • April 2024: BAE Systems announced it would provide its next-generation electric drive system to GILLIG for use in a new hydrogen fuel cell bus line.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Pasta Sauce Market 2026: Size, Share, Industry Overview and Forecast to 2034

United States Pasta Sauce Market 2026: Size, Share, Industry Overview and Forecast to 2034

IMARC Group has recently released a report titled “United States Pasta Sauce Market Report by Product Type (Tomato-Based Sauces, Pesto-Based Sauces, Alfredo-Based Sauces), Packaging Type (Glass Bottles, PET, Cans, Pouches, Cartons), Distribution Channel (Direct, Indirect), and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Pasta Sauce Market Size and Forecast 2026–2034

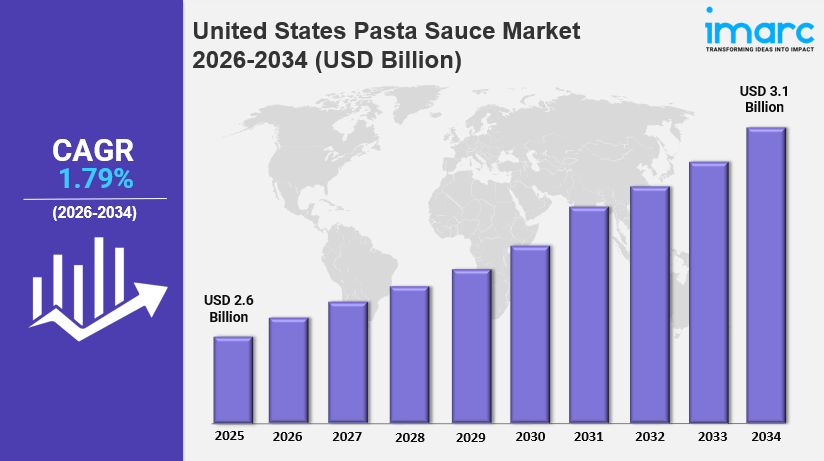
The United States pasta sauce market size reached USD 2.6 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 3.1 Billion by 2034, exhibiting a growth rate (CAGR) of 1.79% during 2026-2034. The market is growing due to high consumption of ready-to-eat (RTE) food products like pasta, a large number of cafes, restaurants, and quick-service restaurants (QSRs) using pasta sauce in their menus, and considerable reliance on online shopping channels. Growing demand for convenient meal options and upscale, restaurant-quality flavors is further supporting market share.

In 2026, the United States pasta sauce market growth is being fueled by rising demand for low-sugar, globally inspired, and plant-based pasta sauces, health-focused formulations using organic and natural ingredients, and the expansion of e-commerce and direct-to-consumer models. Continued product innovation, including new flavors and clean-label launches, is further broadening consumer choice and intensifying competition between established brands and emerging gourmet and health-oriented players.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 2.6 Billion
  • Projected Size (2034): USD 3.1 Billion
  • Growth Rate: CAGR of 1.79%

Explore Opportunities in the United States Pasta Sauce Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-pasta-sauce-market/requestsample

United States Pasta Sauce Market Growth: Key Trends and Market Insights

The United States pasta sauce market growth is supported by high consumption of RTE foods such as pasta, driven by hectic lifestyles. A considerable number of cafes, restaurants, and QSRs use pasta sauce to offer a variety of pasta dishes on their menus, strengthening market growth. Significant reliance on online shopping channels, which offer convenience, doorstep delivery, and secure payment methods, is also influencing the market positively.

Key United States pasta sauce market trends include increasing preference for economical meal options. Pasta and sauce offer a cost-effective meal for families and individuals on a budget, using low-cost ingredients such as canned tomatoes, herbs, and spices, and the sauce can be stored and used across multiple meals. The influence of celebrity chefs and food media is another major driver, as cooking shows, food blogs, and social media platforms expose consumers to recipe ideas and feature pasta sauce as a pantry staple.

The United States pasta sauce market growth is also being shaped by demand for low-sugar, globally inspired, and plant-based sauces, as brands use e-commerce and direct-to-consumer models and introduce new flavors to meet changing dietary requirements. Growing launches of premium and organic products, such as Carbone Fine Food’s five new sauce flavors and Bionaturae’s first line of certified organic sauces, are expected to create opportunities for brands through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2642&flag=C

United States Pasta Sauce Market Segmentation Analysis

The United States pasta sauce market is segmented by product type, packaging type, distribution channel, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Product Type

  • Tomato-Based Sauces: The largest segment and most widely used product type, including traditional, marinara, meat, mushroom, roasted garlic, cheese, and tomato and basil sauces.
  • Pesto-Based Sauces: Prepared with fresh herbs, nuts, cheese, garlic, and olive oil, including traditional basil pesto and sun-dried tomato pesto varieties.
  • Alfredo-Based Sauces: Rich, creamy sauces made with butter, cream, and cheese, including traditional, garlic, and cheese alfredo varieties.

Breakup by Packaging Type

  • Glass Bottles: Account for the largest market share, preferred for their classic look, use in premium and gourmet sauces, and ability to preserve flavor and quality.
  • PET: Lightweight, recyclable, and shatterproof, with good barrier properties that help maintain freshness.
  • Cans: A widely used, durable format suited to long shelf life and easy storage.
  • Pouches: Growing in popularity as flexible packaging that is space-efficient, lightweight, resealable, and convenient for portion control.
  • Cartons: An alternative packaging format supporting convenience and sustainability-focused brands.

Breakup by Distribution Channel

  • Direct: Manufacturers sell directly to consumers through their own websites, company-owned stores, farmers markets, and food fairs.
  • Indirect: Holds the largest market share, covering store-based retailing, supermarkets, specialty stores, convenience stores, and online retailing.

Breakup by Region

  • Northeast: A key regional market for pasta sauce consumption across the United States.
  • Midwest: A key regional market supported by household demand for economical, convenient meal options.
  • South: A key regional market supported by broad retail distribution and foodservice demand.
  • West: A key regional market where demand for premium, organic, and globally inspired sauces is growing.

Key Challenges and Growth Opportunities in the United States Pasta Sauce Market

The United States pasta sauce market faces several challenges that could affect its growth, including changing raw material prices and increasing competition from private-label products, which put pressure on pricing and margins for branded manufacturers.

Despite these challenges, the market offers significant growth opportunities driven by functional sauces, clean-label brands, and niche segments such as gluten-free and high-protein versions that address increasing consumer health needs. Continued growth of e-commerce and direct-to-consumer models, along with new flavors and plant-based and low-sugar offerings, is expected to further support market expansion. Companies investing in R&D, flavor diversification, and eco-friendly packaging will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The United States pasta sauce market features a competitive landscape in which established players compete with emerging gourmet and health-oriented brands across mainstream and premium retail channels. The report provides a comprehensive analysis of the competitive landscape, including detailed profiles of all major companies operating in the space.

Key players are using high pressure processing technology to preserve and sterilize products, maintaining nutritional value and flavor while extending shelf life, and are adopting advanced machinery and robotic systems for ingredient mixing, sauce cooking, filling, labeling, and packaging to improve efficiency and consistency. Smart packaging technologies, such as intelligent labels that monitor freshness and temperature or provide recipe suggestions, are also supporting market growth. Companies continue to invest in R&D, flavor diversification, and eco-friendly packaging to remain competitive.

Latest News and Developments

  • February 2025: Carbone Fine Food extended its line of offerings with five new pasta sauce flavors in the United States: Sweet Pepper & Onion, Mediterranean Marinara, Black Truffle Alfredo, Mac & Cheese Alfredo, and Lemon Pepper Alfredo, designed to bring upscale Italian-American cooking into home kitchens across the country.
  • January 2025: Bionaturae debuted its first-ever line of certified organic pasta sauces in the U.S. The gluten-free, glyphosate-free, and Non-GMO sauces come in Marinara, Arrabbiata, and Tomato & Basil varieties, designed to raise the bar in clean-label choices for premium pasta sauces.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Airway Management Devices Market Size to Hit USD 1,011.3 Million by 2034 | Growth at 5.66% CAGR

United States Airway Management Devices Market Size to Hit USD 1,011.3 Million by 2034 | Growth at 5.66% CAGR

IMARC Group has recently released a report titled “United States Airway Management Devices Market Report by Product (Supraglottic Devices, Infraglottic Devices, Resuscitators, Laryngoscopes, and Others), Patient Type (Adult, Pediatric Patient/Neonates), Application (Anesthesia, Emergency Medicine, and Others), End Use (Hospitals, Homecare, and Others), and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Airway Management Devices Market Size and Forecast 2026–2034

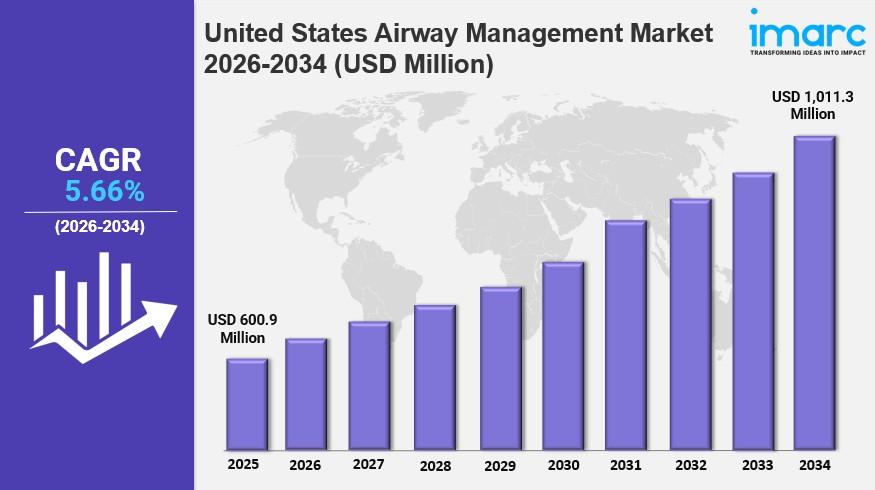
The United States airway management devices market size reached USD 600.9 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 1,011.3 Million by 2034, exhibiting a growth rate (CAGR) of 5.66% during 2026-2034. The market is growing due to the rising focus on addressing respiratory disorders, technological advancements, and the growing adoption of minimally invasive approaches across the country. Increasing awareness and diagnosis of conditions such as chronic obstructive pulmonary disease (COPD) and obstructive sleep apnea is further expanding demand for advanced airway management devices.

In 2026, the United States airway management devices market share is being supported by the integration of smart features, improved materials, and ergonomic designs that enhance patient comfort and clinical efficacy. The development of novel airway devices that minimize patient discomfort, combined with the widespread adoption of telehealth and remote patient monitoring solutions, is expected to further support market expansion throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 600.9 Million
  • Projected Size (2034): USD 1,011.3 Million
  • Growth Rate: CAGR of 5.66%

Explore Opportunities in the United States Airway Management Devices Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-airway-management-devices-market/requestsample

United States Airway Management Devices Market Growth: Key Trends and Market Insights

Airway management devices play a crucial role in maintaining or restoring ventilation in patients, supporting the assessment, planning, and implementation of medical procedures for those experiencing respiratory failure or acute obstruction. Commonly used approaches include supraglottic airway devices (SADs), tracheal intubation, transtracheal access, and airway clearance techniques, all designed to keep the upper airway open, protect the lungs from injury, and facilitate gas exchange.

Key United States airway management devices market trends include the rising incidence of respiratory disorders, including COPD and obstructive sleep apnea. Increasing awareness and diagnosis of these ailments is contributing to growing demand for advanced airway management devices across the country. Technological advancements, including the integration of smart features, improved materials, and ergonomic designs, are acting as significant growth-inducing factors.

The United States airway management devices market growth is also supported by the rising emphasis on minimally invasive techniques, with novel devices that offer effective airway support while minimizing patient discomfort gaining traction. This trend aligns with the broader healthcare focus on improving patient outcomes and experiences. Furthermore, the widespread adoption of telehealth solutions and remote patient monitoring is expected to create opportunities for device manufacturers through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=21056&flag=C

United States Airway Management Devices Market Segmentation Analysis

The United States airway management devices market is segmented by product, patient type, application, end use, and region, offering a comprehensive view of clinical demand, care settings, and regional dynamics across the country.

Breakup by Product

  • Supraglottic Devices: Includes oropharyngeal devices, nasopharyngeal devices, laryngeal airway devices, and others designed to keep the upper airway open.
  • Infraglottic Devices: Includes endotracheal tubes, tracheostomy tubes, and others used for tracheal intubation and securing the airway.
  • Resuscitators: Supports ventilation for patients experiencing respiratory failure in emergency and clinical settings.
  • Laryngoscopes: Used to visualize the airway during intubation, benefiting from technological advancements and improved designs.
  • Others: Includes additional airway management devices benefiting from ongoing product innovation.

Breakup by Patient Type

  • Adult: Driven by the rising incidence of respiratory disorders such as COPD and obstructive sleep apnea.
  • Pediatric Patient/Neonates: A specialized segment requiring devices designed for smaller airways and focused on patient comfort and clinical efficacy.

Breakup by Application

  • Anesthesia: Relies on airway devices to maintain ventilation and protect the lungs during procedures.
  • Emergency Medicine: Uses airway devices to treat patients with respiratory failure or acute obstruction.
  • Others: Includes additional clinical applications requiring airway support and ventilation.

Breakup by End Use

  • Hospitals: Core care setting for airway management across anesthesia, emergency, and critical care.
  • Homecare: Supported by the adoption of telehealth solutions and remote patient monitoring.
  • Others: Includes additional healthcare facilities and care settings using airway management devices.

Breakup by Region

  • Northeast: Covers a regional healthcare market with demand for advanced airway management devices.
  • Midwest: Covers a regional healthcare market supported by growing awareness and diagnosis of respiratory disorders.
  • South: Covers a regional healthcare market with demand for devices across hospital and homecare settings.
  • West: Covers a regional healthcare market shaped by technological advancements and adoption of minimally invasive approaches.

Key Challenges and Growth Opportunities in the United States Airway Management Devices Market

The United States airway management devices market faces challenges typical of the medical device sector, including the need to continually develop devices that improve clinical efficacy while minimizing patient discomfort, and the need to integrate smart features and improved materials without compromising ergonomics and ease of use.

Despite these challenges, the market offers significant growth opportunities driven by the rising focus on respiratory disorders such as COPD and obstructive sleep apnea, technological advancements, and growing adoption of minimally invasive approaches. The widespread adoption of telehealth solutions and remote patient monitoring is expected to further support market expansion. Companies investing in smart features, improved materials, and patient-friendly designs will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The United States airway management devices market features a dynamic competitive landscape comprising medical device manufacturers offering supraglottic and infraglottic devices, resuscitators, laryngoscopes, and related products across hospital and homecare settings. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.

Market participants are investing in product innovation, improved materials, and ergonomic designs to strengthen their positioning and meet growing clinical demand. Companies continue to focus on minimally invasive solutions and patient comfort to remain competitive in the evolving United States airway management devices market.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
U.S. Pet Insurance Market Size Growth, Industry Report 2034

U.S. Pet Insurance Market Size Growth, Industry Report 2034

IMARC Group has recently released a new research study titled “U.S. Pet Insurance Market Size, Share, Trends and Forecast by Policy, Animal, Provider, and Region, 2026-2034”, offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.

U.S. Pet Insurance Market Outlook 2034: Opportunities for Insurers, Veterinary Networks, and Pet Care Brands

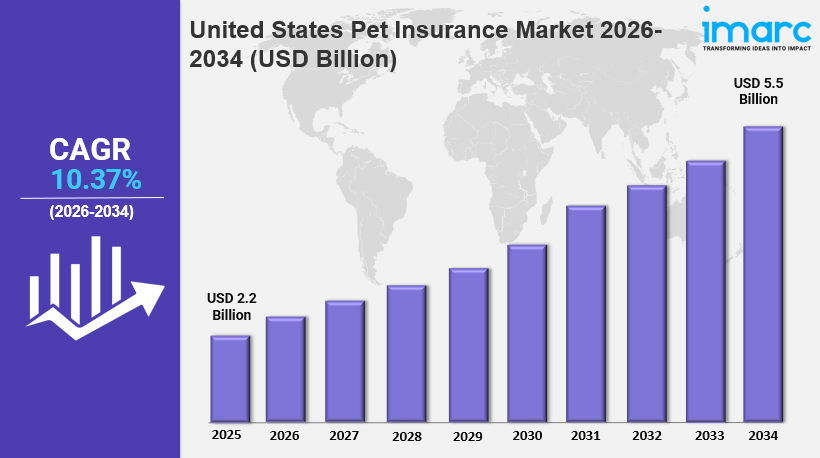
The U.S. pet insurance market size is on a strong growth trajectory, valued at USD 2.2 Billion in 2025 and projected to reach USD 5.5 Billion by 2034. This expansion, characterized by a compound annual growth rate (CAGR) of 10.37% from 2026 to 2034, is supported by increasing pet ownership, rising veterinary costs, and heightened awareness of pet health. Insurers are broadening coverage options and adopting digital platforms, while customized plans, wellness coverage, and telehealth integration are encouraging wider adoption across the country. For insurers, veterinary partners, and pet care brands, understanding the dynamics of this market is crucial.

Key Market Statistics at a Glance

Base Year: 2025

Historical Years: 2020–2025

Forecast Period: 2026–2034

Market Size (2025): USD 2.2 Billion

Projected Size (2034): USD 5.5 Billion

Growth Rate: CAGR of 10.37%

Explore Growth Opportunities in the U.S. Pet Insurance Market Grab Your Sample Report for Evaluation: https://www.imarcgroup.com/united-states-pet-insurance-market/requestsample

How Rising Pet Ownership and Digital Innovation Are Shaping the U.S. Pet Insurance Market

More households now consider pets to be family members, which is raising the need for financial security against unexpected veterinary expenses. According to industry reports, 66% of U.S. households (86.9 million) owned pets in 2024, with millennials leading ownership at 33%, followed by Gen X at 25%. Dogs (65.1 million) and cats (46.5 million) remain the most popular pets. This shift is steadily lifting U.S. pet insurance market demand, as owners look to manage costly surgeries, advanced treatments, and chronic conditions such as diabetes and arthritis. Simplified insurance processes and digital tools are making policies more accessible to younger demographics, supporting long-term U.S. pet insurance market growth.

Key U.S. Pet Insurance Market Trends:

  • Rising Pet Ownership and Expenditure: Pet owners are dedicating larger budgets to healthcare, nutrition, and wellness. In 2024, 86.8% of dog owners reported regular veterinarian visits, with average veterinary costs of $214 for dogs and $138 for cats.
  • Product Diversification and Customization: Insurers are offering accident-only, illness, and comprehensive plans with wellness and preventive care, along with add-ons such as dental care, alternative therapies, and hereditary condition coverage.
  • Integration with the Broader Pet Care Ecosystem: Partnerships with veterinary clinics and retailers, along with bundled wellness plans, are placing insurance directly where pet owners shop and seek care.

A detailed U.S. pet insurance market analysis shows that digital claims, direct reimbursement, and flexible plan design are becoming central to customer acquisition and retention.

U.S. Pet Insurance Market: Key Growth Drivers and Strategic Insights for Businesses

Several factors are shaping the expansion of pet insurance in the United States. Understanding them is essential for businesses planning to invest, partner, or launch new offerings, and for tracking U.S. pet insurance market trends as they evolve through 2034.

Key Growth Drivers:

  1. Increasing Pet Ownership: Rising pet adoption, including post-pandemic adoption, is expanding the base of potential policyholders.
  2. Rising Veterinary Costs: Advanced veterinary care, including expensive surgeries and treatments, is encouraging owners to invest in insurance and lifting U.S. pet insurance market demand.
  3. Prevalence of Chronic Conditions: Growing diagnoses of diabetes, arthritis, and kidney disease in pets are pushing demand for comprehensive coverage.
  4. Digitalization and Preventive Care Focus: Simplified, app-based policy management and a greater emphasis on preventive care are broadening adoption and accelerating U.S. pet insurance market growth.

Strategic Insights:

  • Invest in Customization: Flexible deductibles, reimbursement rates, and add-on riders help insurers match diverse budgets and pet needs.
  • Build Ecosystem Partnerships: Collaborations with veterinary clinics, retailers, and employers improve awareness, trust, and convenience, helping insurers defend U.S. pet insurance market share.
  • Prioritize Data-Led Planning: Segment-level U.S. pet insurance market analysis helps stakeholders identify the policy types, animals, and regions with the strongest potential.

Why Insurers and Partners Are Investing in the U.S. Pet Insurance Market

Competition for U.S. pet insurance market share is intensifying, with insurers differentiating through customizable coverage, flexible pricing, and a better customer experience. Strategic moves such as Chubb’s April 2024 acquisition of Healthy Paws from Aon, and Independence Pet Holdings’ March 2024 acquisition of Pets Best from Synchrony, show how seriously established players are treating this opportunity. With the U.S. pet insurance market size expected to more than double between 2025 and 2034, the incentive to invest is clear.

Reasons for Investment:

  • Digital Convenience: Mobile apps and streamlined claims processing improve customer experience and retention. In October 2024, Synchrony linked CareCredit and Pets Best so claims can be reimbursed directly to the CareCredit card.
  • Product Differentiation: Insurers are responding to U.S. pet insurance market trends such as wellness coverage, telehealth integration, and employer-offered voluntary benefits, as seen in Unum’s May 2024 launch of Unum Pet Insurance provided by Nationwide.
  • Customer Loyalty and Reach: Co-branded offerings, such as the January 2024 Petco and Nationwide plan, expand reach while encouraging holistic pet health management and sustained U.S. pet insurance market demand.

U.S. Pet Insurance Market Segmentation:

The report offers a segment-wise U.S. pet insurance market analysis, with forecasts from 2026-2034 across policy, animal, provider, and region.

Policy Insights:

  • Illnesses and Accidents
  • Chronic Conditions
  • Others

Animal Insights:

  • Dog
  • Cat
  • Others

Provider Insights:

  • Public
  • Private

Regional Insights:

  • Northeast
  • Midwest
  • South
  • West

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20400&flag=C

Leading Companies in the U.S. Pet Insurance Market

The market is dominated by private providers, and the following players are positioning themselves to capture U.S. pet insurance market share and benefit from long-term U.S. pet insurance market growth.

  • Nationwide – Offers pet insurance through partnerships including Petco and Unum, with plans covering accidents, illnesses, and wellness care.
  • Trupanion – Provides pet insurance with a strong Northeast presence, supported by partnerships with local veterinary clinics and pet retailers.
  • Petplan – Known in the Midwest for coverage focused on accidents and illnesses common in active, working, and family pets.
  • ASPCA Pet Health Insurance – Offers accident and illness coverage plans, with community-focused marketing and local veterinarian partnerships.
  • Healthy Paws – A leading pet insurance provider acquired by Chubb from Aon plc in April 2024 to strengthen its presence in the market.
  • Pets Best (Independence Pet Holdings, Inc.) – Pet insurance brand acquired by Independence Pet Holdings from Synchrony in March 2024, integrated with CareCredit reimbursement.

Author IMARC Group

IMARC Group is a leading global management consulting firm providing comprehensive market research, feasibility studies, and strategic advisory services. The firm supports organizations worldwide in identifying growth opportunities, mitigating risks, and making informed business decisions across industries.

Contact Us
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

Mexico Circuit Breaker Market Size, Overview, Industry Growth Rate, Research Report 2026-2034

Mexico Circuit Breaker Market Size, Overview, Industry Growth Rate, Research Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Circuit Breaker Market Size, Share, Trends and Forecast by Product Type, Voltage, Technology, End-Use, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Circuit Breaker Market Size & Share 2026-2034

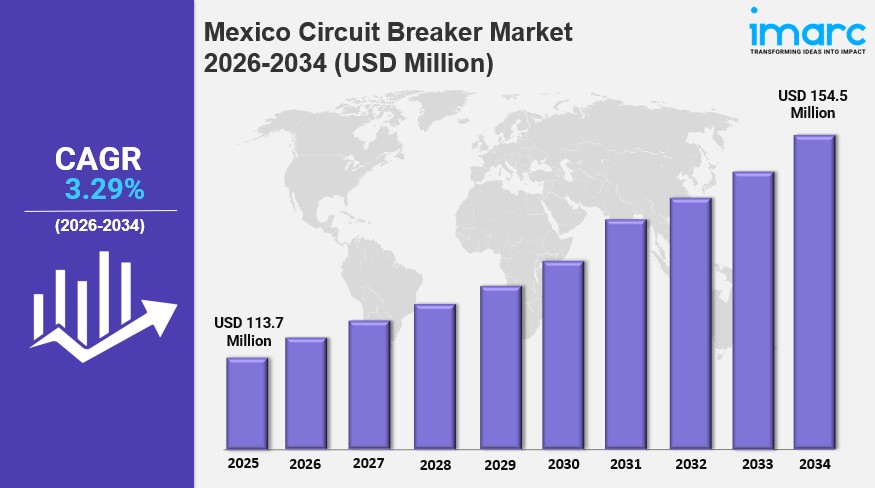
The Mexico circuit breaker market size reached USD 113.7 Million in 2025 and is projected to reach USD 154.5 Million by 2034, expanding at a CAGR of 3.29% during 2026-2034. In 2026, the market continues to gain momentum, propelled by the upgrading of the country’s power infrastructure, rising foreign direct investment (FDI) across industries such as automotive, electronics, pharmaceuticals, and logistics, and the increasing integration of renewable energy projects, especially solar and wind power.

Growth in 2026 is further reinforced by grid modernization efforts, expanding industrial and commercial construction under nearshoring, and rising demand for reliable protection and control systems across transmission, distribution, and generation. These dynamics are expected to strengthen the Mexico circuit breaker market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 113.7 Million
  • Projected Market Size (2034): USD 154.5 Million
  • Growth Rate: CAGR of 3.29% (2026-2034)

Explore Opportunities in the Mexico Circuit Breaker Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-circuit-breaker-market/requestsample

Key Growth Drivers and Trends in the Mexico Circuit Breaker Market

Growth in the Mexico circuit breaker market is being driven by the rapid expansion of power infrastructure and grid modernization. The Federal Electricity Commission (CFE) is advancing projects to strengthen the grid, extend transmission lines, and incorporate renewable energy sources, while rising electricity consumption in cities and industrial areas increases demand for dependable protection and control systems. Substation upgrades and smart grid deployment call for advanced circuit protection devices with remote monitoring and automatic fault response, and incentives for rural electrification and energy reliability further support demand. On March 18, 2025, President Claudia Sheinbaum signed a comprehensive energy reform package that adds eight new secondary laws and reforms three existing ones, strengthening the role of state-owned firms in the power industry.

One of the leading Mexico circuit breaker market trends is the growth of industrial and commercial construction. FDI across automotive, electronics, pharmaceuticals, and logistics, along with Mexico’s position as a production base under nearshoring, is raising the need for strong electrical infrastructure. Manufacturing plants, data centers, shopping centers, and office buildings require high-end circuit protection to ensure safety and continuity, and compliance with safety standards and sustainability goals is encouraging energy-efficient and eco-friendly circuit protection products.

Another key factor supporting Mexico circuit breaker market growth is the rising integration of renewable energy projects. With rich natural resources and favorable climate conditions, Mexico is becoming a prime location for solar and wind investment, supported by government incentives and reforms such as the Energy Transition Law. Renewable systems need circuit breakers that can handle varying loads and protect high-voltage transmission lines and inverter-based systems, particularly given the power fluctuations and grid instability common in these systems, and distributed energy resources (DERs) add to demand for high-reliability breakers. IMARC Group projects Mexico’s wind power market to reach 8.50 Gigawatt by 2033.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33121&flag=C

Mexico Circuit Breaker Industry Segmentation Insights

Breakup by Product Type:

  • Indoor Circuit Breakers: Installed within buildings, switchgear rooms, and substations, serving industrial plants, commercial facilities, and enclosed power distribution systems.
  • Outdoor Circuit Breakers: Designed to withstand weather and environmental exposure, used in outdoor substations, transmission lines, and renewable energy installations.

Breakup by Voltage:

  • Low Voltage: Protects final distribution circuits in buildings, commercial facilities, and industrial equipment.
  • Medium Voltage: Used in distribution networks, industrial plants, and renewable energy collection systems.
  • High Voltage: Used in transmission networks and large substations to protect high-voltage lines and equipment.

Breakup by Technology:

  • Air: Uses air as the arc-quenching medium, commonly applied in low-voltage protection.
  • Vacuum: Interrupts the arc in a vacuum chamber, widely used in medium-voltage applications for its compact, low-maintenance design.
  • Oil: Uses oil as the arc-quenching and insulating medium, found largely in older installations.
  • SF6: Uses sulfur hexafluoride gas for arc interruption, commonly used in high-voltage applications.

Breakup by End-Use:

  • Transmission and Distribution: Supports grid expansion, substation upgrades, and smart grid deployment as CFE works to strengthen and extend the network.
  • Renewable: Driven by growing solar and wind capacity that requires breakers able to manage variable loads and protect inverter-based systems and high-voltage lines.
  • Power Generation: Covers circuit protection for generating facilities to safeguard equipment and maintain continuity of supply.
  • Railways: Covers protection and control of electrical systems used in rail transport and related infrastructure.

Breakup by Region:

  • Northern Mexico: A major industrial and manufacturing region, with demand linked to nearshoring-driven plants and logistics facilities.
  • Central Mexico: A large demand center combining dense urban populations, commercial buildings, and industrial activity.
  • Southern Mexico: Demand supported by rural electrification, energy reliability initiatives, and renewable energy development.
  • Others: Covers the remaining regions of Mexico not included in the three main regional groupings.

Key Challenges and Growth Opportunities in the Mexico Circuit Breaker Market

The Mexico circuit breaker market is shaped by the need to keep pace with evolving safety standards and technology requirements, including remote monitoring, automatic fault response, and energy-efficient, eco-friendly designs. Suppliers must also adapt to changes in the energy policy and regulatory landscape as the power sector evolves.

Despite this, the market offers considerable growth opportunities driven by grid modernization, rising electricity demand, nearshoring-led industrial and commercial construction, and the rapid growth of solar and wind projects. Demand for sophisticated and eco-certified circuit breakers in industrial and commercial applications is expected to create substantial opportunities for long-term growth in the Mexico circuit breaker market.

Competitive Landscape

The Mexico circuit breaker market features competition among suppliers serving utilities, industrial users, commercial builders, and renewable energy developers. IMARC’s report analyzes the competitive landscape in detail, including market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant, along with detailed profiles of the major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Software Market 2026: Size, Share, Industry Overview and Forecast to 2034

United States Software Market 2026: Size, Share, Industry Overview and Forecast to 2034

IMARC Group has recently released a new research study titled “United States Software Market Report by Type (Application Software, System Infrastructure Software, Development and Deployment Software, Productivity Software), Deployment Mode (On-premises, Cloud-based), Enterprise Size (Small and Medium-sized Enterprises, Large Enterprises), Industry Vertical (IT and Telecom, BFSI, Retail, Government/Public Sector, Energy and Utilities, Healthcare, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Software Market Size & Share 2026-2034

The United States software market size reached USD 173,603.7 Million (approximately USD 173.6 Billion) in 2025 and is projected to reach USD 246,675.6 Million (approximately USD 246.7 Billion) by 2034, expanding at a CAGR of 3.86% during 2026-2034. In 2026, the market continues to gain momentum, propelled by growing demand for remote healthcare, patient management, and medical data analysis, the increasing shift from on-premises software to cloud-based services, and the rising popularity of low-code and no-code development platforms.

Growth in 2026 is further reinforced by digital transformation, cloud computing adoption, rising demand for automation, and continued investment in artificial intelligence, which together drive enterprise modernization and underpin scalable, intelligent technology infrastructures. These dynamics are expected to strengthen the United States software market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 173,603.7 Million
  • Projected Market Size (2034): USD 246,675.6 Million
  • Growth Rate: CAGR of 3.86% (2026-2034)

Explore Opportunities in the United States Software Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-software-market/requestsample

Key Growth Drivers and Trends in the United States Software Market

Growth in the United States software market is being driven by the expansion of cloud-native solutions. Technologies such as containerization, microservices, and serverless computing allow companies to build scalable, elastic applications suited to fast-changing environments, and organizations across industries are investing in platforms that can deploy, observe, and manage workloads in real time. Software vendors are responding with cloud-first offerings, supported by cloud-based development environments and DevOps practices that improve operational agility, lower costs, and shorten innovation cycles.

One of the leading United States software market trends is the integration of artificial intelligence into mainstream software platforms. AI-based capabilities, from predictive analytics to natural language processing and machine learning, are increasingly embedded in enterprise applications to enhance performance and enable intelligent automation. This supports faster data analysis, tailored customer experiences, and higher productivity, with particularly strong demand in healthcare, finance, and logistics. Recent developments include OpenAI’s May 2025 research preview of Codex, an AI software engineering agent that writes code, debugs, and runs tests, and the July 2025 debut of Rune Technologies’ AI-powered military logistics platform, TyrOS, which raised USD 24 million in Series A funding.

Another key factor supporting United States software market growth is the heightened focus on security and compliance. As digital systems and regulatory environments grow more complex, developers and businesses are building security and compliance natively into the software development lifecycle through DevSecOps. This responds to data governance needs and to regulations such as GDPR, HIPAA, and CCPA, and is increasing demand for secure coding, identity management, and auditability. In March 2025, OneTrust launched an AI-driven Privacy Breach Response Agent, built with Microsoft Security Copilot, to automate data analysis, regulatory mapping, and compliance measures during privacy incidents.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=19069&flag=C

United States Software Industry Segmentation Insights

Breakup by Type:

  • Application Software: Covers enterprise resource planning (ERP), customer relationship management (CRM), supply chain management (SCM), enterprise collaboration, enterprise content management (ECM), education software, and other business applications used to run core organizational functions.
  • System Infrastructure Software: Includes network management systems (NMS), storage software, and security software, forming the foundation that keeps IT environments connected, protected, and operational.
  • Development and Deployment Software: Comprises enterprise data management (EDM), business analytics and reporting tools, application servers, integration and orchestration middleware, and data quality tools that support building, connecting, and managing applications and data.
  • Productivity Software: Includes office software, creative software, and other tools that help individuals and teams create content, collaborate, and complete everyday tasks more efficiently.

Breakup by Deployment Mode:

  • On-premises: Software installed and run on an organization’s own servers, preferred where tight control over data, customization, and security is required.
  • Cloud-based: Software delivered over the internet on a subscription or on-demand basis, supported by scalability, lower upfront costs, remote accessibility, and the ongoing shift away from on-premises solutions.

Breakup by Enterprise Size:

  • Small and Medium-sized Enterprises: Adopting affordable, scalable, and easy-to-deploy software, including cloud-based and low-code or no-code platforms, to automate operations and compete more effectively.
  • Large Enterprises: Investing in enterprise-scale platforms for ERP, analytics, security, and AI-driven automation to support complex, multi-location operations and large-scale modernization.

Breakup by Industry Vertical:

  • IT and Telecom: Relies on software for network management, cloud infrastructure, and service delivery across fast-evolving digital ecosystems.
  • BFSI: Uses software for digital banking, risk management, fraud detection, and regulatory compliance, with strong emphasis on security.
  • Retail: Applies software to e-commerce, inventory and supply chain management, customer engagement, and personalized shopping experiences.
  • Government/Public Sector: Adopts software to modernize public services, strengthen cybersecurity, and support defense and logistics operations.
  • Energy and Utilities: Uses software for grid management, asset monitoring, operational analytics, and efficient resource planning.
  • Healthcare: Driven by growing demand for remote healthcare, patient management, and medical data analysis solutions.
  • Others: Covers additional verticals such as manufacturing, education, and logistics that rely on specialized and industry-specific software.

Breakup by Region:

  • Northeast: A major hub for financial services, healthcare, and professional services, driving demand for secure, compliance-focused, and analytics-oriented software.
  • Midwest: Supported by a strong base of manufacturing, agriculture, and logistics industries adopting software for automation, supply chain management, and operational efficiency.
  • South: Growing demand across energy, healthcare, and expanding business centers, supported by increasing enterprise digitization and technology investment.
  • West: Home to a dense concentration of technology companies and startups, fueling innovation in cloud, AI, and developer platforms.

Key Challenges and Growth Opportunities in the United States Software Market

The United States software market faces ongoing challenges from data privacy concerns, evolving regulatory requirements, and persistent cybersecurity threats, which require vendors to continually strengthen security and compliance capabilities.

Despite this, the market offers considerable growth opportunities as pressure builds to adopt intelligent automation, edge computing, and vertical-specific SaaS solutions. Continued demand for cloud-native architectures, AI-infused capabilities, and platform-as-a-service (PaaS) models, together with accelerated innovation cycles and real-time analytics, is expected to create substantial opportunities for long-term growth in the United States software market.

Competitive Landscape

The United States software market is highly competitive, with both international and national vendors competing for enterprise demand. Differentiation is based on innovation velocity, integration expertise, cybersecurity strength, and industry-specific tailoring to meet a wide range of enterprise needs. Vendors are increasingly focusing on cloud-first offerings, AI-powered capabilities, and security-by-design to strengthen their positions, while market participants continue to launch new AI-driven products and platforms to address evolving customer requirements.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
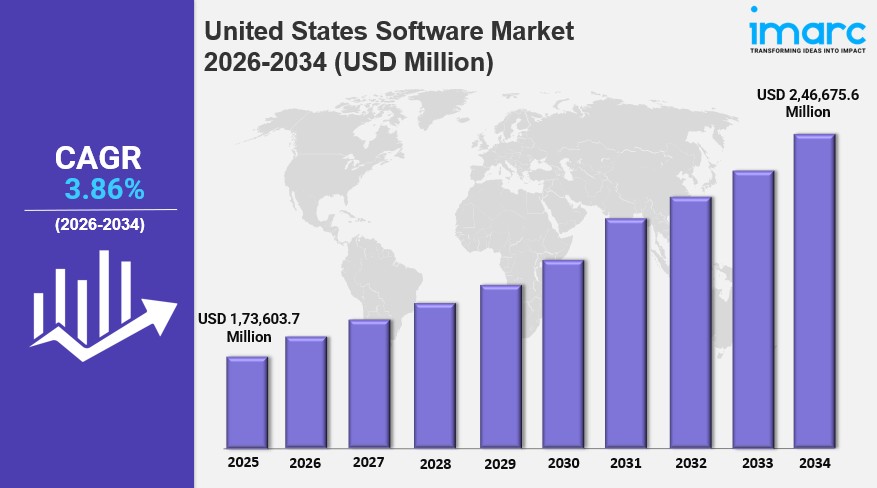
Mexico Ready to Drink Coffee Market Size, Share, Demand, Forecast, Report 2026-2034

Mexico Ready to Drink Coffee Market Size, Share, Demand, Forecast, Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Ready to Drink Coffee Market Size, Share, Trends and Forecast by Packaging, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Ready to Drink Coffee Market Size & Share 2026-2034

The Mexico ready to drink coffee market size reached USD 467.8 Million in 2025 and is projected to reach USD 744.9 Million by 2034, expanding at a CAGR of 5.14% during 2026-2034. In 2026, the market continues to gain momentum, propelled by a growing working population seeking easy and swift beverage consumption that fits an on-the-go lifestyle, rising spending on specialty and premium drinks, and the increasing influence of coffee culture.

Growth in 2026 is further reinforced by the convenience RTD coffee offers, giving consumers their preferred beverage without any preparation, alongside the expanding reach of convenience stores and supermarkets. These dynamics are expected to strengthen the Mexico ready to drink coffee market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 467.8 Million
  • Projected Market Size (2034): USD 744.9 Million
  • Growth Rate: CAGR of 5.14% (2026-2034)

Explore Opportunities in the Mexico Ready to Drink Coffee Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-ready-to-drink-coffee-market/requestsample

Key Growth Drivers and Trends in the Mexico Ready to Drink Coffee Market

Growth in the Mexico ready to drink coffee market is being driven by the rise of urban life and convenience culture. As more people move to urban centers for jobs and education, daily routines have become more hectic, and RTD coffee offers a quick, stimulating beverage that does not need to be brewed. Young professionals, students, and daily commuters in cities such as Mexico City, Guadalajara, and Monterrey gravitate toward portable coffee drinks, supported by the growing number of convenience stores, supermarkets, vending machines, and ready-to-consume facilities at fuel stations.

One of the leading Mexico ready to drink coffee market trends is the influence of global coffee culture and premiumization. According to SADER data, Chiapas is the leading coffee-producing state at 41.3%, followed by Veracruz at 24.4% and Oaxaca at 8.2%, and Mexico’s coffee industry includes over 500,000 producers and more than 75,500 coffee shops. As international café chains spread and social media raises awareness, consumers are seeking higher-quality, specialty-style coffee in convenient formats, prompting brands to offer cold brews, flavored lattes, and plant-based milk alternatives.

Another key factor supporting Mexico ready to drink coffee market growth is local ingredient innovation and a focus on sustainability. Brands increasingly highlight Mexican-grown beans from Chiapas, Veracruz, and Oaxaca, which supports local farmers and appeals to national pride, while experimenting with traditional flavors such as cinnamon, piloncillo, and chocolate. Sustainability is also gaining importance, with recyclable packaging, reduced plastic use, and fair trade practices.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=35242&flag=C

Mexico Ready to Drink Coffee Industry Segmentation Insights

Breakup by Packaging:

  • Bottles: A widely used format for portable, ready-to-consume coffee, with packaging increasingly designed to communicate quality, style, and sustainability.
  • Cans: A convenient on-the-go format suited to grab-and-go consumption through convenience stores, vending machines, and fuel stations.
  • Others: Covers additional packaging formats used for RTD coffee products.

Breakup by Distribution Channel:

  • Supermarkets/Hypermarkets: Offer consumers a wide choice of RTD coffee brands in one place, supported by the growing number of retail outlets.
  • Convenience Stores: A key channel for grab-and-go purchases by commuters, students, and young professionals in busy urban areas.
  • Online Retail: An emerging channel giving consumers easy access to a broad range of RTD coffee products.
  • Others: Includes vending machines and ready-to-consume facilities at fuel stations, which support on-the-go consumption.

Breakup by Region:

  • Northern Mexico: Includes urban centers such as Monterrey, where long working hours and busy lifestyles support demand for convenient RTD coffee.
  • Central Mexico: Includes Mexico City, one of the country’s largest urban markets, where traffic and fast-paced routines favor portable coffee drinks.
  • Southern Mexico: Includes major coffee-producing states such as Chiapas and Oaxaca, supporting local sourcing and sustainability-focused product positioning.
  • Others: Covers the remaining regions analyzed in the report.

Key Challenges and Growth Opportunities in the Mexico Ready to Drink Coffee Market

The Mexico ready to drink coffee market faces challenges including the need to keep pace with rising consumer sophistication, as buyers increasingly expect specialty-style quality, distinctive flavors, and credible sustainability practices in convenient formats. Competition among local and global brands also requires continued investment in product differentiation and packaging.

Despite these challenges, the market offers considerable growth opportunities driven by urbanization, the expanding middle class, the premiumization of RTD coffee, and growing interest in locally sourced, sustainable products. Continued innovation in cold brews, flavored lattes, plant-based options, and traditional Mexican flavors is expected to create substantial opportunities for long-term growth in the Mexico ready to drink coffee market.

Competitive Landscape

The Mexico ready to drink coffee market is competitive, with local and global brands investing in premium product offerings, quality-focused packaging, and sustainable sourcing to strengthen their market position. The IMARC report covers market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
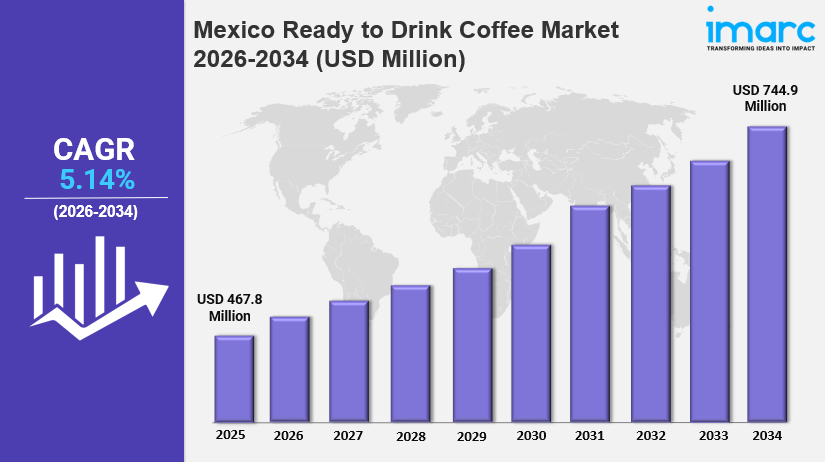
United States Gaming Market Size, Share, Trends | Forecast 2034

United States Gaming Market Size, Share, Trends | Forecast 2034

IMARC Group has recently released a new research study titled “United States Gaming Market Report by Device Type (Consoles, Mobiles and Tablets, Computer), Platform (Online, Offline), Revenue Type (In-Game Purchase, Game Purchase, Advertising), Type (Adventure/Role Playing Games, Puzzles, Social Games, Strategy, Simulation, and Others), Age Group (Adult, Children), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Gaming Market Size & Share 2026-2034

The United States gaming market size reached USD 59.6 Billion in 2025 and is projected to reach USD 108.1 Billion by 2034, expanding at a CAGR of 6.63% during 2026-2034. In 2026, the market continues to gain momentum, propelled by the expanding gaming industry, rapid urbanization, the proliferation of smartphones and tablets, the growing popularity of e-sports, and emerging technologies such as augmented reality (AR) and virtual reality (VR).

Growth in 2026 is further reinforced by increasing digitization and the growing accessibility of gaming platforms, which have made gaming more convenient and widespread by allowing people to play on the go. These dynamics are expected to strengthen the United States gaming market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 59.6 Billion
  • Projected Market Size (2034): USD 108.1 Billion
  • Growth Rate: CAGR of 6.63% (2026-2034)

Explore Opportunities in the United States Gaming Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-gaming-market/requestsample

Key Growth Drivers and Trends in the United States Gaming Market

Growth in the United States gaming market is being driven by the rising adoption of smartphones, which has made gaming more accessible than ever. With powerful hardware and high-speed internet connectivity, smartphones let users play a wide range of games anytime, anywhere, without dedicated consoles or PCs. According to the Statista Global Consumer Survey published in January 2022, nearly 54% of polled U.S. consumers play games on their smartphones regularly, and mobile gaming user penetration in the country rose from 41% in 2019 to more than 46% in 2023.

One of the leading United States gaming market trends is the increasing popularity of mobile gaming, which has broadened the gaming audience significantly to include people who may not have traditionally considered themselves gamers. Companies are also focusing on mobile game development, as seen when Netflix unveiled mobile games for Android users in November 2021, while the rising penetration of cloud gaming on inexpensive and mid-range smartphones is further expanding access to high-performance games.

Another key factor supporting United States gaming market growth is the emergence of cloud gaming subscriptions, which let players access a vast library of games on smartphones, tablets, PCs, and smart TVs without expensive hardware. Netflix began testing its cloud gaming service in the United States in October 2023, and the rollout of 5G networks, with lower latency and higher bandwidth, is enabling smoother and more responsive gameplay. Continuous advances in AR, VR, and digital game distribution platforms further stimulate demand.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=9497&flag=C

United States Gaming Industry Segmentation Insights

Breakup by Device Type:

  • Consoles: Platforms such as PlayStation, Xbox, and Nintendo Switch remain popular, with demand often peaking during holiday seasons when new releases and bundle deals attract consumers.
  • Mobiles and Tablets: A major segment driven by widespread smartphone and tablet adoption, the convenience of gaming on mobile devices, and a diverse range of titles on app stores.
  • Computer: PC gaming remains a staple, supported by a dedicated community of enthusiasts who invest in high-performance hardware and by large digital distribution platforms such as Steam.

Breakup by Platform:

  • Online: Services such as Steam, Epic Games Store, PlayStation Store, Xbox Live Marketplace, and Nintendo eShop let gamers purchase and download games digitally and access them instantly.
  • Offline: Physical retail stores such as GameStop, Best Buy, and Walmart still play a role, selling games, consoles, accessories, and merchandise to consumers who prefer physical copies.

Breakup by Revenue Type:

  • In-Game Purchase: Transactions within a game to unlock additional content, features, or virtual goods, often through microtransactions for items such as cosmetic skins, virtual currency, and expansion packs.
  • Game Purchase: Buying the entire game upfront in physical or digital format, a model common for console and PC games.
  • Advertising: Ads integrated into the gameplay experience, displayed within the game environment or during loading screens to promote products, services, or other games.

Breakup by Type:

  • Adventure/Role Playing Games: Narrative-driven games where players assume character roles, with exploration, character development, quests, and decision-making.
  • Puzzles: Games that challenge players to solve problems using logic, strategy, and spatial reasoning, such as matching patterns or solving riddles.
  • Social Games: Games designed to be played and shared with others through social networking platforms or multiplayer features, focused on interaction, cooperation, and competition.
  • Strategy: Games centered on planning and tactical decision-making to achieve objectives.
  • Simulation: Games that recreate real-world or imagined activities and environments.
  • Others: Covers additional game genres beyond those listed above.

Breakup by Age Group:

  • Adult: Seek high-quality experiences with engaging narratives, immersive gameplay mechanics, impressive graphics, depth, challenge, and replay value.
  • Children: Drawn to entertaining and fun games with colorful graphics, engaging characters, and exciting gameplay that holds their attention.

Breakup by Region:

  • Northeast: Cities such as New York City, Boston, and Philadelphia have diverse, tech-savvy populations that contribute to a robust gaming market.
  • Midwest: Cities such as Madison, Wisconsin, and Ann Arbor, Michigan, are emerging hubs for game development and technology startups, supported by game studios and incubators.
  • South: Features a diverse gaming culture shaped by regional identity, demographics, and cultural heritage, from urban centers like Atlanta and Miami to suburban and rural communities.
  • West: The West Coast has a thriving indie game development scene, with independent studios and solo developers creating innovative and artistic games.

Key Challenges and Growth Opportunities in the United States Gaming Market

The United States gaming market faces challenges including high competition among key players and rising cybersecurity concerns, both of which can hamper market growth.

Despite these challenges, the market offers considerable growth opportunities driven by technologies such as VR, AR, and artificial intelligence (AI), which present exciting possibilities for innovation in gaming experiences. Continued growth in cloud gaming, mobile gaming, and digital distribution is expected to create substantial opportunities for long-term growth in the United States gaming market.

Competitive Landscape

The United States gaming market is competitive, with key players focusing on technological innovation, mobile and cloud gaming expansion, and digital distribution to strengthen their market position. The IMARC report covers market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302