IMARC Group has recently released a new research study titled “United States Peanut Butter Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
United States Peanut Butter Market Size & Share 2026-2034
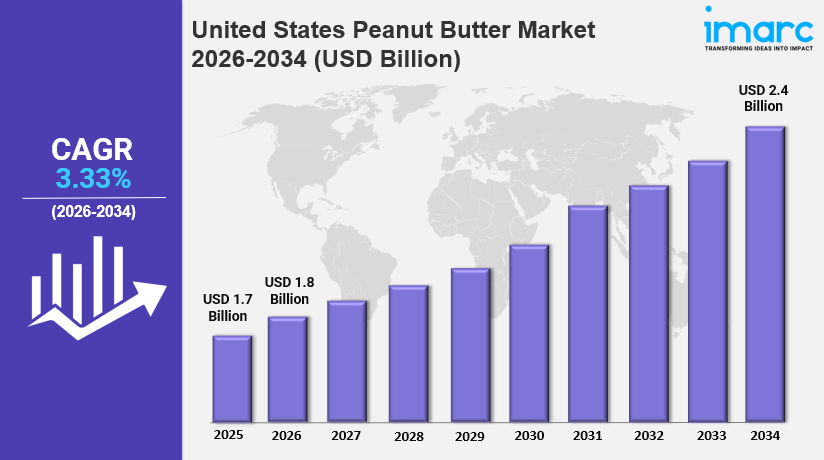
The United States peanut butter market size increased from USD 1.7 Billion in 2025 to USD 1.8 Billion in 2026 and is projected to reach USD 2.4 Billion by 2034, expanding at a CAGR of 3.33% during 2026-2034. In 2026, the market continues to gain momentum, fueled by increasing consumer interest in nutritious, protein-rich foods and the versatility of peanut butter across various meal occasions.
Growth in 2026 is further reinforced by rising demand for clean-label products, innovative packaging formats, and evolving dietary preferences. Strong distribution through retail and online channels, along with expanding usage in both sweet and savory recipes, is expected to strengthen the United States peanut butter market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 1.7 Billion
- Market Size (2026): USD 1.8 Billion
- Projected Market Size (2034): USD 2.4 Billion
- Growth Rate: CAGR of 3.33% (2026-2034)
Explore Opportunities in the United States Peanut Butter Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-peanut-butter-market/requestsample
Key Growth Drivers and Trends in the United States Peanut Butter Market
Growth in the United States peanut butter market is being driven primarily by changing consumer preferences and a heightened emphasis on health and wellness. As individuals look for nutritious and protein-rich food options, peanut butter has become more popular for its natural properties and health benefits. In May 2024, Jif introduced its Peanut Butter & Chocolate Flavored Spread, its first significant flavor innovation in almost ten years, with 50% less sugar than popular hazelnut spreads.
One of the leading United States peanut butter market trends is cross-category integration. Peanut butter is no longer just a traditional breakfast spread; it is a popular ingredient in baked goods, protein bars, smoothies, savory sauces, and ready-to-eat meals, driving demand in both retail and foodservice. In March 2025, Justin’s announced plans to launch new products such as Classic Crunchy Peanut Butter and Peanut Caramel Nougat Chocolate Candy Bars, along with frozen Sandos in collaboration with Rudi’s Rocky Mountain Bakery.
Another key factor supporting United States peanut butter market growth is the shift toward clean-label and natural products, alongside alternative formats that drive convenience-led growth. Shoppers increasingly prefer peanut butter made with only a few ingredients, mainly peanuts and salt, without artificial preservatives, added sugars, or hydrogenated oils, while squeezable pouches, resealable snack packs, and single-serve containers address the need for on-the-go usability and portion control.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=11604&flag=C
United States Peanut Butter Industry Segmentation Insights
Breakup by Product Type:
- Crunchy Peanut Butter: Valued for its texture and used widely as a spread and ingredient, with steady demand across the South and other regions.
- Smooth Peanut Butter: The largest product type, holding 59.7% of the market in 2024, driven by its easy spreadability, consistent texture, and appeal across all age groups, including children and busy professionals.
- Others: Includes flavored and specialty varieties such as organic, high-protein, and chocolate-flavored spreads.
Breakup by Distribution Channel:
- Supermarkets and Hypermarkets: The leading channel with around 53.3% of market share in 2024, allowing shoppers to compare brands, sizes, and flavors in one place, often with promotional discounts and strong in-store visibility.
- Convenience Stores: Serve quick, on-the-go purchases, supported by single-serve and resealable formats.
- Online Stores: A growing channel for niche, organic, and direct-to-consumer brands, widening access to a broader audience.
- Others: Includes other retail formats and channels through which peanut butter is sold.
Breakup by Region:
- Northeast: Consistent demand fueled by health-conscious consumers seeking natural and organic options, with urban centers embracing clean-label and specialty varieties.
- Midwest: A substantial share driven by high household consumption and strong brand loyalty, with a preference for traditional smooth peanut butter and stable demand from bulk purchases at large retailers and discount chains.
- South: Notable growth bolstered by cultural familiarity and broad consumption across age groups, with steady demand for both smooth and crunchy varieties and rising interest in low-sugar and protein-rich options.
- West: A vibrant market shaped by lifestyle and health trends, where consumers favor organic, plant-based, and clean-label products that foster niche and premium brands.
Key Challenges and Growth Opportunities in the United States Peanut Butter Market
The United States peanut butter market faces challenges including intense competition among established brands and new entrants, and the growing popularity of cost-effective private-label products in major retail stores. Allergen concerns around peanuts and the need for continuous innovation to maintain customer loyalty also shape brand strategies.
Despite these challenges, the market offers considerable growth opportunities driven by rising health awareness, demand for plant-based protein, and the versatility of peanut butter in various meals. Product innovation, clean-label formulations, convenient ready-to-use formats, and the growth of e-commerce and direct-to-consumer sales are expected to support long-term growth.
Competitive Landscape
The United States peanut butter market is competitive, with both well-established brands and new entrants. Companies strive to attract consumers through high product quality, competitive pricing, innovative packaging, and health-oriented formulations. Niche products such as organic, flavored, and high-protein options help newer brands carve out their own space, while private-label brands are gaining popularity by offering cost-effective choices. Health-focused claims, sustainability messaging, and e-commerce and direct-to-consumer channels are becoming vital for brand positioning and reach.
Recent Developments in the United States Peanut Butter Market
- May 2025: Ferrero announced its first-ever Nutella flavor variation, Nutella Peanut, blending peanut butter with its classic hazelnut spread and set for 2026 release. Ferrero invested USD 75 Million to expand its Illinois plant, adding the first U.S. Nutella production line.
- March 2025: Drumstick launched its first-ever peanut butter sundae cones nationwide with the “We Love Peanut Butter” 8-pack, featuring peanut butter and chocolate peanut butter flavors.
- February 2025: Honey Stinger introduced a new range of organic peanut butter energy waffles in three flavors: plain peanut butter, peanut butter chocolate, and peanut butter strawberry.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302

