Author: Deepak Mishra

Mexico Automotive Camera Market Size, Share, Growth, Trends Analysis, Report 2026-2034

Mexico Automotive Camera Market Size, Share, Growth, Trends Analysis, Report 2026-2034

IMARC Group has recently released a new research study titled “Mexico Automotive Camera Market Report by Vehicle Type (Passenger Cars, Commercial Vehicles), Technology (Digital Camera, Infrared, Thermal), Application Type (ADAS, Parking), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Automotive Camera Market Size & Share 2026-2034

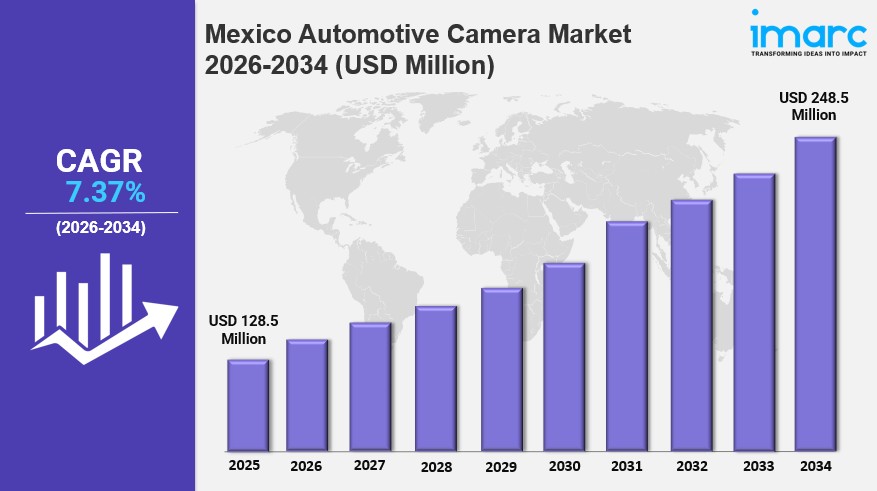
The Mexico automotive camera market size reached USD 128.5 Million in 2025 and is projected to reach USD 248.5 Million by 2034, expanding at a CAGR of 7.37% during 2026-2034. In 2026, the market continues to gain momentum, propelled by rising vehicle production, growing consumer awareness about safety, supportive regulations, escalating demand for luxury vehicles, and continued technological advancements.

Growth in 2026 is further reinforced by Mexico’s role as a major vehicle manufacturing and export hub, alongside expanding integration of advanced driver assistance systems across passenger and commercial vehicles. These dynamics are expected to strengthen the Mexico automotive camera market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 128.5 Million
  • Projected Market Size (2034): USD 248.5 Million
  • Growth Rate: CAGR of 7.37% (2026-2034)

Explore Opportunities in the Mexico Automotive Camera Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-automotive-camera-market/requestsample

Key Growth Drivers and Trends in the Mexico Automotive Camera Market

Growth in the Mexico automotive camera market is being driven by increasing vehicle production, as Mexico has established itself as a significant hub for vehicle manufacturing and export, supported by favorable trade agreements, a skilled workforce, and strategic geographic location. Mexico produces 3.5 million passenger cars a year, making it the seventh-largest passenger vehicle producer in the world, with 76% of vehicles made in Mexico exported, primarily to the U.S., driving demand for advanced safety features such as cameras, particularly for export-oriented vehicles destined for markets with stringent safety regulations.

One of the leading Mexico automotive camera market trends is the tightening of government regulations and safety standards, as regulatory bodies in Mexico and export destination markets progressively implement stricter safety requirements incorporating advanced technologies like cameras. The Federal Official Gazette released NOM-194-SE-2021 on October 3, 2022, outlining specifications and standards for safety equipment on new lightweight vehicles intended for commercialization within Mexico, aimed at reducing traffic accidents and improving road safety while encouraging manufacturers to integrate cameras into vehicle designs.

Another key factor supporting Mexico automotive camera market growth is rising consumer demand for vehicle safety, as growing awareness of road safety and the benefits of advanced safety features has increased preference for vehicles equipped with the latest safety technologies. Cameras that enhance driver visibility and reduce blind spots have become a major selling factor, while increased road accidents and fatalities have driven both consumers and policymakers to prioritize vehicle safety through stricter regulations and guidelines.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=24625&flag=C

Mexico Automotive Camera Industry Segmentation Insights

Breakup by Vehicle Type:

  • Passenger Cars: Represents a leading vehicle type segment, driven by rising consumer demand for advanced safety features and Mexico’s strong passenger vehicle production base.
  • Commercial Vehicles: Benefits from growing adoption of camera systems to support fleet safety, logistics efficiency, and regulatory compliance.

Breakup by Technology:

  • Digital Camera: Widely adopted for its high-resolution imaging capabilities supporting ADAS and parking assistance functions.
  • Infrared: Enables enhanced visibility in low-light and nighttime driving conditions.
  • Thermal: Supports advanced detection capabilities for pedestrians and obstacles in challenging visibility conditions.

Breakup by Application Type:

  • ADAS: Represents a major growth driver as automakers integrate advanced driver assistance systems to meet evolving safety standards.
  • Parking: Benefits from rising consumer demand for backup and surround-view camera systems supporting safer, more convenient parking.

Breakup by Region:

  • Northern States: Benefits from a strong automotive manufacturing base and proximity to U.S. export markets.
  • Central States: Holds a significant share supported by dense industrial infrastructure and vehicle assembly operations.
  • Southern States: An emerging region with growing automotive investment supporting camera adoption.

Key Challenges and Growth Opportunities in the Mexico Automotive Camera Market

The Mexico automotive camera market faces challenges including the need for continuous technological innovation to keep pace with evolving safety standards, along with cost pressures associated with integrating advanced camera systems into vehicles across different price segments. Ensuring consistent quality and reliability across a growing supplier base also remains an important consideration for manufacturers.

Despite these challenges, the market offers considerable growth opportunities driven by Mexico’s expanding role as a global vehicle production and export hub, rising consumer demand for enhanced safety features, and continued evolution of regulatory standards mandating camera integration. Growing investment in domestic camera module manufacturing capacity is expected to create substantial opportunities for long-term growth in the Mexico automotive camera market.

Competitive Landscape

The Mexico automotive camera market is competitive, with established automotive electronics manufacturers and specialized camera technology providers focusing on production capacity expansion, technological innovation, and strategic investment to strengthen their market position. Companies are increasingly establishing or expanding local manufacturing facilities to serve Mexico’s growing automotive production base and meet rising demand for advanced camera systems across passenger and commercial vehicle segments.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Football Market Size, Share, Growth, Latest Trends and Forecast 2026-2034

United States Football Market Size, Share, Growth, Latest Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “United States Football Market Report by Type (Training Football, Match Football, and Others), Size (Size 1, Size 2, Size 3, Size 4, Size 5), Distribution Channel (Online, Offline), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Football Market Size & Share 2026-2034

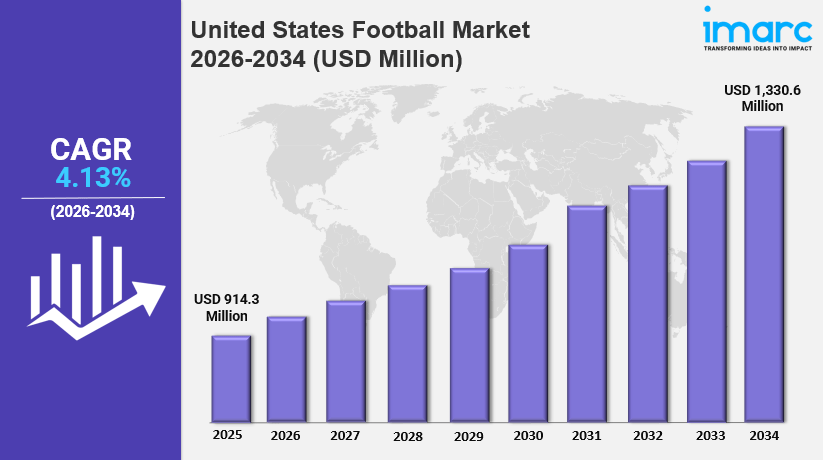
The United States football market size reached USD 914.3 Million in 2025 and is projected to reach USD 1,330.6 Million by 2034, expanding at a CAGR of 4.13% during 2026-2034. In 2026, the market continues to gain momentum, propelled by the increasing popularity of the sport, rising investment in youth development programs, and growing digital technology that offers easy access to live games, highlights, and player statistics through online platforms and mobile apps.

Growth in 2026 is further reinforced by effective marketing by major sports leagues, expanding fan engagement on social media, and the growing link between sports leagues and betting companies. These dynamics are expected to strengthen the United States football market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 914.3 Million
  • Projected Market Size (2034): USD 1,330.6 Million
  • Growth Rate: CAGR of 4.13% (2026-2034)

Explore Opportunities in the United States Football Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-football-market/requestsample

Key Growth Drivers and Trends in the United States Football Market

Growth in the United States football market is being driven by the increasing popularity of the sport, supported by effective marketing from major leagues such as the National Football League (NFL). These leagues have invested heavily in promoting the sport at home and abroad, and initiatives such as the NFL’s international series of games have expanded its reach, attracting new fans and revenue streams.

One of the leading United States football market trends is the rise of digital technology, which gives fans easy access to live games, highlights, and player statistics through online platforms and mobile apps. Social media further supports the sport by giving fans a space to discuss, share, and engage with football content.

Another key factor supporting United States football market growth is rising investment in youth development programs and initiatives that introduce the sport to younger audiences, creating a steady pipeline of talent, alongside college and university football scholarships. The legalization of sports betting in several states has also created new avenues for revenue and fan engagement, leading to partnerships between sports leagues and betting companies.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=19930&flag=C

United States Football Industry Segmentation Insights

Breakup by Type:

  • Training Football: Covers footballs designed for practice sessions, drills, and skill development.
  • Match Football: Covers footballs designed for competitive games and matches.
  • Others: Includes additional football types serving recreational and specialized use.

Breakup by Size:

  • Size 1: Covers the smallest football size category.
  • Size 2: Covers small footballs in the mini size range.
  • Size 3: Covers footballs suited to younger players.
  • Size 4: Covers footballs used in youth play.
  • Size 5: Covers the full-size football used in standard adult play.

Breakup by Distribution Channel:

  • Online: Includes sales through e-commerce platforms and online sports retailers.
  • Offline: Includes sales through sporting goods stores, specialty outlets, and other physical retail.

Breakup by Region:

  • Northeast: One of the four major regional markets analyzed in the report.
  • Midwest: One of the four major regional markets analyzed in the report.
  • South: One of the four major regional markets analyzed in the report.
  • West: One of the four major regional markets analyzed in the report.

United States Football Market: Key Challenges and Opportunities

The United States football market faces challenges including strong competition from established sports such as American football, basketball, and baseball, which can limit audience engagement and media attention. Limited participation in some regions, fragmented youth development pathways, high training and facility costs, and the need for continued investment in professional and grassroots infrastructure may also constrain market expansion.

However, significant opportunities exist through growing youth participation, expanding Major League Soccer (MLS), increasing investment in professional clubs and academies, and rising interest among younger and diverse audiences. The 2026 FIFA World Cup hosted across the United States, Canada, and Mexico is expected to further increase visibility, sponsorship, tourism, merchandise sales, and fan engagement, while digital streaming and social media offer additional avenues for reaching new audiences.

Competitive Landscape

The IMARC report provides a comprehensive analysis of the competitive landscape of the United States football market, covering market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of all major companies.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Laptop Market Market Size, Share, Growth Analysis and Forecast 2026-2034

United States Laptop Market Market Size, Share, Growth Analysis and Forecast 2026-2034

IMARC Group has recently released a report titled “United States Laptop Market Size, Share, Trends and Forecast by Type, Screen Size, Price, End Use, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Laptop Market Size and Forecast 2026–2034

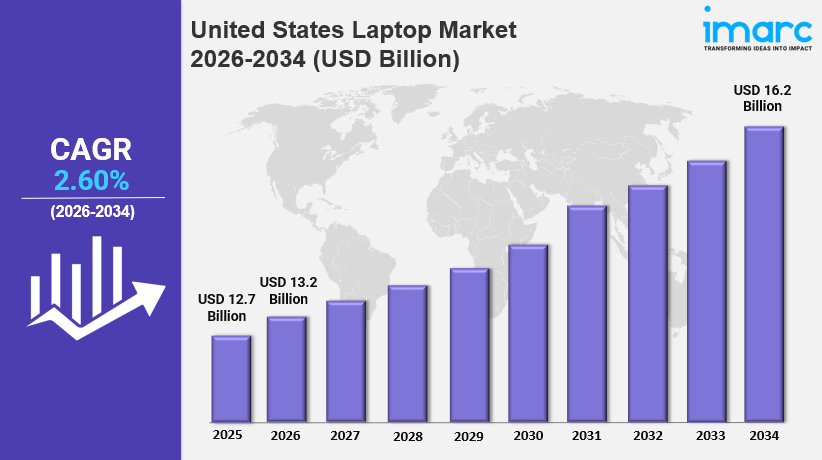
The United States laptop market size increased from USD 12.7 Billion in 2025 to USD 13.2 Billion in 2026. Looking forward, IMARC Group estimates the market to reach USD 16.2 Billion by 2034, exhibiting a CAGR of 2.60% from 2026–2034. The market is growing due to increasing demand for remote work and online learning solutions, and innovations such as AI-powered features, 5G connectivity, and lightweight designs. The growing popularity of gaming and creative industries has also augmented demand for high-performance laptops with advanced graphics.

In 2026, the United States laptop market growth is being supported by the shift toward hybrid and remote work models, business investment in laptops with advanced security, high processing power, and cloud integration, and the adoption of e-learning platforms and government initiatives promoting digital literacy. Robust retail and e-commerce channels, along with rising interest in energy-efficient and eco-friendly devices, are further improving access and market penetration.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 12.7 Billion
  • Market Size (2026): USD 13.2 Billion
  • Projected Size (2034): USD 16.2 Billion
  • Growth Rate: CAGR of 2.60%

Explore Opportunities in the United States Laptop Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-laptop-market/requestsample

United States Laptop Market Growth: Key Trends and Market Insights

The United States laptop market growth is supported by increased demand for thin, light, and multi-feature laptops, with AI-enabled features, greater portability, and longer battery life driving upgrades. The education sector is also a pivotal driver: according to IMARC Group, the United States e-learning market reached USD 122.4 Billion in 2023 and is expected to reach USD 278.3 Billion by 2032, exhibiting a CAGR of 9.3% during 2024–2032.

Key United States laptop market trends include the growing adoption of AI-powered features such as predictive battery optimization, adaptive performance adjustments, and enhanced security. In March 2024, HP Inc. launched its AI PC portfolio, including HP Elite PCs and Z by HP mobile workstations. The expansion of 5G-enabled laptops is another trend, supported by the share of known operator locations with 5G availability rising from 68.4% in Q3 2023 to 76.7% in Q1 2024.

Customizable and modular laptops are also gaining traction, allowing users to upgrade components such as RAM, storage, and graphics cards while addressing electronic waste concerns. In January 2024, HP Inc. introduced its most personalized gaming portfolio, featuring OMEN and HyperX innovations powered by Intel Core Ultra 9 185H processors and up to NVIDIA GeForce RTX 4070 GPUs. These evolving trends are expected to create opportunities for manufacturers through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20155&flag=C

United States Laptop Market Segmentation Analysis

The United States laptop market is segmented by type, screen size, price, end use, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Type

  • Traditional Laptop: Serves professionals, students, and casual consumers, noted for robust performance, versatility, and affordability.
  • 2-in-1 Laptop: Combines laptop and tablet functionality with touchscreens, stylus compatibility, and tent and tablet modes, popular among creative professionals, students, and business users.

Breakup by Screen Size

  • Up to 10.9″: Portable, affordable devices suited to students, travelers, and general users for browsing, streaming, and simple productivity.
  • 11″ to 12.9″: Balance style and performance for on-the-go and hybrid work, often with 2-in-1 capabilities and touch screens.
  • 13″ to 14.9″: Highly preferred for the balance between portability and screen area, with high resolution, longer battery life, and strong processing power.
  • 0″ to 16.9″: Suited to users who prioritize a larger display for work and entertainment.
  • More than 17″: Targets users who need maximum screen space, such as gamers and creative professionals.

Breakup by Price

  • Up to USD 500: Addresses budget-sensitive consumers, students, and casual users, and remains a major growth driver for education-related demand.
  • USD 501 to USD 1000: Balances cost and power with better processing, storage, and display quality for work, study, and light gaming.
  • USD 1001 to USD 1500: Offers advanced features and performance for creative professionals, gamers, and tech enthusiasts, including many hybrid and premium designs.
  • USD 1501 to USD 2000: Covers premium and high-performance devices.
  • Above USD 2001: Covers top-tier workstation and enthusiast laptops.

Breakup by End Use

  • Personal: Covers everyday tasks such as web browsing, streaming, social media, and light productivity for students, families, and individual users.
  • Business: Focuses on reliability, performance, and security features such as biometric authentication, supported by remote and hybrid work.
  • Gaming: Includes high-refresh-rate displays, dedicated GPUs, and powerful processors for gamers, esports users, and 3D modelers.
  • Others: Includes additional specialized uses.

Breakup by Region

  • Northeast: A heavy concentration of educational institutions sustains laptop demand in the education and professional sectors.
  • Midwest: Its manufacturing and industrial base drives constant demand for business laptops as remote work technologies expand.
  • South: Rapidly developing tech hubs and diverse industries drive strong growth in gaming and business segments.
  • West: Silicon Valley and other innovation centers lead demand for high-performance laptops for tech professionals, creative industries, and gamers.

Key Challenges and Growth Opportunities in the United States Laptop Market

The United States laptop market faces several challenges that could affect its growth, including supply chain disruption, price pressure, and stiff competition that test profitability. Fast-paced technology changes require continuous innovation, and consumer apprehension about AI usage and data privacy may slow adoption of newer laptop variants.

Despite these challenges, the market offers significant growth opportunities, as eco-friendliness, modular designs, and AI capabilities can be used to differentiate products. Direct-to-consumer models, penetration of creators and gamers, and improved customer support can support long-term brand loyalty and expansion through 2034.

Competitive Landscape

The United States laptop market is highly competitive, with key players focusing on consumer-centric and sustainable approaches. Manufacturers are integrating AI-powered performance enhancements, 5G connectivity, and advanced security features, while launching high-performance laptops for gamers, creatives, and professionals and ultra-portable and 2-in-1 devices for remote workers and students. The report provides a comprehensive analysis of the competitive landscape, with detailed profiles of all major companies.

Market participants are also adopting recycled materials, improving energy efficiency, and implementing eco-friendly production, while flexible pricing, subscription-based and financing models expand accessibility across income brackets. Leading players are capitalizing on digital sales channels, strengthening retail partnerships, and enhancing customer service to ensure seamless purchase and post-purchase experiences.

Latest News and Developments

  • July 2025: Google announced plans to merge Chrome OS and Android into a unified platform, according to Android ecosystem president Sameer Samat, signaling deeper integration across smartphones, tablets, laptops, and other connected hardware.
  • September 2024: Lenovo unveiled AI-focused products at Innovation World 2024, including the ThinkPad X1 Carbon Gen 13 Aura Edition and the Auto Twist AI PC concept, expanded its Copilot+ PC portfolio with new ThinkPad and ThinkBook models, and launched the AI PC Fast Start solution to accelerate enterprise AI adoption.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Beer Market Size to Reach USD 132.99 Billion by 2034 at 2.20% CAGR

United States Beer Market Size to Reach USD 132.99 Billion by 2034 at 2.20% CAGR

IMARC Group has recently released a report titled “United States Beer Market Size, Share, Trends and Forecast by Product Type, Packaging, Production, Alcohol Content, Flavor, Distribution Channel, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Beer Market Size and Forecast 2026–2034

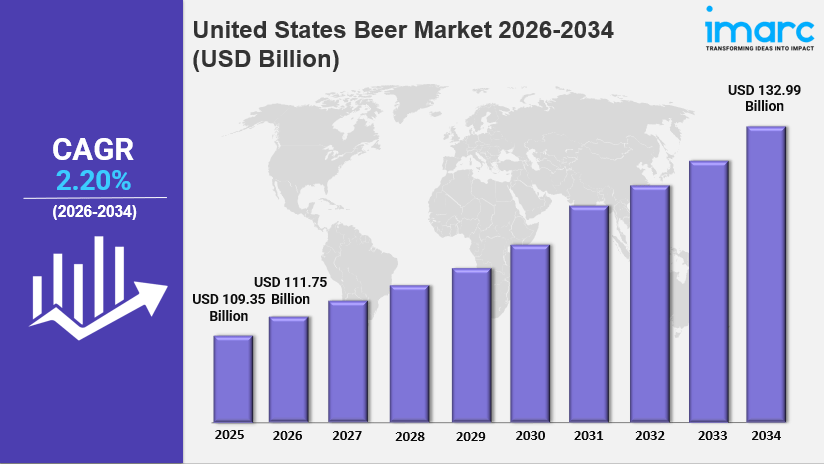
The United States beer market size increased from USD 109.35 Billion in 2025 to USD 111.75 Billion in 2026 and is projected to reach USD 132.99 Billion by 2034, exhibiting a CAGR of 2.20% during 2026–2034. The market is growing due to changing consumer preferences towards craft and flavored beers, rising disposable incomes, and the proliferation of microbreweries and brewpubs.

In 2026, the United States beer market growth is being supported by premiumization, with consumers trading up to premium lagers, craft IPAs, and imported specialty beers, alongside the mainstreaming of low-alcohol and non-alcoholic variants and the development of direct-to-consumer e-commerce channels. Standard lager dominates the product mix at 46.8% in 2025, glass packaging leads at 41.6%, and the West commands a 29.6% regional share, reflecting California’s craft culture and premium demand.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 109.35 Billion
  • Market Size (2026): USD 111.75 Billion
  • Projected Size (2034): USD 132.99 Billion
  • Growth Rate: CAGR of 2.20%
  • Largest Region (2025): West (29.6%)
  • Second Region (2025): South (27.8%)
  • Leading Product Type (2025): Standard Lager (46.8%)
  • Leading Packaging (2025): Glass (41.6%)

Explore Opportunities in the United States Beer Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-beer-market/requestsample

United States Beer Market Growth: Key Trends and Market Insights

The United States beer market growth is supported by the craft beer and premiumization trend, as consumers increasingly prefer unique, locally produced, and artisanal varieties. Over 9,700 craft breweries were operating in the United States, generating sustained demand for specialty and premium segments that command higher retail price points. Beer’s strong association with sports events, concerts, and music festivals, along with the expanding network of microbreweries and brewpubs, continues to drive high-frequency consumption occasions and brewery tourism.

Key United States beer market trends include non-alcoholic beer becoming a mainstream category, as the sober-curious movement and brewing technology advances allow premium positioning; Blue Moon Non-Alcoholic and Heineken 0.0 both entered the top non-alcoholic beverage rankings within their first year of launch. The market is also growing in value terms through premiumization despite volume pressures from health consciousness, while sustainability credentials, such as Molson Coors’ commitment of USD 85 million to eliminate plastic six-pack rings, are becoming a key purchase driver among younger consumers.

The regulatory easing of direct-to-consumer alcohol shipping in over 40 states is opening a new high-margin channel for craft brewers, supported by subscription clubs, limited-edition releases, and digital marketing and loyalty programs. These evolving trends are expected to create opportunities for brewers as revenue mix shifts toward higher-value premium and craft categories through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=4662&flag=C

United States Beer Market Segmentation Analysis

The United States beer market is segmented by product type, packaging, production, alcohol content, flavor, distribution channel, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Product Type

  • Standard Lager: Leads with a 46.8% share in 2025, owing to widespread appeal, an accessible price point, and the brand strength of Budweiser, Coors Light, and Miller Lite.
  • Premium Lager: Holds a 24.6% share in 2025, capturing the premiumization trend as consumers trade up to brands such as Heineken, Corona, and Stella Artois.
  • Specialty Beer: Accounts for 20.4% in 2025 and is the fastest-growing product segment (~3.2% CAGR through 2034), driven by craft brewery expansion, IPAs, stouts, and sour ales.
  • Others: Represents 8.2% in 2025, including malt beverages and rapidly growing non-alcoholic variants.

Breakup by Packaging

  • Glass: Dominates at 41.6% in 2025, preferred for premium, craft, and imported beers where bottle presentation signals quality.
  • Metal Can: Holds 34.8% in 2025, supported by sustainability advantages, portability, and growing craft brewery adoption.
  • PET Bottle: Accounts for 15.6% in 2025, serving value and convenience segments, with a projected CAGR of ~3.5% through 2034.
  • Others: Represents 8.0% in 2025, including kegs and innovative packaging emerging in hospitality channels.

Breakup by Production

  • Macro-Brewery: The leading production category in 2025, benefiting from scale, national distribution, and cost efficiency.
  • Micro-Brewery: Supported by the craft movement, local loyalty, and taproom and tourism demand.
  • Others: Includes brewpubs and other production formats.

Breakup by Alcohol Content

  • High: The leading category in 2025, covering traditional-strength beers.
  • Low: Growing with health-conscious consumers seeking low-calorie and low-alcohol options.
  • Alcohol-Free: A fast-expanding category driven by the sober-curious movement and premium non-alcoholic launches.

Breakup by Flavor

  • Unflavored: The leading category in 2025, anchored by traditional lagers and ales.
  • Flavored: Benefits from consumer interest in innovation and experimental profiles.

Breakup by Distribution Channel

  • Supermarkets and Hypermarkets: The leading channel in 2025, offering broad availability and large-format retail reach.
  • On-Trades: Includes bars, restaurants, stadiums, and taprooms, where glass and draft formats are prominent.
  • Specialty Stores: Serve craft, import, and premium beer demand.
  • Convenience Stores: Provide accessible, high-frequency purchase occasions.
  • Others: Includes e-commerce and direct-to-consumer channels.

Breakup by Region

  • West: Commands the largest share at 29.6% in 2025, driven by California’s craft breweries, Pacific Northwest premium demand, and Colorado’s craft scene.
  • South: Holds 27.8% in 2025, supported by high-volume consumption in Texas, Florida, and Georgia, sports events, and outdoor culture.
  • Midwest: Accounts for 23.4% in 2025, anchored by heritage brewing in Chicago, St. Louis, and Milwaukee.
  • Northeast: Represents 19.2% in 2025, with premium urban craft demand in New York City and Boston.

Key Challenges and Growth Opportunities in the United States Beer Market

The United States beer market faces several challenges that could affect its growth, including a health consciousness and moderation trend among Millennials and Gen Z that pressures mainstream standard lager volumes, competition from wine, spirits, hard seltzers, and ready-to-drink cocktails, and commodity input cost volatility across barley, hops, aluminum, and glass. The three-tier distribution system and varying state alcohol laws also create compliance complexity, particularly for small craft producers.

Despite these challenges, the market offers significant growth opportunities driven by the mainstreaming of non-alcoholic beer, direct-to-consumer e-commerce channels, and continued premiumization and craft beer innovation. Brewers investing in premium portfolios, zero-alcohol variants, sustainable packaging, and digital engagement will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The United States beer market is moderately concentrated, with Anheuser-Busch InBev and Molson Coors commanding a combined estimated 60–65% volume share, while Constellation Brands leads the premium import segment. Key players include Anheuser-Busch InBev, Molson Coors Beverage Company, Constellation Brands, Boston Beer Company, Heineken USA, Pabst Brewing Company, and Diageo Beer Company USA. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.

Market participants are investing in premium and craft portfolios, non-alcoholic offerings, sustainability initiatives, and digital distribution platforms. Modelo Especial overtook Bud Light as the top-selling U.S. beer brand by dollar value in 2023, underscoring Constellation’s premium import strength, while consolidation through craft acquisitions continues to reshape the competitive structure.

Latest News and Developments

  • March 2026: Constellation Brands entered into an agreement to acquire the remaining stake in HOPWTR, a fast-growing premium non-alcoholic beverage brand, taking full ownership after its initial investment in 2021.
  • May 2025: Anheuser-Busch announced a USD 300 million investment to expand and modernize its manufacturing operations across the United States, focusing on facility upgrades, technology, and workforce development.
  • March 2022: Molson Coors committed USD 85 million to eliminate plastic six-pack rings from its North American brands by the end of 2025.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Biodiesel Market Size, Overview, Industry Growth Rate, Research Report 2026-2034

United States Biodiesel Market Size, Overview, Industry Growth Rate, Research Report 2026-2034

IMARC Group has recently released a report titled “United States Biodiesel Market Size, Share, Trends and Forecast by Feedstock, Application, Type, Production Technology, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Biodiesel Market Size and Forecast 2026–2034

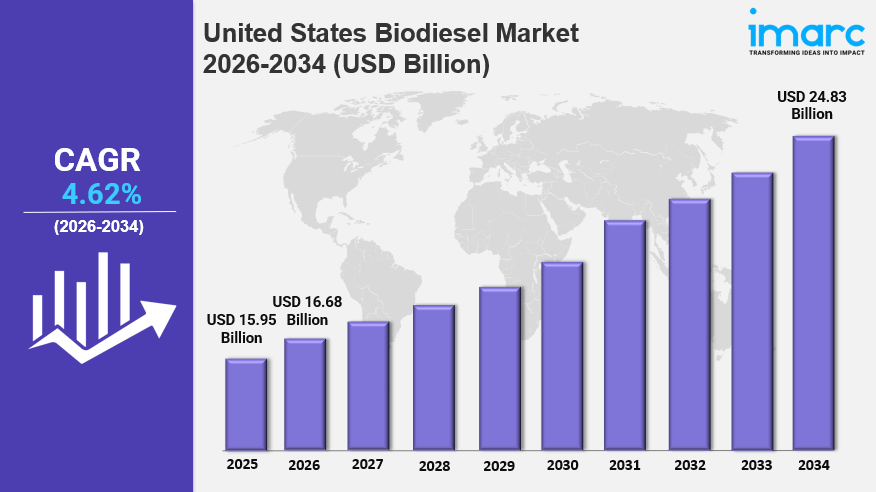
The United States biodiesel market size increased from USD 15.95 Billion in 2025 to USD 16.68 Billion in 2026 and is projected to reach USD 24.83 Billion by 2034, exhibiting a CAGR of 4.62% during 2026–2034. The market is growing due to strong support from the federal Renewable Fuel Standard (RFS), abundant domestic soybean oil supply, and rising fleet decarbonization efforts. Expanding renewable diesel capacity and low-carbon fuel standard incentives are further strengthening the market outlook.

In 2026, the United States biodiesel market growth is being driven by the Environmental Protection Agency’s proposed biomass-based diesel volume of 5.61 Billion gallons for 2026, the Section 45Z Clean Fuel Production Credit, which took effect in January 2025 and has been extended through 2029, and the expansion of state low-carbon fuel programs, including New Mexico’s Clean Transportation Fuel Program, which began implementation in April 2026. Rising adoption of B5 to B20 blends among trucking and municipal fleets, along with growing use in standby and backup power, is further broadening demand. After growing from USD 12.72 Billion in 2020, the market is expected to reach approximately USD 19.98 Billion by 2030.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 15.95 Billion
  • Market Size (2026): USD 16.68 Billion
  • Projected Size (2034): USD 24.83 Billion
  • Growth Rate: CAGR of 4.62%

Explore Opportunities in the United States Biodiesel Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-biodiesel-market/requestsample

United States Biodiesel Market Growth: Key Trends and Market Insights

The United States biodiesel market growth is supported by biodiesel’s shift from a niche additive to a core compliance fuel blended into the national diesel pool under the RFS. Falling soybean oil prices, fleet sustainability targets, and tightening biomass-based diesel obligations are lifting blending volumes, while state low-carbon fuel programs reinforce demand across on-road, off-road, and stationary applications. According to the U.S. Energy Information Administration, biodiesel and renewable diesel together met about 9% of on-road diesel demand in 2024.

Key United States biodiesel market trends include a shift toward lower-carbon-intensity feedstocks such as used cooking oil, distillers corn oil, and tallow, which earn higher Section 45Z and Low Carbon Fuel Standard (LCFS) credit values, the co-location of new projects with expanded soybean crushing capacity across Iowa, North Dakota, and the Mid-South, and the convergence of biodiesel with renewable diesel and sustainable aviation fuel (SAF) at multi-product biorefineries. Producers are also adopting continuous-flow reactors, solid catalysts, advanced feedstock pretreatment, and digital traceability platforms to improve yields and meet 45Z and LCFS reporting requirements.

Large logistics operators and municipal fleets are embedding B20 to B100 blends into ESG reporting and signing multi-year supply agreements, strengthening long-term offtake visibility. Vegetable oils, fuel, and the West region are expected to expand faster than the overall market through 2034, supported by soybean processing capacity and B20 fleet adoption, while the Midwest is projected to be the fastest-growing region.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2722&flag=C

United States Biodiesel Market Segmentation Analysis

The United States biodiesel market is segmented by feedstock, application, type, production technology, and region, offering a comprehensive view of feedstock sourcing, end-use demand, blending patterns, and regional dynamics across the country.

Breakup by Feedstock

  • Vegetable Oils: Leads with a 47.6% share in 2025, anchored by domestic soybean crushing infrastructure and abundant soybean oil supply.
  • Animal Fats: Holds a 32.4% share, covering tallow, choice white grease, poultry fat, and yellow grease from meatpacking and food service, which earn lower carbon-intensity scores.
  • Others: Accounts for the remaining 20.0%, including used cooking oil, distillers corn oil, and other waste-derived feedstocks.

Breakup by Application

  • Fuel: Dominates with a 68.3% share in 2025, driven by compliance blending into the on-road diesel pool and adoption of B5 to B20 blends across trucking and municipal fleets.
  • Power Generation: Holds an 18.7% share, concentrated in standby generators, data center backup, microgrids, and remote off-grid power.
  • Others: Represents the remaining 13.0%, including marine, rail, agricultural, and home-heating uses.

Breakup by Type

  • B100: Pure biodiesel, whose use is limited in northern winter conditions by higher cloud and pour points compared with petroleum diesel.
  • B20: The leading type in 2025, widely adopted by fleets to reduce scope-1 emissions without engine modifications.
  • B10: A lower blend supporting broad compatibility with existing diesel engines and fuel infrastructure.
  • B5: The lowest blend level, widely used for routine compliance blending into the diesel pool.

Breakup by Production Technology

  • Conventional Alcohol Trans-Esterification: The leading production technology in 2025, converting vegetable oils, animal fats, and recycled cooking oils with methanol and a catalyst into methyl esters and glycerin.
  • Pyrolysis: An alternative thermal conversion pathway covered within the report.
  • Hydro Heating: An alternative hydro-based conversion pathway covered within the report.

Breakup by Region

  • West: Commands the leading market share of 34.2% in 2025, driven by premium credit pricing under California’s LCFS, active programs in Oregon and Washington, and strong fleet decarbonization commitments.
  • Midwest: Holds a 27.8% share and is the fastest-growing region through 2034, supported by proximity to soybean crushing and animal-fat rendering capacity and dense biorefinery clusters in Iowa, Minnesota, Missouri, and Illinois.
  • South: Accounts for 22.6% of the market, supported by expanding soybean processing investments, growing trucking demand, and port-based export options.
  • Northeast: Holds a 15.4% share, supported by Bioheat home-heating-oil mandates, urban municipal fleet adoption, and developing state low-carbon fuel programs.

Key Challenges and Growth Opportunities in the United States Biodiesel Market

The United States biodiesel market faces several challenges that could affect its growth, including high feedstock cost volatility that can compress producer margins, competition from renewable diesel for the same fats and oils feedstocks, the lapse of the legacy USD 1 per gallon blender tax credit at the end of 2024, RIN price volatility and regulatory uncertainty, and cold-weather performance constraints that limit high-blend use in northern climates.

Despite these challenges, the market offers significant growth opportunities driven by waste and used cooking oil pathways that earn premium low-carbon pricing, co-production of sustainable aviation fuel, continued benefits from the Section 45Z production credit, and the expansion of state low-carbon fuel programs. Under-penetrated applications such as Bioheat in the Northeast, off-road agriculture and construction equipment, marine bunker fuel, and rail switching are expected to open additional demand pools. Vertically integrated operators and waste-feedstock specialists are best positioned to capture the largest share of value through 2034.

Competitive Landscape

The United States biodiesel market is moderately fragmented, with a handful of large vertically integrated producers operating at national scale alongside numerous regional and specialty producers. Key companies operating in the market include Chevron Corporation, ADM, Louis Dreyfus Company, Cargill, Incorporated, and Western Iowa Energy, LLC. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.

Feedstock procurement depth, biorefinery scale, and LCFS pathway approvals form the primary competitive advantages, with the top five producers estimated to hold approximately 50–60% of operating capacity in 2025. Barriers to entry include EPA RFS producer registration and access to long-term feedstock contracts, while consolidation is being driven by capital intensity and the shift toward renewable diesel and SAF co-production.

Latest News and Developments

  • April 2026: New Mexico began implementing its Clean Transportation Fuel Program, a low-carbon fuel standard aimed at reducing road fuel carbon intensity by 20% within this decade, marking the first such initiative beyond the West Coast.
  • August 2025: Chevron confirmed that its Geismar, Louisiana renewable fuels plant began production following an expansion that raised capacity from 7,000 to 22,000 barrels per day, lifting annual renewable diesel output from approximately 90 Million gallons to 340 Million gallons.
  • June 2025: Louis Dreyfus Company announced plans to reopen its Burns Harbor grain export facility in Portage, Indiana, supporting feedstock and origination flows for its Claypool, Indiana biodiesel plant.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
US Deodorant Market Size, Trends, Growth and Forecast 2026-2034

US Deodorant Market Size, Trends, Growth and Forecast 2026-2034

IMARC Group has recently released a report titled “US Deodorant Market Report by Product Type (Sprays, Roll-On, Creams, and Others), Distribution Channel (Supermarkets and Hypermarkets, Convenience Stores, Pharmacies, Online Stores, and Others), Packaging Type (Metal, Plastic, and Others), and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

US Deodorant Market Size and Forecast 2026–2034

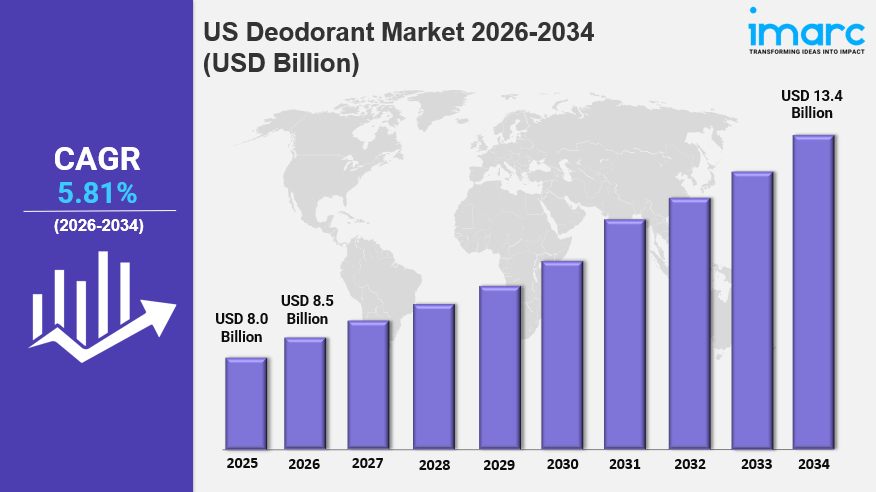
The US deodorant market size increased from USD 8.0 Billion in 2025 to USD 8.5 Billion in 2026 and is projected to reach USD 13.4 Billion by 2034, exhibiting a CAGR of 5.81% during 2026–2034. The market is growing due to the escalating health and wellness trend, the introduction of gender-specific products, growing demand for eco-friendly deodorants, increasing participation in sports and allied activities, and the proliferation of e-commerce platforms.

In 2026, the US deodorant market growth is being fueled by recent advancements in skincare science that enable more effective and skin-friendly formulations, aggressive marketing and promotional campaigns by manufacturers through celebrity endorsements, social media, and television commercials, and increasing humidity and hot weather conditions. Easy product availability across pharmacies, supermarkets, and online platforms is further broadening consumer access and intensifying competition among deodorant brands.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 8.0 Billion
  • Market Size (2026): USD 8.5 Billion
  • Projected Size (2034): USD 13.4 Billion
  • Growth Rate: CAGR of 5.81%

Explore Opportunities in the US Deodorant Market: Download the IMARC Sample Report: https://www.imarcgroup.com/us-deodorant-market/requestsample

US Deodorant Market Growth: Key Trends and Market Insights

The US deodorant market growth is supported by the escalating health and wellness trend, which extends beyond diet and exercise to personal hygiene and cleanliness. Body odor is widely considered socially unacceptable, and as awareness grows, demand for odor-controlling products rises. Personal hygiene is now seen as an essential part of the daily routine across teenagers, adults, and the geriatric population, while educational campaigns by health organizations explain the role of bacteria in causing body odor and how deodorants tackle it.

Key US deodorant market trends include the introduction of gender-specific products. Traditional deodorants were largely unisex, but research indicates that men and women have different requirements in intensity, duration, odor protection, and fragrance. Men’s deodorants offer longer-lasting effects and stronger scents for active or outdoor lifestyles, while women’s deodorants focus on milder fragrances and skin-sensitive formulations. This trend has opened new avenues for premium and specialized products, supported by gender-specific marketing strategies.

The US deodorant market growth is also being supported by growing demand for eco-friendly deodorants amid rising emphasis on sustainability, and by increasing participation in sports and allied activities that require long-lasting protection against sweat and odor. The health and wellness trend is also prompting consumers to seek innovative deodorants with added benefits, such as skin-moisturizing properties or added vitamins, creating opportunities for manufacturers through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=12182&flag=C

US Deodorant Market Segmentation Analysis

The US deodorant market is segmented by product type, distribution channel, packaging type, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Product Type

  • Sprays: Offer quick and easy application suited to fast-paced lifestyles, dry quickly, and use an aerosol mechanism that distributes the product uniformly for comprehensive coverage.
  • Roll-On: Provide more control during application for targeted odor protection, minimize wastage, and often come in alcohol-free and hypoallergenic formulations for sensitive skin.
  • Creams: Often contain moisturizing ingredients such as shea butter or coconut oil and come in compact containers that are easy to carry while traveling.
  • Others: Includes additional deodorant formats such as sticks.

Breakup by Distribution Channel

  • Supermarkets and Hypermarkets: Provide a broad range of brands and types in one location, along with competitive pricing, discounts, and promotions.
  • Convenience Stores: Strategically located in high-traffic areas with extended operating hours, making them ideal for quick, emergency, or late-night purchases.
  • Pharmacies: Offer in-person advice from pharmacists or sales representatives, along with testers or sample sizes, which is helpful for consumers with sensitive skin or strong body odor.
  • Online Stores: Offer an expansive range of brands and types and allow customers to easily compare prices, ingredients, and reviews.
  • Others: Includes additional retail and distribution channels.

Breakup by Packaging Type

  • Metal: Durable and resistant to damage during handling and transportation, with a sleek, premium look and the ability to withstand extreme temperatures, prolonging shelf life.
  • Plastic: Cheaper to produce than glass or metal, lightweight for lower transportation costs and easy carrying, and available in a wide range of shapes, sizes, and colors.
  • Others: Includes additional packaging materials and formats.

Breakup by Region

  • Northeast: Characterized by densely populated urban centers and a relatively affluent population, driving higher consumption of personal care products and premium, specialized deodorants.
  • Midwest: Large cities with high deodorant consumption due to dense population and urban lifestyles, and a lower cost of living that allows consumers to spend more on personal care.
  • South: A warm climate makes deodorant an essential personal care item with year-round demand, and the region serves as a major retail hub with numerous distribution points.
  • West: Known for a health-conscious lifestyle that makes natural and organic deodorants popular, and a leader in eco-friendly regulations that benefit sustainable brands.

Key Growth Opportunities in the US Deodorant Market

The US deodorant market offers significant growth opportunities driven by the rising health and wellness trend, growing demand for eco-friendly and sustainable products, and the introduction of premium, gender-specific formulations. Advancements in skincare science are enabling more effective and skin-friendly products, while the proliferation of e-commerce platforms alongside physical retail in pharmacies and supermarkets is making purchasing hassle-free.

Increasing participation in sports and allied activities, along with hot and humid weather conditions, is expected to support sustained demand for long-lasting sweat and odor protection. Companies investing in natural and organic options, products with added skin benefits, and expanded retail and online distribution will be well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The US deodorant market features a competitive landscape in which leading companies are focusing on innovative product formulations, including natural and organic options, gender-specific products, and deodorants that offer added benefits such as skin moisturizing. The report provides a comprehensive analysis of the competitive landscape, along with detailed profiles of all major companies operating in the space.

Companies are adopting sustainable practices such as biodegradable packaging and lower-carbon manufacturing, investing heavily in market research to understand consumer preferences and unmet needs, and building strong brand identities through campaigns featuring social media influencers, celebrities, and athletes. Strategic partnerships with both online and brick-and-mortar retailers are also helping ensure wider distribution and product availability.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Luxury Furniture Market Size, Demands, Growth Analysis, Industry Report 2026-2034

United States Luxury Furniture Market Size, Demands, Growth Analysis, Industry Report 2026-2034

IMARC Group has recently released a report titled “United States Luxury Furniture Market Report by Raw Material (Wood, Metal, Glass, Leather, Plastic, Multiple, and Others), Application (Domestic, Commercial), Distribution Channel (Conventional Furniture Stores, Specialty Stores, Online Retailers, and Others), Design (Modern, Contemporary), and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Luxury Furniture Market Size and Forecast 2026–2034

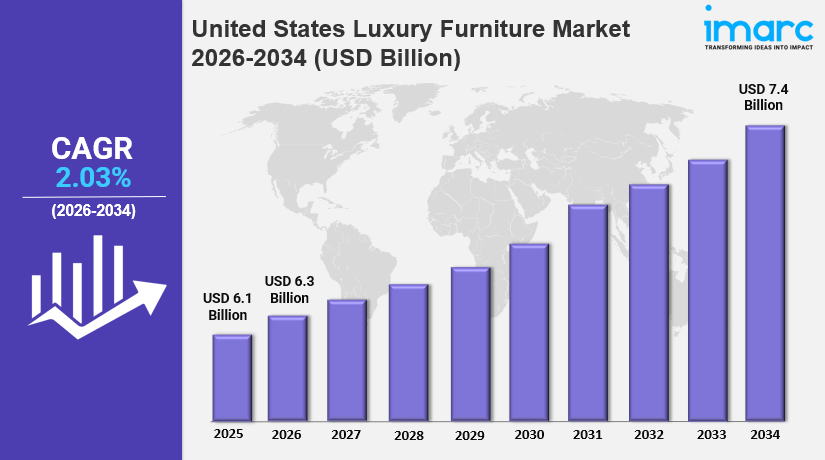
The United States luxury furniture market size increased from USD 6.1 Billion in 2025 to USD 6.3 Billion in 2026 and is projected to reach USD 7.4 Billion by 2034, exhibiting a CAGR of 2.03% during 2026–2034. The market is growing due to growing economic prosperity, changing lifestyle preferences, rapid urbanization, rising awareness about design, emerging e-commerce and rapid digitalization, increasing sustainability and eco-consciousness, introduction of customization and personalization options, and rising renovation and remodeling activity.

In 2026, the United States luxury furniture market growth is being fueled by the nation’s broader economic health, with high gross domestic product, low unemployment, and rising disposable incomes creating a firm foundation for consumers to pursue high-end home decor. For many buyers, luxury furniture represents an expression of personal taste and social standing, creating demand for statement pieces that combine elegance with durability, while continued urbanization is prompting manufacturers to create smaller, multifunctional solutions that retain a luxurious sensibility for space-constrained city living.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 6.1 Billion
  • Market Size (2026): USD 6.3 Billion
  • Projected Size (2034): USD 7.4 Billion
  • Growth Rate: CAGR of 2.03%

Explore Opportunities in the United States Luxury Furniture Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-luxury-furniture-market/requestsample

United States Luxury Furniture Market Growth: Key Trends and Market Insights

The United States luxury furniture market growth is supported by increased cultural sensitivity toward design, as consumers appreciate furniture that expresses identity, imagination, and lifestyle choices rather than serving function alone. Technological advancement is also revolutionizing how individuals engage with high-end brands, with online platforms and virtual showrooms providing ease of access to collections, side-by-side comparisons, and judicious purchases from home, helping businesses reach underserved markets and tech-savvy consumers.

Key United States luxury furniture market trends include rising demand for sustainably produced and environmentally friendly furniture, pushing businesses to adopt certified sustainable materials, minimize manufacturing waste, and incorporate low-emission technologies. Customization has also become a major market differentiator, with buyers requesting furniture tailored to their personal style across material, size, and styling details, adding emotional value to each purchase and reshaping brand competitiveness across the industry.

The United States luxury furniture market growth is also being supported by rising interest from millennial and Gen Z consumers who prioritize style and self-expression, fueling demand for customized items that balance appearance and functionality. Hybrid work patterns have spurred home remodeling and interior refashioning spending on high-end furniture that improves comfort and aesthetic appeal, while international luxury houses are entering the U.S. market through online platforms and limited retail partnerships, bringing new designs to a sophisticated consumer base through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20173&flag=C

United States Luxury Furniture Market Segmentation Analysis

The United States luxury furniture market is segmented by raw material, application, distribution channel, design, and region, offering a comprehensive view of material preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Raw Material

  • Wood: A core material valued for craftsmanship, durability, and timeless appeal across luxury furniture pieces.
  • Metal: Used for structural and decorative elements that add contemporary sophistication.
  • Glass: Incorporated for sleek, modern aesthetics in tables, cabinets, and decorative accents.
  • Leather: A hallmark of luxury upholstery, valued for texture, durability, and refined appearance.
  • Plastic: Used in select modern and outdoor luxury furniture applications for versatility.
  • Multiple: Combines several materials to create distinctive, statement-making designs.
  • Others: Include additional specialty materials used in luxury furniture manufacturing.

Breakup by Application

  • Domestic: The leading application, covering residential luxury furniture needs, sub-categories include:
    • Living Room and Bedroom: Represents core residential luxury furniture demand for statement seating and bedroom pieces.
    • Kitchen: Covers high-end cabinetry and kitchen furnishing elements.
    • Bathroom: Includes premium vanities and bathroom furniture fixtures.
    • Outdoor: Benefits from rising demand for luxury patio and garden furniture collections.
    • Lighting: Covers decorative and statement lighting fixtures within luxury interiors.
  • Commercial: Serves business and hospitality furnishing needs, sub-categories include:
    • Office: Covers premium furnishing for corporate and executive office spaces.
    • Hospitality: Serves hotels, resorts, and upscale dining establishments.
    • Others: Include additional commercial luxury furniture applications.

Breakup by Distribution Channel

  • Conventional Furniture Stores: Offer in-person browsing and hands-on evaluation of luxury furniture pieces.
  • Specialty Stores: Provide curated collections and personalized service for discerning luxury buyers.
  • Online Retailers: Growing rapidly through virtual showrooms and digital platforms that simplify browsing and purchasing.
  • Others: Include additional channels such as designer showrooms and direct brand outlets.

Breakup by Design

  • Modern: Features clean lines and minimalist aesthetics appealing to contemporary sensibilities.
  • Contemporary: Reflects current design trends with a focus on comfort, functionality, and evolving style preferences.

Breakup by Region

  • Northeast: A significant market supported by dense urban centers and strong demand for space-efficient luxury pieces.
  • Midwest: Benefits from steady demand across metropolitan hubs and growing renovation activity.
  • South: A large regional market supported by population growth and expanding residential construction.
  • West: Benefits from strong design awareness and demand for contemporary and sustainable luxury furniture.

Key Challenges and Growth Opportunities in the United States Luxury Furniture Market

The United States luxury furniture market faces several challenges that could affect its growth, including supply chain disruptions affecting the sourcing of high-quality raw materials, variability in consumer spending during periods of economic instability that can impact discretionary purchases, and growing competition from international and domestic luxury brands applying pressure on pricing and requiring stronger differentiation. Balancing traditional craftsmanship with contemporary demands for convenience, sustainability, and digital interaction presents an additional challenge for established manufacturers.

Despite these challenges, the market offers significant growth opportunities driven by rising millennial and Gen Z interest in personalized, style-forward furnishings, expanding digital platforms and virtual showrooms that deepen customer relationships, and growing demand for green luxury furniture built from sustainably sourced materials. Home remodeling driven by hybrid work patterns and the entry of international luxury houses through online and limited retail partnerships are expected to further support market expansion through 2034.

Competitive Landscape

The United States luxury furniture market features a competitive landscape comprising established luxury furniture brands, specialty retailers, and designer collaborations serving discerning residential and commercial buyers. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the market.

Market participants are competing through designer collaborations, expanded customization options, and sustainable material sourcing to differentiate their offerings. Companies are also investing in digital showrooms and e-commerce capabilities to reach broader and increasingly tech-savvy consumer segments while preserving the exclusivity associated with luxury positioning.

Latest News and Developments

  • March 2025: McGee & Co. unveiled its 2025 Outdoor Collection, blending classic luxury with resort-inspired design, featuring weather-resistant lounge chairs, striped pillow covers, and sophisticated melamine tableware for porches and patios.
  • February 2025: Crate & Barrel introduced a 54-piece designer luxury furniture collection in collaboration with designer Brigette Romanek, featuring daybeds, velvet sofas, and sculptural beds reflecting a “livable but luxe” philosophy.
  • October 2024: Albany Park introduced the Barton Chaise Sectional, a made-to-order luxury seating item with deep-plush cushions, pet- and child-friendly materials, vegan upholstery, and a handcrafted North American frame backed by a lifetime guarantee.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Logistics Market Size, Share, Industry Overview, Latest Trends and Forecast 2026-2034

Mexico Logistics Market Size, Share, Industry Overview, Latest Trends and Forecast 2026-2034

IMARC Group has recently released a report titled “Mexico Logistics Market Size, Share, Trends and Forecast by Model Type, Transportation Mode, End Use, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

Mexico Logistics Market Size and Forecast 2026–2034

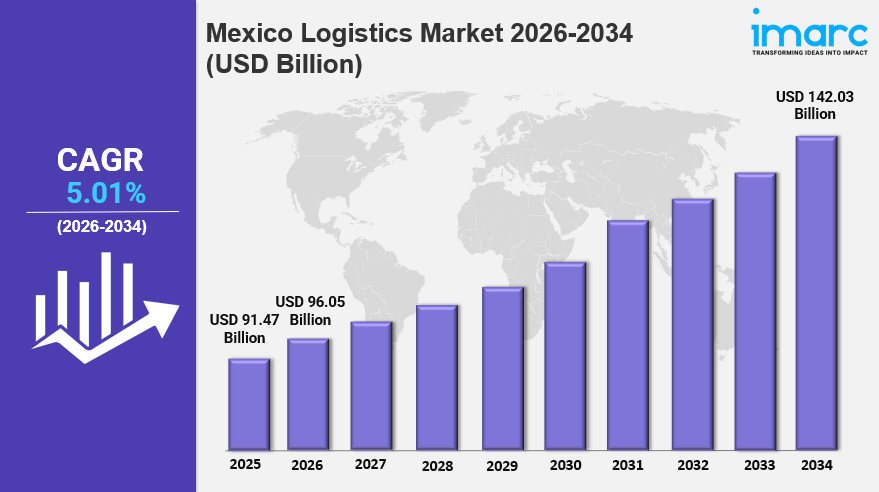
The Mexico logistics market size increased from USD 91.47 Billion in 2025 to USD 96.05 Billion in 2026 and is projected to reach USD 142.03 Billion by 2034, exhibiting a CAGR of 5.01% during 2026–2034. The market is driven by Mexico’s strategic geographic positioning as a gateway for North American trade, accelerating nearshoring activities from multinational corporations, and the rapid expansion of e-commerce platforms demanding efficient last-mile delivery solutions. Rising adoption of third-party logistics providers and multimodal transportation networks is further strengthening operational efficiency across diverse industries.

In 2026, the Mexico logistics market growth is being fueled by continued nearshoring-driven demand for warehousing, freight services, and customs clearance across major industrial corridors, alongside large-scale infrastructure and technology investment. In September 2025, Amazon, Mercado Libre, and GEODIS announced a combined USD 1.1 Billion investment in the State of Mexico’s logistics sector to expand distribution centers and logistics infrastructure. Rapid digitalization of retail channels, ongoing highway, port, and railway modernization, and growing adoption of smart logistics technologies are further improving operational visibility and efficiency across the supply chain ecosystem.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 91.47 Billion
  • Market Size (2026): USD 96.05 Billion
  • Projected Size (2034): USD 142.03 Billion
  • Growth Rate: CAGR of 5.01%

Explore Opportunities in the Mexico Logistics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-logistics-market/requestsample

Mexico Logistics Market Growth: Key Trends and Market Insights

The Mexico logistics market growth is supported by digital transformation and smart logistics adoption, as artificial intelligence, IoT sensors, and blockchain solutions gain widespread implementation. Logistics providers are deploying real-time tracking systems, predictive analytics platforms, and automated warehouse management solutions, while cloud-based logistics platforms enable seamless coordination between stakeholders. In October 2025, Salesforce announced a USD 1 Billion investment in Mexico to expand AI-driven operations and establish a Global Delivery Center, accelerating digital transformation across industries, alongside growing exploration of autonomous guided vehicles and drone delivery for last-mile operations.

Key Mexico logistics market trends include the expansion of multimodal transportation networks combining road, rail, sea, and air freight to optimize cost, delivery timelines, and cargo specifications while reducing environmental impact. In June 2025, the 73-hectare U.A.C Logistics Park was inaugurated near Veracruz port, enhancing Mexico’s global supply chains and supporting multimodal transport. Strategic investments in port infrastructure and railway connectivity continue to strengthen the backbone of multimodal networks, enabling comprehensive door-to-door services for manufacturing, retail, and e-commerce sectors.

The Mexico logistics market growth is also being supported by sustainability and green logistics initiatives, including the transition toward electric and alternative fuel vehicles, energy-efficient warehouse designs, and solar power installations. In May 2025, GEODIS and Prologis launched a 619 kW rooftop solar project at Prologis Park Grande in Tepotzotlán, generating approximately 892 MWh annually to advance sustainable logistics in Mexico. Route optimization algorithms and packaging innovations are further reducing fuel consumption, emissions, and material waste, positioning environmentally responsible providers for competitive advantage through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=16217&flag=C

Mexico Logistics Market Segmentation Analysis

The Mexico logistics market is segmented by model type, transportation mode, end use, and region, offering a comprehensive view of demand drivers, operational preferences, and regional dynamics across the country.

Breakup by Model Type

  • 3 PL: Dominates with a 46% share in 2025, as manufacturers and retailers increasingly outsource complex supply chains to specialized providers to optimize costs, improve scalability, and enhance service flexibility. In December 2025, DP World opened a 117,000-square-foot multi-customer warehouse in Querétaro, strengthening 3PL capabilities and supporting nearshoring-driven demand.
  • 2 PL: Covers asset-based transportation and warehousing services provided directly to shippers without the broader integration offered by 3PL and 4PL models.
  • 4 PL: Serves businesses seeking fully integrated supply chain management and strategic oversight across multiple logistics providers.

Breakup by Transportation Mode

  • Roadways: Lead with a 59% share in 2025, supported by extensive highway networks, last-mile flexibility, and cost efficiency. In June 2025, Mexico’s SICT announced a MX$53.3 Billion investment to modernize and expand the national highway network, enhancing freight connectivity nationwide.
  • Seaways: Support international trade flows through Mexico’s major ports, benefiting from ongoing port modernization and multimodal terminal development.
  • Railways: Provide cost-efficient movement of high-volume freight, with continued investment in railway connectivity strengthening multimodal networks.
  • Airways: Serve time-sensitive and high-value cargo, supporting sectors such as electronics and healthcare that require rapid transit.

Breakup by End Use

  • Manufacturing: Represents the largest segment with an 18% share in 2025, driven by Mexico’s strength in automotive, aerospace, electronics, and consumer goods. In April 2025, Volvo announced a USD 1 Billion investment to expand its heavy-duty truck manufacturing plant in Nuevo León, reinforcing logistics demand from the sector.
  • Consumer Goods: Benefits from rising domestic consumption and distribution network expansion.
  • Retail: Driven by omnichannel strategies connecting physical stores with digital fulfillment.
  • Food and Beverages: Requires temperature-controlled and time-sensitive logistics solutions.
  • IT Hardware: Supported by growth in electronics assembly and export activities.
  • Healthcare: Demands specialized handling and regulatory-compliant distribution networks.
  • Chemicals: Requires hazardous materials handling and safety-focused logistics protocols.
  • Construction: Supported by infrastructure modernization and industrial park development.
  • Automotive: A key driver of nearshoring-related logistics demand across northern industrial corridors.
  • Telecom: Benefits from network infrastructure expansion and equipment distribution needs.
  • Oil and Gas: Requires specialized logistics for equipment and materials transport.
  • Others: Include additional sectors relying on Mexico’s expanding logistics infrastructure.

Breakup by Region

  • Northern Mexico: Dominates with a 46% share in 2025, benefiting from proximity to U.S. borders, dense maquiladora clusters, industrial parks, and established trade corridors enabling efficient cross-border freight flows through cities such as Monterrey, Tijuana, and Ciudad Juárez.
  • Central Mexico: A significant logistics hub anchored by Mexico City’s manufacturing and consumption base.
  • Southern Mexico: An emerging logistics market supported by growing industrial and infrastructure development.
  • Others: Include remaining regions where logistics infrastructure continues to expand.

Key Challenges and Growth Opportunities in the Mexico Logistics Market

The Mexico logistics market faces several challenges that could affect its growth, including infrastructure bottlenecks such as congested transportation corridors, limited port capacity, and inadequate railway connectivity in certain regions, along with border crossing delays and customs processing inefficiencies. Cargo theft and security incidents along transportation routes require substantial investment in protective measures and tracking technologies, while shortages of qualified professionals, particularly truck drivers and supply chain specialists, constrain service capacity and drive up labor costs.

Despite these challenges, the market offers significant growth opportunities driven by accelerating nearshoring and manufacturing relocation, as seen in November 2025 when Canadian company MARKDOM inaugurated a USD 25 Million manufacturing plant in Irapuato, Guanajuato, reinforcing nearshoring trends. Rapid e-commerce expansion is also creating opportunities, with DHL investing USD 60 Million in 2025 to expand its ground delivery fleet by 300 vehicles ahead of El Buen Fin. Continued infrastructure modernization and multimodal network development are expected to further support market expansion through 2034.

Competitive Landscape

The Mexico logistics market demonstrates a fragmented competitive landscape marked by the coexistence of global logistics enterprises, regional operators, and niche service providers catering to varied industry requirements. Companies compete by differentiating their service portfolios, geographic reach, technological integration, and sector-specific expertise to meet complex supply chain demands. The report provides a comprehensive analysis of the competitive landscape, including detailed profiles of major companies operating in the market.

Strategic alliances, mergers, and acquisitions continue to influence market dynamics as players aim to strengthen capabilities, scale operations, and broaden customer bases. Increasing investment in digital platforms, automation solutions, data analytics, and sustainability initiatives highlights shifting competitive priorities and long-term value creation strategies across the logistics ecosystem.

Latest News and Developments

  • December 2025: DP World opened a 117,000-square-foot multi-customer warehouse in Querétaro, enhancing 3PL capabilities and strengthening integrated supply chain services for manufacturers across Mexico.
  • November 2025: Canadian company MARKDOM inaugurated a USD 25 Million manufacturing plant in Irapuato, Guanajuato, expanding production capacity and reinforcing nearshoring trends.
  • October 2025: Salesforce announced a USD 1 Billion investment in Mexico to expand AI-driven operations, establish a Global Delivery Center, and accelerate digital transformation across industries.
  • September 2025: Amazon, Mercado Libre, and GEODIS announced a combined USD 1.1 Billion investment in the State of Mexico’s logistics sector, expanding distribution centers and infrastructure.
  • June 2025: Amazon Mexico partnered with Rappi to launch Amazon Now, delivering over 5,000 essential products in under 15 minutes across Mexico’s 10 largest cities, integrating restaurant orders alongside ultrafast e-commerce fulfillment.
  • June 2025: The 73-hectare U.A.C Logistics Park was inaugurated near Veracruz port, enhancing multimodal transport capacity and supporting Mexico’s global supply chains.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
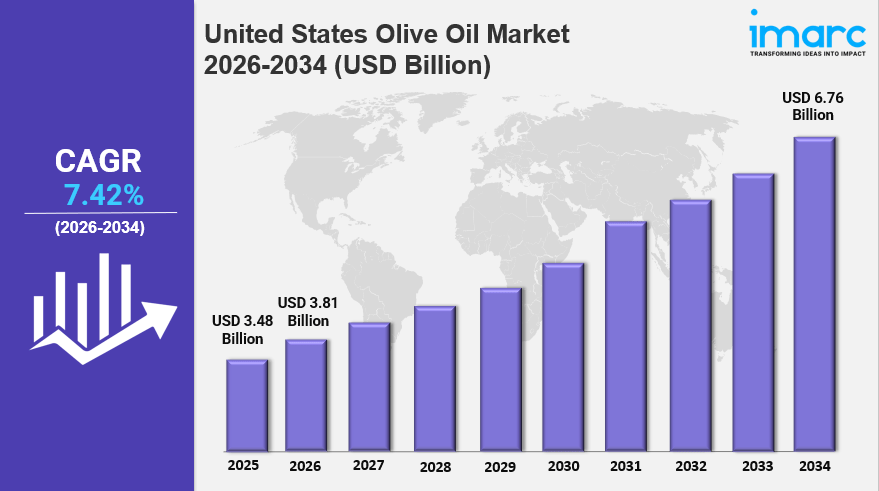
United States Olive Oil Market Size to Worth USD 6.76 Billion by 2034

United States Olive Oil Market Size to Worth USD 6.76 Billion by 2034

IMARC Group has recently released a report titled “United States Olive Oil Market Size, Share, Trends and Forecast by Type, Distribution Channel, Application, and Region 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Olive Oil Market Size and Forecast 2026–2034

The United States olive oil market size increased from USD 3.48 Billion in 2025 to USD 3.81 Billion in 2026, and is projected to reach USD 6.76 Billion by 2034, growing at a CAGR of 7.42% during 2026–2034. Rising health consciousness among consumers, the surging popularity of the Mediterranean diet, and expanding applications of olive oil across food, cosmetics, and pharmaceutical sectors are key growth drivers.

The United States olive oil market share is led by the West region, which accounted for 34.2% in 2025, while extra virgin olive oil represented 48.7% of type demand. The food and beverage segment dominated applications with a 76.5% share. Growing premiumization, demand for authentic Mediterranean and single-origin varieties, and increasing domestic production in California are further supporting market expansion.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 3.48 Billion
  • Market Size (2026): USD 3.81 Billion
  • Projected Size (2034): USD 6.76 Billion
  • Growth Rate: CAGR of 7.42%

Explore Opportunities in the United States Olive Oil Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-olive-oil-market/requestsample

United States Olive Oil Market Overview

Olive oil is a premium edible oil extracted from fresh olives, predominantly imported from Mediterranean countries including Spain, Italy, Greece, and Tunisia, with at least 97% of the US supply derived from imports. The market ecosystem spans producers and exporters in Mediterranean growing regions, import distributors, domestic California producers, food manufacturers, and retail and foodservice channels serving household, commercial, cosmetic, and pharmaceutical applications. Rising per-capita health expenditure, growing awareness of cardiovascular disease prevention, and the mainstreaming of the Mediterranean dietary pattern are primary growth catalysts, with the US having overtaken Spain to become the world’s second-largest olive oil consumer for the first time in 2023.

Market Drivers

  • Rising Health Consciousness: Olive oil’s documented cardiovascular benefits are driving consistent consumer trading-up from conventional cooking oils, with a large majority of Americans expecting to cook as much or more in the year ahead, sustaining retail demand for premium varieties.
  • Mediterranean Diet Popularity: Endorsed by leading nutrition organizations and consistently ranked among the healthiest dietary patterns, the Mediterranean diet has elevated olive oil from a specialty product to a household staple across income brackets.
  • Expanding Foodservice Sector: Foodservice and restaurant channels account for roughly 40% of bulk olive oil purchases in the US, with major chains reformulating menus around olive oil as a core cooking ingredient.
  • E-Commerce Growth: Online retail is expanding rapidly as a distribution channel for premium olive oil, giving consumers access to specialty, organic, and single-origin varieties not typically stocked by conventional supermarkets.

United States Olive Oil Market Growth: Key Trends and Market Insights

The United States olive oil market growth is being supported by increasing consumer awareness of healthy dietary choices and the nutritional benefits associated with olive oil. Consumers are increasingly incorporating olive oil into everyday cooking, salad dressings, marinades, and other food preparations as interest in heart-healthy and natural ingredients continues to rise. Growing awareness of Mediterranean dietary patterns is also encouraging demand for high-quality olive oil, particularly among health-conscious consumers seeking products perceived as natural, minimally processed, and rich in beneficial compounds.

The United States olive oil market trends are increasingly characterized by premiumization and rising consumer preference for extra virgin olive oil. Consumers are showing greater interest in authentic Mediterranean products, single-origin varieties, traceability, quality certifications, and distinctive flavor profiles. Extra virgin olive oil accounted for 48.7% of type demand in 2025, reflecting its strong position within the market. The food and beverage segment also remained the leading application, accounting for 76.5% share, supported by the widespread use of olive oil across households, restaurants, food manufacturers, and other foodservice establishments.

Another important factor supporting market development is the expansion of domestic olive oil production, particularly in California, alongside increasing availability of imported premium products. The West region led the market with a 34.2% share in 2025, benefiting from established production capabilities and strong consumer demand. Rising consumption, product diversification, premium offerings, and growing interest in authentic and single-origin oils are expected to create further opportunities for producers, retailers, and foodservice businesses across the United States.

United States Olive Oil Market Segmentation Analysis

The United States olive oil market is segmented by type, distribution channel, application, and region, offering a comprehensive view of consumer preferences, purchasing behavior, and regional dynamics across the country.

Breakup by Type

  • Extra Virgin Olive Oil: Leads the market with a 48.7% share in 2025 and the fastest growth at an 8.8% CAGR, reflecting premium positioning driven by superior nutritional composition, higher polyphenol content, and authentic flavor.
  • Virgin Olive Oil: Holds an 18.9% share, valued for its purity and cold-press processing without chemical refinement, suited to moderate-temperature cooking and finishing dishes.
  • Refined Olive Oil: Accounts for 14.6% of the market, primarily serving food manufacturing and commercial foodservice where a neutral flavor and higher smoke point are preferred.
  • Olive Pomace Oil and Others: Round out the type segment, serving industrial and value-focused cooking applications.

Breakup by Application

  • Food and Beverage: Dominates with a 76.5% share in 2025, spanning household retail cooking oil, restaurant and foodservice use, food manufacturing for dressings and marinades, and snack production.
  • Cosmetics: Accounts for 11.8% of demand, reflecting olive oil’s growing use in premium skincare, hair care, and beauty formulations valued for emollient and antioxidant properties.
  • Pharmaceuticals: Holds a 7.9% share, growing as olive oil is increasingly incorporated into supplement formulations, topical products, and pharmaceutical-grade excipients.
  • Others: Cover additional industrial and specialty uses of olive oil.

Breakup by Distribution Channel

  • Supermarkets and Hypermarkets: Remain the primary channel for mainstream olive oil purchases, offering broad accessibility and everyday convenience.
  • Online Stores: A fast-growing channel enabling access to specialty, organic, and single-origin varieties through curated digital platforms and subscriptions.
  • Convenience Stores and Others: Support broader distribution reach, particularly for everyday and value-tier products.

Breakup by Region

  • West – 34.2%: Led by California’s domestic production, high per-capita consumption, and strong demand for organic and specialty olive oils.
  • Northeast – 25.6%: Supported by urban gourmet food culture, specialty retailers, EVOO demand, and Mediterranean restaurant presence.
  • South – 22.4%: Experiencing strong consumption growth, expanding Mediterranean cuisine, and well-developed Gulf Coast import networks.
  • Midwest – 17.8%: Showing rapid growth through supermarket distribution, increasing availability, and rising private-label olive oil adoption.

Competitive Landscape

The United States olive oil market is moderately fragmented, with the top five players — Deoleo, Gallo Worldwide, Cargill Incorporated, Ybarra, SOVENA, and California Olive Ranch, Inc. — collectively holding approximately 40–50% of total market revenue in 2025. Deoleo leads the market through its Bertolli, Carbonell, and Carapelli brands, maintaining a steady market share through its Mediterranean sourcing network. Gallo Worldwide focuses on premium and organic EVOO positioning, while Cargill leverages its agricultural commodity scale to supply refined and bulk olive oil to food manufacturers and foodservice operators. California Olive Ranch continues to build market share through domestic production, freshness positioning, and traceability. A diverse mix of Mediterranean export brands, California producers, specialty importers, and private-label retailers accounts for the remaining share, sustaining a competitive landscape that rewards both scale and quality differentiation. The report provides a comprehensive analysis of the competitive landscape, including detailed profiles of all major companies operating in the market.

Author: IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
United States Crop Protection Chemicals Market Size to Hit USD 25.3 Billion by 2034 | Growth at 3.88% CAGR

United States Crop Protection Chemicals Market Size to Hit USD 25.3 Billion by 2034 | Growth at 3.88% CAGR

IMARC Group has recently released a report titled “United States Crop Protection Chemicals Market Size, Share, Trends, and Forecast by Type, Origin, Application, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

United States Crop Protection Chemicals Market Size and Forecast 2026–2034

The United States crop protection chemicals market size grew from USD 17.9 Billion in 2025 to USD 18.6 Billion in 2026, and is projected to reach USD 25.3 Billion by 2034, exhibiting a CAGR of 3.88% during 2026–2034. The United States crop protection chemicals market share is led by the Midwest, which held a significant share in 2025. Growth is being driven by increasing agricultural productivity, advanced farming practices, genetically modified crops, rising pest resistance, and climate variability.

Market expansion is further supported by growing food demand associated with population growth, encouraging farmers to increase their use of herbicides, insecticides, and fungicides. The adoption of precision agriculture, including GPS-guided equipment and remote sensing, enables more targeted chemical application. Meanwhile, genetically modified corn, soybean, and cotton varieties, alongside regulatory and R&D investments in lower-toxicity formulations, are reinforcing long-term market growth through 2034.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 17.9 Billion
  • Market Size (2026): USD 18.6 Billion
  • Projected Size (2034): USD 25.3 Billion
  • Growth Rate: CAGR of 3.88%

Explore Opportunities in the United States Crop Protection Chemicals Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-crop-protection-chemicals-market/requestsample

United States Crop Protection Chemicals Market Growth: Key Trends and Market Insights

The United States crop protection chemicals market trends are increasingly influenced by population growth, precision agriculture adoption, and technological innovation. Rising food demand is encouraging farmers to improve crop yields and protect harvests from pests, diseases, and weeds, supporting consistent demand for crop protection solutions.

The United States crop protection chemicals market growth is also being supported by the expanding adoption of precision farming technologies, including GPS mapping, drone-based spraying, and variable-rate application. These technologies enable farmers to apply crop protection inputs more efficiently while reducing waste and improving productivity.

Continued innovation is further strengthening market expansion, with manufacturers and regulators focusing on effective, environmentally responsible formulations. The development of broad-spectrum and resistance-management solutions is supporting improved efficacy, safety, and sustainability while helping the industry respond to evolving agricultural and environmental requirements.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20483&flag=C

United States Crop Protection Chemicals Market Segmentation Analysis

The United States crop protection chemicals market is segmented by type, origin, application, and region, offering a comprehensive view of demand drivers, product preferences, and regional dynamics across the country.

Breakup by Type

  • Herbicides: Hold the leading share at 43.7% in 2025, supported by the vast scale of commercial farming and the high prevalence of weed-related crop loss, reinforced by wider adoption of herbicide-tolerant GM crops.
  • Insecticides: Remain essential for managing recurring pest pressure across major row crops, particularly as unpredictable weather patterns raise the risk of pest outbreaks.
  • Fungicides: Continue to gain traction as growers seek protection against foliar and soil-borne diseases that threaten yield and quality.
  • Others: Include nematicides, rodenticides, and plant growth regulators used in targeted crop-protection programs.

Breakup by Origin

  • Synthetic: Leads the market with a 78.3% share in 2025, owing to its proven effectiveness, broad-spectrum action, cost-efficiency, and compatibility with genetically modified crop varieties.
  • Bio-based: Gaining ground as growers and regulators favor lower-toxicity, environmentally responsible alternatives alongside conventional chemistries.

Breakup by Application

  • Grains and Cereals: Lead the market with a 38.9% share in 2025, reflecting the vast cultivation area and critical role of corn, wheat, and rice in domestic consumption, animal feed, and exports.
  • Pulse and Oilseeds: Benefit from steady demand for protein and oil crops requiring consistent pest and disease management.
  • Fruits and Vegetables: See growing chemical usage tied to quality-sensitive, high-value horticultural production.
  • Commercial Crops: Cotton and other cash crops continue to drive targeted herbicide and insecticide demand.
  • Others: Cover turf, ornamentals, and additional specialty applications.

Breakup by Region

  • Midwest: Dominates the market, underpinned by large-scale corn, soybean, and wheat cultivation, widespread adoption of GM seeds, and strong uptake of precision farming technologies.
  • South: Supported by diverse cropping patterns and sustained demand for pest and weed management across row and specialty crops.
  • West: Driven by high-value fruit, vegetable, and nut production requiring intensive crop protection.
  • Northeast: A smaller but steady contributor, supported by diversified and specialty agriculture.

Key Challenges and Growth Opportunities in the United States Crop Protection Chemicals Market

The market faces challenges including tightening regulatory scrutiny from the EPA, growing resistance among target weeds and pests that reduces the efficacy of established chemistries, and the need to balance high-performance synthetic solutions with rising demand for sustainable, lower-toxicity alternatives.

Despite these challenges, the market offers significant growth opportunities driven by rising food demand, expanding precision agriculture adoption, and continued investment in R&D for resistance-management and eco-friendly formulations. Companies pursuing agri-tech partnerships, digital integration, and biological product pipelines are well positioned to strengthen their competitive position through 2034.

Competitive Landscape

The United States crop protection chemicals market is highly competitive, with major companies such as Bayer AG, Corteva Agriscience, Syngenta AG, BASF SE, and FMC Corporation dominating through extensive product portfolios and nationwide distribution networks. Leading players are investing heavily in R&D to develop eco-friendly and resistance-management solutions, including biologicals and precision-targeted chemicals, while pursuing mergers, acquisitions, and agri-tech collaborations to enhance digital integration and application efficiency. Regional players and startups are also emerging in niche segments such as biopesticides, as evolving EPA standards continue to shape competitive dynamics. The report provides a comprehensive analysis of the competitive landscape, including detailed company profiles and Porter’s Five Forces analysis.

Latest News and Developments

  • June 2025: Corteva confirmed the release of its Forcivo fungicide, combining three active ingredients to combat foliar diseases such as tar spot and southern rust in corn and soybeans, pending EPA registration.
  • May 2025: ADAMA Ltd. secured US registration for Temper More, a herbicide built on its proprietary formulation technology aimed at controlling herbicide-resistant weeds.
  • April 2025: Syngenta disclosed three new foliar-applied insecticide products — Incipio, Vertento, and Zivalgo — for in-season insect control, pending EPA approval.
  • March 2025: ADAMA US introduced Maxentis SC, a dual-active fungicide for maize, soybean, and wheat growers targeting major crop diseases.
  • January 2025: FMC launched two new herbicides, Keenali Complete and Keenali GR, powered by its Dodylex active ingredient, with staggered rollout for rice growers through 2028.

Author: IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302