Author: Deepak Mishra

Mexico Skin Care Products Market Size, Growth, Demand, Trends and Forecast 2026-2034

Mexico Skin Care Products Market Size, Growth, Demand, Trends and Forecast 2026-2034

IMARC Group has recently released a new research study titled “Mexico Skin Care Products Market Size, Share, Trends and Forecast by Product Type, Ingredient, Gender, Distribution Channel, and Region, 2026-2034“, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Skin Care Products Market Size & Share 2026-2034

The Mexico skin care products market size reached USD 2.6 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 3.6 Billion by 2034, exhibiting a growth rate of CAGR of 3.58% during 2026-2034. Rising consumer awareness of natural ingredients, rapid growth in e-commerce platforms, and increasing demand for personalized, inclusive skin care solutions are key drivers of the Mexico skin care products market outlook.

Local brands leveraging traditional botanicals and digital engagement strategies are gaining value, while technology integration enhances consumer experiences and purchasing decisions, strengthening the Mexico skin care products market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 2.6 Billion
  • Projected Market Size (2034): USD 3.6 Billion
  • Growth Rate: CAGR of 3.58% (2026-2034)

Explore Opportunities in the Mexico Skin Care Products Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-skin-care-products-market/requestsample

Key Growth Drivers and Trends in the Mexico Skin Care Products Market

Growth in the Mexico skin care products market is being driven by growing demand for natural and organic products, as Mexican consumers become more attracted to skin care items focused on natural and organic ingredients. Increased concern regarding strong chemicals has spurred a movement toward clean beauty, with paraben-free, sulfate-free, and artificial-free products bolstering market growth, while locally sourced products with classic botanical extracts such as aloe vera, avocado oil, and nopal (cactus) are well received for their cultural recognition and documented skin benefits.

One of the leading Mexico skin care products market trends is digital transformation and e-commerce expansion, with social media and e-commerce revolutionizing how consumers discover and purchase products. Platforms like TikTok, Instagram, and YouTube play a major role in influencing consumer choices, particularly through beauty influencers, with Mexican micro-influencers highly active in beauty, shopping, and lifestyle categories. Brands are investing in influencer marketing, improving digital presence, and providing AI-enabled features such as virtual try-ons and customized product suggestions.

Another key factor supporting Mexico skin care products market growth is the emphasis on personalization and inclusivity, as consumers increasingly look for products that address specific skin concerns such as acne, hyperpigmentation, or sensitivity. Brands are responding with customized routines, skin analysis tools, and targeted formulations, alongside growing demand for inclusivity through diverse product ranges accommodating various skin tones, types, and cultural backgrounds.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32112&flag=C

Mexico Skin Care Products Industry Segmentation Insights

Breakup by Product Type:

  • Face Cream: Includes skin brightening cream, anti-aging cream, and sun protection cream, addressing diverse skin care needs.
  • Body Lotion: Includes mass body care, premium body care, and others, catering to varied consumer price preferences.

Breakup by Ingredient:

  • Chemical: Remains a widely used category valued for consistent formulation and cost-effectiveness.
  • Natural: Gaining traction rapidly amid rising demand for clean beauty and botanical-based products.

Breakup by Gender:

  • Male: Growing segment reflecting rising grooming awareness among male consumers.
  • Female: Represents the leading segment driven by broad and diverse skin care product usage.
  • Unisex: Expanding through demand for inclusive, gender-neutral skin care formulations.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Provides broad accessibility and a wide selection of skin care brands.
  • Beauty Parlours and Salons: Offers professional guidance and premium product recommendations.
  • Multi Branded Retail Stores: Supports curated selections across multiple skin care brands.
  • Online: Growing rapidly through e-commerce platforms and social media-driven discovery.
  • Exclusive Retail Stores: Provides brand-focused shopping experiences for dedicated consumers.
  • Others: Includes additional retail and distribution channels serving the market.

Breakup by Region:

  • Northern Mexico: Benefits from a strong urban and retail base supporting skin care demand.
  • Central Mexico: Holds a significant share supported by dense urban population and beauty-conscious consumers.
  • Southern Mexico: An emerging region with growing retail investment supporting skin care demand.
  • Others: Comprises smaller regional markets experiencing gradual growth in adoption.

Key Challenges and Growth Opportunities in the Mexico Skin Care Products Market

The Mexico skin care products market faces challenges including the technical complexity of formulating effective natural and clean-label products that match the performance of conventional formulations, along with intensifying competition from both domestic brands and international entrants expanding their retail presence.

Despite these challenges, the market offers considerable growth opportunities driven by continued demand for natural and organic products, rising e-commerce and influencer-driven marketing, and growing emphasis on personalized and inclusive beauty solutions. Continued investment in digital engagement and product innovation is expected to create substantial opportunities for long-term growth in the Mexico skin care products market.

Competitive Landscape

The Mexico skin care products market is competitive, with established and emerging brands focusing on product innovation, digital engagement, and retail expansion to strengthen their market position. Recent entries such as E.L.F. Cosmetics at Sephora Mexico and Ulta Beauty’s planned joint venture with Grupo Axo highlight growing international interest in the Mexican beauty retail landscape.

Author

IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Spectrometry Market Share, Size, In-Depth Analysis and Forecast 2026-2034

Mexico Spectrometry Market Share, Size, In-Depth Analysis and Forecast 2026-2034

IMARC Group has recently released a new research study titled “Mexico Spectrometry Market Size, Share, Trends and Forecast by Type, Product, Application, End User, and Region, 2026-2034“, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Spectrometry Market Size & Share 2026-2034

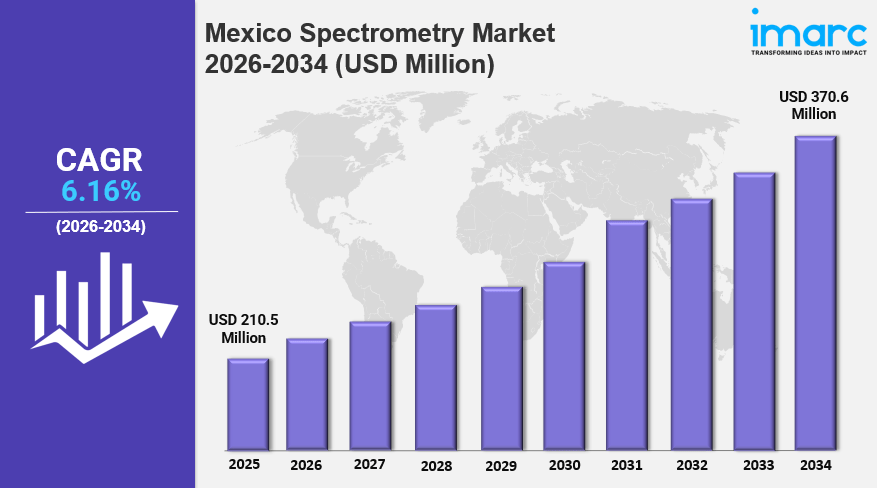
The Mexico spectrometry market size reached USD 210.5 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 370.6 Million by 2034, exhibiting a growth rate of CAGR of 6.16% during 2026-2034. Tighter environmental regulations, increased industrial complexity, and growing emphasis on pollutant detection are driving analytical adoption, while rising pharmaceutical research activity, expanded clinical trials, and public-private investments are enhancing instrumentation demand.

Strategic biotech partnerships, improved data accuracy requirements, and high-throughput research integration are strengthening the Mexico spectrometry market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 210.5 Million
  • Projected Market Size (2034): USD 370.6 Million
  • Growth Rate: CAGR of 6.16% (2026-2034)

Explore Opportunities in the Mexico Spectrometry Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-spectrometry-market/requestsample

Key Growth Drivers and Trends in the Mexico Spectrometry Market

Growth in the Mexico spectrometry market is being driven by increasing industrial and environmental applications, as regulatory bodies intensify monitoring requirements across sectors such as mining, petrochemicals, and wastewater treatment. This heightened scrutiny necessitates precise, real-time analytical technologies, with mass spectrometry and related techniques offering unmatched sensitivity and reliability. Industrial facilities, particularly in northern Mexico, are integrating these systems into quality control and emissions tracking processes to ensure compliance with national and international standards. In November 2023, Balluff announced the opening of a new production facility in Aguascalientes, Mexico, with an investment of approximately USD 53 Million, enhancing the country’s capabilities in sensor and network technology integral to spectrometry applications.

One of the leading Mexico spectrometry market trends is the expansion of the pharmaceutical and clinical research sector, driven by increased clinical trial activity and pharmaceutical manufacturing. The country’s strategic position as a nearshore destination for U.S. biotech companies, combined with competitive labor costs and growing medical infrastructure, has positioned it as a central hub for drug discovery and validation. Mass spectrometry systems play a critical role in pharmacokinetics, toxicology, proteomics, and biomarker research, with universities and contract research organizations increasingly adopting these technologies to improve data quality and accelerate development timelines.

Another key factor supporting Mexico spectrometry market growth is the growing demand for forensic and security applications, particularly in drug enforcement and criminal investigations. Mass spectrometry, with its ability to detect trace amounts of substances with high sensitivity, is integral to forensic labs analyzing illegal drugs, explosives, and other illicit materials, with law enforcement agencies increasingly adopting these techniques to enhance the accuracy of evidence analysis and ensure compliance with international security standards.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33783&flag=C

Mexico Spectrometry Industry Segmentation Insights

Breakup by Type:

  • Molecular Spectrometry: Includes visible and ultraviolet spectroscopy, infrared spectroscopy, nuclear magnetic resonance (NMR) spectroscopy, and others.
  • Mass Spectrometry (MS): Includes MALDI-TOF, triple quadrupole, quadrupole-trap, hybrid linear ion trap orbitrap, and quadrupole-orbitrap.
  • Atomic Spectrometry: Includes atomic absorption spectroscopy (AAS), atomic emission spectroscopy (AES), atomic fluorescence spectroscopy (AFS), X-ray fluorescence (XRF), and inorganic mass spectroscopy.

Breakup by Product:

  • Instrument: Represents the core hardware category driving spectrometric analysis across industries.
  • Consumables: Reflects recurring demand for reagents, columns, and other supporting materials.
  • Services: Gaining traction through maintenance, calibration, and analytical support offerings.

Breakup by Application:

  • Proteomics: Supports advanced protein research within pharmaceutical and academic settings.
  • Metabolomics: Growing rapidly through applications in biomarker and disease research.
  • Pharmaceutical Analysis: Represents a significant share driven by drug development and quality control needs.
  • Forensic Analysis: Expanding through increased use in criminal investigations and drug enforcement.
  • Others: Comprises additional application areas across various industries.

Breakup by End User:

  • Government and Academic Institutions: Utilizes spectrometry for research, regulatory testing, and education.
  • Pharmaceutical and Biotechnology Companies: Represents a leading end-user category driven by drug discovery and validation needs.
  • Others: Includes additional end-user segments adopting spectrometry solutions.

Breakup by Region:

  • Northern Mexico: Benefits from a strong industrial and manufacturing base supporting spectrometry demand.
  • Central Mexico: Holds a significant share supported by dense urban population and research infrastructure.
  • Southern Mexico: An emerging region with growing investment supporting spectrometry demand.
  • Others: Comprises smaller regional markets experiencing gradual growth in adoption.

Key Challenges and Growth Opportunities in the Mexico Spectrometry Market

The Mexico spectrometry market faces challenges including the high cost and technical complexity of advanced analytical instruments, along with the need for skilled personnel to operate and interpret sophisticated spectrometric data across industrial, clinical, and forensic settings.

Despite these challenges, the market offers considerable growth opportunities driven by tighter environmental regulations, expanding pharmaceutical and clinical research activity, and rising demand for forensic and security applications. Continued investment in sensor technology, biotech partnerships, and analytical infrastructure is expected to create substantial opportunities for long-term growth in the Mexico spectrometry market.

Competitive Landscape

The Mexico spectrometry market is competitive, with established manufacturers focusing on product innovation, sensor and instrumentation advancement, and strategic partnerships to strengthen their market position. In November 2023, Balluff opened a new production facility in Aguascalientes, Mexico, investing approximately USD 53 Million to enhance its sensor and network technology capabilities integral to spectrometry applications.

Author

IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
U.S. Logistics Market Size, Share, Industry Trends, Growth and Forecast 2026-2034

U.S. Logistics Market Size, Share, Industry Trends, Growth and Forecast 2026-2034

IMARC Group has recently released a new research study titled “U.S. Logistics Market Size, Share, Trends and Forecast by Model Type, Transportation Mode, End Use, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

U.S. Logistics Market Size & Share 2026-2034

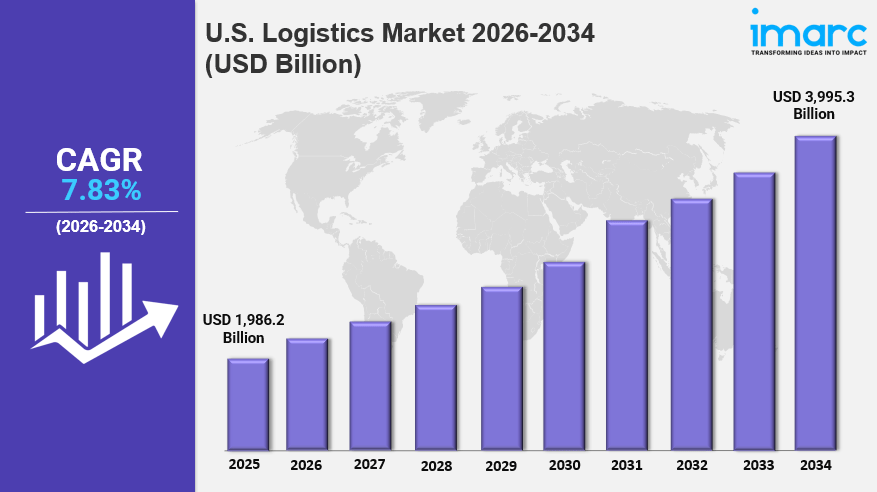
The U.S. logistics market size is anticipated to reach USD 1,986.2 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 3,995.3 Billion by 2034, exhibiting a growth rate of CAGR of 7.83% during 2026-2034. The market is driven by e-commerce growth, advancements in automation and AI, the rising demand for fast delivery, global trade expansion, and infrastructure development.

Increasing focus on supply chain optimization, real-time tracking, and sustainability significantly influence the growth of the U.S. logistics market.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 1,986.2 Billion
  • Projected Market Size (2034): USD 3,995.3 Billion
  • Growth Rate: CAGR of 7.83% (2026-2034)

Explore Opportunities in the U.S. Logistics Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-logistics-market/requestsample

Key Growth Drivers and Trends in the U.S. Logistics Market

Growth in the U.S. logistics market is being driven by e-commerce growth, as the quick rise in e-commerce remains an essential driver, with the US Census Bureau reporting an estimated USD 300.1 Billion in retail e-commerce sales in the third quarter of 2024, up 7.4% from the same quarter in 2023 and accounting for 16.2% of all retail sales. The increasing consumer demand for fast, reliable delivery has increased the need for efficient supply chain operations, including last-mile delivery solutions, with businesses investing in advanced technologies and fulfillment networks to meet same-day and next-day delivery expectations.

One of the leading U.S. logistics market trends is significant technological advancements, with automation, artificial intelligence, and the Internet of Things transforming logistics operations. In March 2024, Walmart Commerce Technologies launched Route Optimization, an AI-based logistics product that helps businesses optimize the efficiency of their supply chains, offering it to other companies as a Software as a Service solution. Automated warehousing, predictive analytics, and smart transportation systems enhance operational efficiency, accuracy, and cost-effectiveness.

Another key factor supporting U.S. logistics market growth is rising sustainability initiatives, as companies employ environmentally friendly procedures to satisfy customer and regulatory requirements. In August 2024, Universal Logistics Holdings, Inc. introduced its new 2025 Peterbilt 579EV into its fleet as part of ongoing sustainability initiatives, with Universal Intermodal Services, Inc. ready to reduce its carbon footprint in Southern California, reflecting the industry’s broader shift toward electric vehicles and route optimization.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20480&flag=C

U.S. Logistics Industry Segmentation Insights

Breakup by Model Type:

  • 2 PL: Involves outsourcing specific logistics functions, primarily transportation and warehousing, to a service provider.
  • 3 PL: Projected to dominate the market due to comprehensive services including transportation, warehousing, inventory management, and distribution.
  • 4 PL: Provides a complete package of supply chain management, integrating multi-3PL services under one umbrella for strategic planning and technology-driven insights.

Breakup by Transportation Mode:

  • Roadways: Offers flexibility and accessibility for last-mile deliveries and regional transportation via an extensive highway and interstate network.
  • Seaways: Facilitates international trade through major ports like Los Angeles, Long Beach, and Houston, vital for imports and exports.
  • Railways: Plays a key role in transporting bulk goods, industrial products, and long-haul shipments with cost-efficiency and high capacity.
  • Airways: Supports time-sensitive and high-value freight requiring rapid transit across long distances.

Breakup by End Use:

  • Manufacturing: Drives demand for efficient supply chains transporting raw materials and finished goods, especially across industrial hubs like the Midwest.
  • Consumer Goods: Dominates due to consistent demand for fast and reliable delivery driven by e-commerce growth.
  • Retail: Significantly influences the market through e-commerce and omnichannel strategies requiring efficient fulfillment networks.
  • Food and Beverages: Requires specialized cold chain and time-sensitive logistics solutions.
  • IT Hardware: Relies on secure, efficient logistics networks for high-value technology products.
  • Healthcare: Depends on precise, compliant logistics for pharmaceuticals and medical equipment.
  • Chemicals: Requires specialized handling and regulatory-compliant transportation solutions.
  • Construction: Relies on logistics for transporting heavy materials and equipment to project sites.
  • Automotive: Depends on just-in-time logistics for parts and finished vehicle distribution.
  • Telecom: Requires logistics support for equipment deployment and network infrastructure.
  • Oil and Gas: Relies on specialized logistics for equipment and product transportation.
  • Others: Includes additional end-use industries served by the logistics market.

Breakup by Region:

  • Northeast: Driven by dense urban populations and proximity to major ports like New York and Boston, with strong cold chain logistics demand.
  • Midwest: Fueled by its status as a manufacturing and agricultural hub with strategic distribution positioning.
  • South: Benefits from access to major ports like Houston, Miami, and New Orleans, driving global trade and logistics growth.
  • West: Thrives as a gateway for international trade through ports like Los Angeles and Long Beach, with advanced last-mile delivery systems.

Key Challenges and Growth Opportunities in the U.S. Logistics Market

The U.S. logistics market faces challenges including the technical complexity of scaling automation and AI-driven systems across diverse transportation modes, along with the need for continued investment in sustainable fleet transitions and infrastructure development.

Despite these challenges, the market offers considerable growth opportunities driven by continued e-commerce expansion, rising adoption of automation and real-time tracking technologies, and growing investment in sustainable logistics practices. Continued infrastructure development and supply chain optimization are expected to create substantial opportunities for long-term growth in the U.S. logistics market.

Competitive Landscape

The U.S. logistics market is highly competitive, with key players including FedEx, UPS, DHL, and XPO Logistics dominating the industry through technology integration, extensive networks, and service diversification. In August 2024, FedEx introduced FedEx Surround, a monitoring and intervention solution using artificial intelligence and machine learning to improve customer visibility and control over shipments, while e-commerce giants like Amazon further intensify competition with in-house logistics capabilities.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Perfume Market Size, Share, Trends, Growth Factors and Forecast 2026-2034

Mexico Perfume Market Size, Share, Trends, Growth Factors and Forecast 2026-2034

IMARC Group has recently released a report titled “Mexico Perfume Market Size, Share, Trends and Forecast by Perfume Type, Category, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.

Mexico Perfume Market Size and Forecast 2026–2034

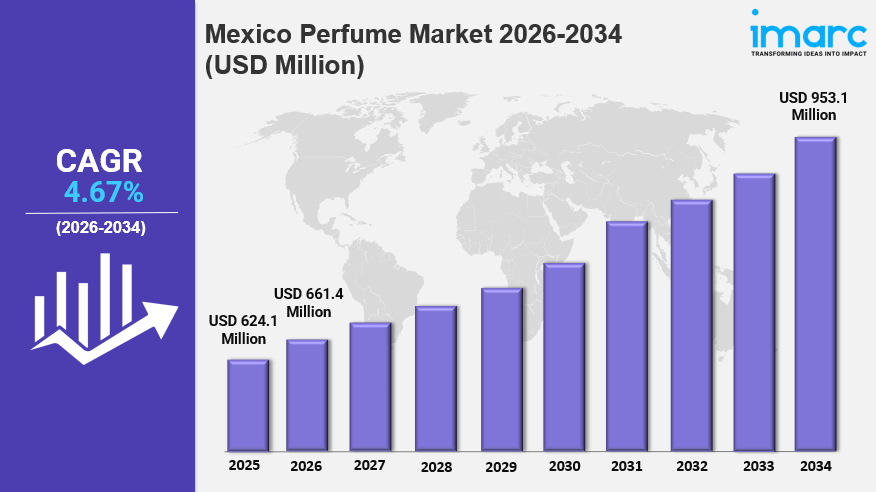
The Mexico perfume market size increased from USD 624.1 Million in 2025 to USD 661.4 Million in 2026, and is projected to reach USD 953.1 Million by 2034, exhibiting a CAGR of 4.67% during 2026–2034. Rising disposable incomes, growing consumer preference for premium and culturally resonant fragrances, and the influence of social media on purchasing behavior continue to drive market expansion. Growing e-commerce penetration and the emergence of local artisanal brands reflecting indigenous heritage are further boosting demand and product diversification.

In 2026, the Mexico perfume market growth is being fueled by the continued expansion of the country’s luxury fragrance segment, rising digital engagement through social media and e-commerce platforms, and growing consumer interest in fragrances inspired by native botanicals and cultural heritage. Strengthening middle and upper-middle-class purchasing power and increasing brand awareness among younger consumers are further broadening market reach across urban and rural regions.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020–2025
  • Forecast Period: 2026–2034
  • Market Size (2025): USD 624.1 Million
  • Market Size (2026): USD 661.4 Million
  • Projected Size (2034): USD 953.1 Million
  • Growth Rate: CAGR of 4.67%

Explore Opportunities in the Mexico Perfume Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-perfume-market/requestsample

Mexico Perfume Market Growth: Key Trends and Market Insights

The Mexico perfume market growth is supported by the continued expansion of the country’s luxury fragrance segment. An expanding middle and upper-middle class with rising disposable incomes is drawing consumers toward prestige brands that emphasize uniqueness, handcrafted quality, and custom fragrance profiles. International luxury houses and niche perfumers are entering the country with region-specific launches, including city-exclusive offerings created for Mexico City, while local high-end brands are combining traditional elements with luxury design. Designers and retailers are responding by enhancing in-store experiences and online branding to attract sophisticated, status-conscious buyers.

Key Mexico perfume market trends include the growing role of e-commerce and digital engagement in shaping how fragrances are marketed and sold. Wider internet access and smartphone penetration are pushing more consumers toward online purchasing channels, supported by tools such as virtual scent profiling alongside user-generated reviews and influencer endorsements. Platforms like Instagram and TikTok have become important channels for building brand visibility, particularly among younger buyers, and fragrance companies are increasingly relying on influencer partnerships, livestreamed launches, and targeted digital campaigns to drive engagement. This digital shift is widening accessibility across both urban and rural areas and allowing niche and independent labels to reach consumers without dedicated physical retail space.

The Mexico perfume market growth is also being supported by a rising embrace of indigenous scents and cultural heritage in fragrance formulation. Brands are increasingly drawing on native botanicals and traditional practices to create fragrances with local resonance, with several labels highlighting ingredients such as copal, agave, and native florals alongside artisan-crafted packaging that reflects Mexican craftsmanship. Younger consumers in particular are seeking fragrances that convey a story and a sense of identity, and companies blending modern perfumery techniques with ancestral elements are positioning themselves as distinctive, culturally rooted alternatives to mainstream offerings through 2034.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=32107&flag=C

Mexico Perfume Market Segmentation Analysis

The Mexico perfume market is segmented by perfume type, category, and region, offering a comprehensive view of consumer preferences, product positioning, and regional dynamics across the country.

Breakup by Perfume Type

  • Premium Perfume Products: Encompasses prestige and luxury fragrances favored by consumers seeking uniqueness, handcrafted quality, and custom scent profiles, supported by rising disposable incomes and growing brand consciousness among affluent and aspirational buyers.
  • Mass Perfume Products: Covers widely available, affordably priced fragrances catering to broad consumer segments, supported by expanding retail and e-commerce distribution across urban and rural areas.

Breakup by Category

  • Female Fragrances: Includes perfumes formulated for women, spanning floral, fruity, and gourmand profiles, with growing demand for fragrances that reflect personal identity and cultural heritage.
  • Male Fragrances: Includes perfumes formulated for men, with rising interest in premium and niche offerings as grooming and self-expression gain greater consumer attention.
  • Unisex Fragrances: Includes gender-neutral scent profiles appealing to consumers, particularly younger demographics, seeking versatile and individualized fragrance choices.

Breakup by Region

  • Northern Mexico: Benefits from strong industrial activity and rising incomes, supporting demand for premium and internationally recognized fragrance brands.
  • Central Mexico: Reflects a dense concentration of population, retail infrastructure, and affluent consumers, supporting broad adoption of both premium and mass fragrance products.
  • Southern Mexico: Represents a growing market as improving retail and digital access expand consumer exposure to fragrance brands, including regionally inspired and artisanal offerings.
  • Others: Includes additional regions where expanding e-commerce and mobile connectivity are gradually widening access to a broader range of fragrance products.

Key Challenges and Growth Opportunities in the Mexico Perfume Market

The Mexico perfume market faces several challenges that could affect its growth, including intense competition from established international fragrance houses, price sensitivity among mass-market consumers, and the risk of counterfeit or unauthorized products undermining brand trust and pricing structures.

Despite these challenges, the market offers significant growth opportunities driven by the continued expansion of e-commerce and digital marketing channels, rising consumer interest in premium and niche fragrances, and growing demand for products rooted in indigenous ingredients and cultural storytelling. Investment in localized formulations, influencer-driven engagement, and artisan-crafted packaging is expected to further support market expansion, with companies that combine authenticity, quality, and digital reach well positioned to strengthen their competitive advantage through 2034.

Competitive Landscape

The Mexico perfume market features a mix of global fragrance houses, established consumer goods companies, and emerging local artisanal brands competing across the premium and mass segments. Participants are differentiating through prestige brand positioning, culturally resonant product formulations, and expanded digital and retail engagement strategies.

The IMARC report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant, along with detailed profiles of all major companies. Companies continue to invest in production capacity, technology, and market expansion initiatives to remain competitive in the evolving Mexico perfume market.

Latest News and Developments

  • November 2024: Givaudan expanded its production facility in Pedro Escobedo, Mexico, as part of its 2025 strategy to strengthen its position in Latin America. The expansion doubled the site’s encapsulation technology production capacity, which now accounts for roughly 40% of Givaudan’s global output in this area, reinforcing the company’s leadership in the fragrance and beauty market while supporting rising regional and global demand.

Author

IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302

United States Software Market Size, Share, Latest Insights and Forecast 2026-2034

United States Software Market Size, Share, Latest Insights and Forecast 2026-2034

IMARC Group has recently released a new research study titled “United States Software Market Report by Type (Application Software, System Infrastructure Software, Development and Deployment Software, Productivity Software), Deployment Mode (On-premises, Cloud-based), Enterprise Size (Small and Medium-sized Enterprises, Large Enterprises), Industry Vertical (IT and Telecom, BFSI, Retail, Government/Public Sector, Energy and Utilities, Healthcare, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

United States Software Market Size & Share 2026-2034

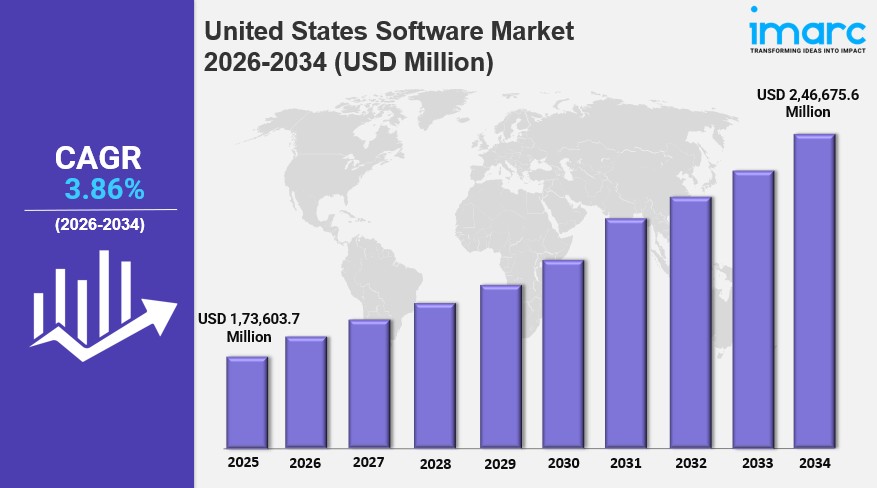
The United States software market size reached USD 1,73,603.7 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 2,46,675.6 Million by 2034, exhibiting a growth rate (CAGR) of 3.86% during 2026–2034. The growing demand in remote healthcare, patient management, and medical data analysis, increasing shift from on-premises software solutions to cloud-based services, and rising popularity of low-code and no-code development platforms represent some of the key factors driving the market.

The industry is further fueled by digital transformation, cloud computing adoption, increasing demand for automation, and artificial intelligence investment, which together drive enterprise modernization and underpin growth in scalable, intelligent technology infrastructures.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Base Year Market Size (2025): USD 173,603.7 Million
  • Forecast Market Size (2034): USD 246,675.6 Million
  • Growth Rate: CAGR of 3.86% (2026-2034)

Explore Opportunities in the United States Software Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-software-market/requestsample

Key Growth Drivers and Trends in the United States Software Market

Growth in the United States software market is being driven by the rapid and swift uptake of cloud-native software architecture, which is reshaping the software development environment as technologies such as containerization, microservices, and serverless computing allow companies to develop scalable and elastic applications optimized for fast-changing environments. Organizations across industries are increasingly betting on platforms that can deploy, observe, and manage workloads in real-time efficiently, with software vendors concentrating on providing cloud-first offerings that reflect the agile and dispersed nature of current IT infrastructures.

One of the leading United States software market trends is the incorporation of artificial intelligence within mainstream software platforms, remaking user experience, decision-making, and operational capabilities. AI-based software products, ranging from predictive analytics to natural language processing and machine learning, are increasingly integrated into enterprise applications to maximize performance and provide intelligent automation, most notably in industries such as healthcare, finance, and logistics. In May 2025, OpenAI released a research preview of Codex, an AI software engineering agent capable of writing code, debugging, running tests, and answering questions, with plans to revolutionize enterprise-scale software development processes.

Another key factor supporting market growth is the increased focus on software compliance and security, as developers and businesses integrate security protocols and compliance models natively into the software development lifecycle through DevSecOps to enable proactive risk management. This responds to both internal data governance needs and external regulatory compliance requirements including GDPR, HIPAA, and CCPA, with companies increasingly adopting security-oriented software applications to uphold user trust and prevent financial fines.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=19069&flag=C

United States Software Industry Segmentation Insights

Breakup by Type:

  • Application Software: Covers ERP, CRM, SCM, enterprise collaboration, enterprise content management, education software, and other business applications.
  • System Infrastructure Software: Includes network management systems, storage software, and security software supporting core IT operations.
  • Development and Deployment Software: Encompasses enterprise data management, business analytics and reporting tools, application servers, integration middleware, and data quality tools.
  • Productivity Software: Includes office software, creative software, and other tools supporting individual and team productivity.

Breakup by Deployment Mode:

  • On-premises: Serves organizations requiring direct infrastructure control and data residency compliance.
  • Cloud-based: Gaining wider adoption due to scalability, remote accessibility, and reduced infrastructure overhead.

Breakup by Enterprise Size:

  • Small and Medium-sized Enterprises: Increasingly adopting cloud-based and subscription software models to access enterprise-grade capabilities cost-effectively.
  • Large Enterprises: Drives substantial software investment across complex, multi-department digital transformation initiatives.

Breakup by Industry Vertical:

  • IT and Telecom: A leading vertical driving continuous software innovation and infrastructure modernization.
  • BFSI: Adopts software extensively for digital banking, risk management, and regulatory compliance.
  • Retail: Utilizes software for e-commerce, inventory management, and customer experience platforms.
  • Government/Public Sector: Invests in software for citizen services, data management, and cybersecurity infrastructure.
  • Energy and Utilities: Applies software for grid management, asset monitoring, and operational efficiency.
  • Healthcare: Growing rapidly with demand in remote healthcare, patient management, and medical data analysis software.
  • Others: Includes additional industry verticals adopting software solutions across diverse use cases.

Breakup by Region:

  • Northeast: Supported by dense concentrations of financial services and enterprise software adoption.
  • Midwest: Benefits from steady industrial and manufacturing software demand.
  • South: A growing region supported by expanding technology hubs and business relocation trends.
  • West: Leads with concentration of major technology companies and software innovation centers.

Key Challenges and Growth Opportunities in the United States Software Market

The United States software market faces challenges including ongoing data privacy issues, complex regulatory requirements, and persistent cybersecurity attacks that require continuous investment in secure software development practices.

Despite these challenges, the market offers considerable growth opportunities driven by pressure to move toward intelligent automation, edge computing, and vertical-specific SaaS solutions. Continued expansion of cloud-native architectures, AI-infused capabilities, and platform-as-a-service models is expected to support long-term growth in the United States software market.

Competitive Landscape

The United States software market is highly competitive among international and national vendors, with differentiation based on innovation velocity, integration expertise, cybersecurity level, and industry-specific tailoring to address a wide range of enterprise needs. Companies are investing heavily in AI-infused capabilities, cloud-native architectures, and compliance-focused offerings to differentiate their solutions across the enterprise software landscape.

Recent Developments in the United States Software Market

  • May 2025: OpenAI released a research preview of Codex, an AI software engineering agent capable of writing code, debugging, running tests, and answering questions, built on the codex-1 model and made available to ChatGPT Pro, Team, and Enterprise customers.
  • March 2025: OneTrust launched an AI-driven Privacy Breach Response Agent designed with Microsoft Security Copilot, automating data analysis, regulatory mapping, and compliance measures to boost organizational efficiency in handling privacy incidents.
  • July 2025: Rune Technologies debuted its AI-fueled military logistics platform, TyrOS, and raised $24 million in Series A funding, with the edge-deployed platform using deep learning to optimize supply chains, with pilot programs underway in the U.S. Army and Marine Corps.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
Mexico Managed Services Market Size, Share, Trends & Growth Report 2034

Mexico Managed Services Market Size, Share, Trends & Growth Report 2034

IMARC Group has recently released a new research study titled “Mexico Managed Services Market Size, Share, Trends and Forecast by Type, Deployment Mode, Enterprise Size, End Use, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Managed Services Market Size & Share 2026-2034

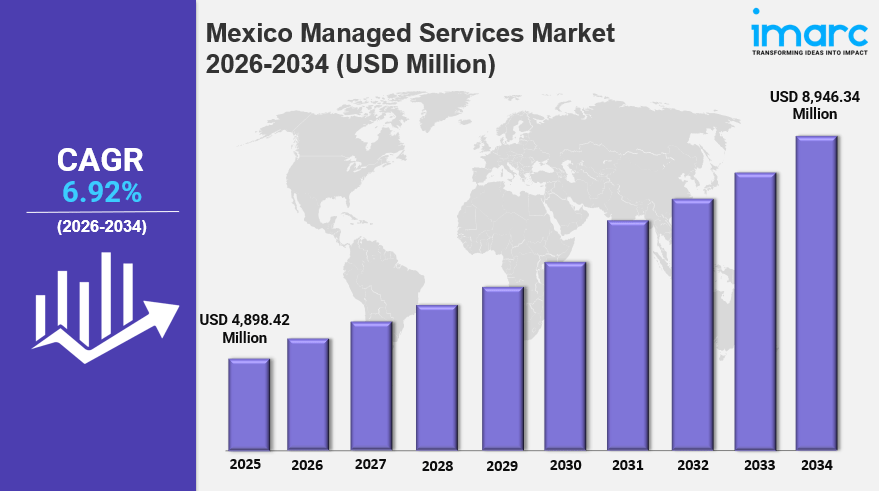
The Mexico managed services market size was valued at USD 4,898.42 Million in 2025 and is projected to reach USD 8,946.34 Million by 2034, growing at a CAGR of 6.92% from 2026-2034. Increasing demand for IT infrastructure management, cloud computing adoption, and cybersecurity solutions is driving consistent consumption as Mexican enterprises seek to optimize operations and reduce costs.

Organizations are prioritizing digital transformation initiatives, enhancing data protection capabilities, and adapting to remote work requirements, with growing emphasis on leveraging expert service providers continuing to strengthen the Mexico managed services market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 4,898.42 Million
  • Projected Market Size (2034): USD 8,946.34 Million
  • Growth Rate: CAGR of 6.92% (2026-2034)

Explore Opportunities in the Mexico Managed Services Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-managed-services-market/requestsample

Key Growth Drivers and Trends in the Mexico Managed Services Market

Growth in the Mexico managed services market is being driven by accelerated cloud migration and hybrid infrastructure adoption, as Mexican enterprises increasingly transition from conventional on-premises infrastructure to flexible hybrid cloud environments. Mexican enterprises extensively adopted cloud computing in 2025, with usage increasing over 25% annually, driven by Microsoft Azure and partners advancing AI and digital transformation, while managed service providers expand their cloud integration capabilities, offering specialized migration roadmaps, DevSecOps implementation, and ongoing hybrid infrastructure management.

One of the leading Mexico managed services market trends is rising emphasis on cybersecurity and compliance services, with cyberattacks targeting Mexican government agencies projected to surge by 260% in 2025, highlighting urgent demand for managed security services. Enterprises across all sectors are prioritizing security operations center capabilities, threat detection and response services, and compliance management solutions, while service providers expand their security portfolios to include advanced threat intelligence and regulatory compliance frameworks tailored to Mexican market requirements.

Another key factor supporting Mexico managed services market growth is the integration of artificial intelligence and automation technologies, with nearly 40% of Mexican businesses now using AI as of December 2025 and 88% noting productivity and revenue improvements. In October 2025, AWS launched three local availability zones in Mexico, supporting enterprise cloud modernization, GenAI adoption, and compliance strategies, further accelerating innovation and improving operational performance across multiple industries.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33813&flag=C

Mexico Managed Services Industry Segmentation Insights

Breakup by Type:

  • Managed Infrastructure: Leads at 22% share, driven by comprehensive outsourced management of servers, storage systems, networking equipment, and data centers.
  • Managed Data Center: Supports enterprises seeking scalable, reliable data center operations without capital-intensive investments.
  • Managed Security: Reflects growing demand for threat detection, incident response, and compliance management capabilities.
  • Managed Communications: Supports enterprise voice, messaging, and collaboration infrastructure needs.
  • Managed Network: Ensures optimized, secure, and continuously monitored enterprise network performance.
  • Managed Mobility: Supports enterprise device management and mobile workforce enablement.

Breakup by Deployment Mode:

  • On-premises: Leads at 55% share, reflecting data sovereignty requirements and regulatory compliance mandates in regulated industries.
  • Cloud-based: Growing steadily as enterprises adopt hybrid approaches combining on-premises infrastructure with selective cloud services.

Breakup by Enterprise Size:

  • Small and Medium-sized Enterprises: Represents the largest segment at 58% share, driven by cost-effective access to enterprise-grade IT capabilities.
  • Large Enterprises: Reflects steady demand for sophisticated, integrated managed service solutions at scale.

Breakup by End Use:

  • IT and Telecommunication: Leads at 24% share, driven by the sector’s need for advanced network management and cybersecurity services.
  • BFSI: Requires secure, compliant managed services supporting financial data protection.
  • Healthcare: Relies on managed services for data security and regulatory compliance.
  • Entertainment and Media: Utilizes managed services to support content delivery and digital infrastructure.
  • Retail: Adopts managed services to support e-commerce and omnichannel operations.
  • Manufacturing: Requires managed services for industrial automation and operational technology support.
  • Government: Relies on managed services amid rising cybersecurity threats and digital modernization needs.
  • Others: Includes additional sectors adopting managed IT service solutions.

Breakup by Region:

  • Northern Mexico: Anchored by Monterrey and Tijuana, benefiting from nearshoring activity and cross-border connectivity.
  • Central Mexico: Dominates the national landscape, hosting major hyperscale data centers across the Querétaro-Mexico City corridor.
  • Southern Mexico: Presents emerging opportunities supported by growing tourism, healthcare, and logistics sector investment.
  • Others: Comprises secondary technology hubs such as Guadalajara supporting broader ecosystem growth.

Key Challenges and Growth Opportunities in the Mexico Managed Services Market

The Mexico managed services market faces challenges including chronic shortages of qualified cybersecurity professionals and cloud architects driving wage inflation, data sovereignty and security concerns among regulated industries, and uneven digital infrastructure development across regions.

Despite these challenges, the market offers considerable growth opportunities driven by accelerating digital transformation initiatives, rising cybersecurity threats requiring specialized expertise, and continued cost optimization imperatives among SMEs. Continued investment in hyperscale infrastructure and AI-driven service delivery is expected to create substantial opportunities for long-term growth in the Mexico managed services market.

Competitive Landscape

The Mexico managed services market demonstrates a fragmented competitive structure, with multinational technology corporations competing alongside regional service providers and specialized niche players. Market participants are differentiating through service portfolio expansion, technology partnerships, vertical industry expertise, and localized service delivery capabilities, with strategic acquisitions and partnership formations serving as primary competitive strategies to strengthen market positioning across Mexico.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
North America Adult Diaper Market 2026: Size, Trends, Growth, Latest Insights and Forecast to 2034

North America Adult Diaper Market 2026: Size, Trends, Growth, Latest Insights and Forecast to 2034

IMARC Group has recently released a new research study titled “North America Adult Diaper Market Size, Share, Trends and Forecast by Type, Distribution Channel, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

North America Adult Diaper Market Size & Share 2026-2034

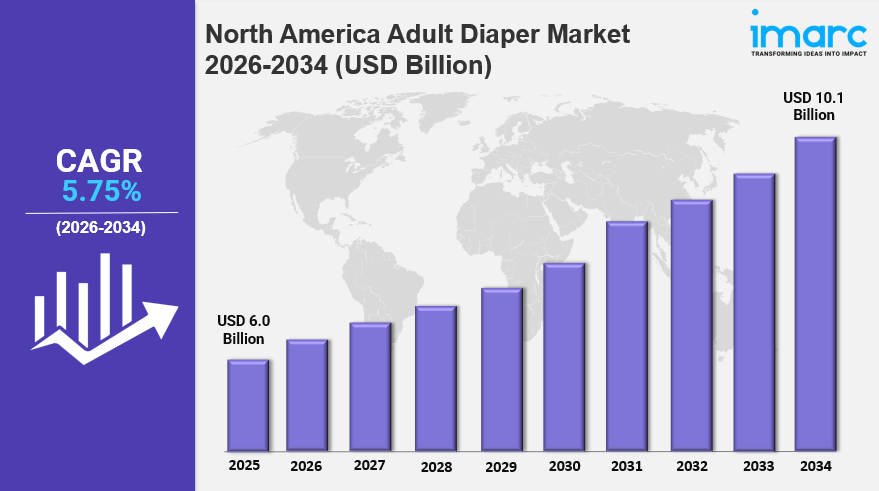
The North America adult diaper market size reached USD 6.0 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 10.1 Billion by 2034, exhibiting a growth rate of CAGR of 5.75% during 2026-2034. The increasing geriatric population and their care needs, along with rising awareness about incontinence products and their benefits, are driving consistent consumption.

Growing preference for convenient and discreet personal care solutions, advancements in product innovation and comfort features, and higher disposable income and improved healthcare accessibility are supporting broader adoption of adult diapers across North America.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 6.0 Billion
  • Projected Market Size (2034): USD 10.1 Billion
  • Growth Rate: CAGR of 5.75% (2026-2034)

Explore Opportunities in the North America Adult Diaper Market: Download the IMARC Sample Report: https://www.imarcgroup.com/north-america-adult-diaper-market/requestsample

Key Growth Drivers and Trends in the North America Adult Diaper Market

Growth in the North America adult diaper market is being driven by an increasing focus on personal care and hygiene, as consumers increasingly purchase adult diapers that are comfortable, absorbent, and equipped with odor-controlling capabilities. This is particularly observed among the geriatric demographic, disabled individuals, and patients with chronic health problems. The stigma associated with incontinence is slowly fading, and individuals are now more openly seeking solutions, which continues to increase adult diaper sales.

One of the leading North America adult diaper market trends is continued product innovation and improved comfort, as manufacturers engineer features such as breathable materials, odor control technologies, elastic waistbands for better fit, and enhanced absorbency that keeps users dry for longer periods. These innovations also target consumers with sensitive skin through hypoallergenic formulations, making adult diapers more appealing and reliable for a broader range of users.

Another key factor supporting North America adult diaper market growth is the increase in healthcare spending and insurance coverage, with many elderly individuals and those suffering from chronic diseases now better positioned to buy incontinence products due to increased access and affordability of healthcare. Adult diapers have also become an accepted item covered under insurance policies as part of incontinence management, easing out-of-pocket cost concerns and expanding accessibility across the region.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1520&flag=C

North America Adult Diaper Industry Segmentation Insights

Breakup by Type:

  • Adult Pad Type Diaper: Represents the leading segment, driven by usability, comfort, and affordability, with strong availability in pharmacies and online stores.
  • Adult Flat Type Diaper: Provides a flexible option suited to varying levels of incontinence care needs.
  • Adult Pant Type Diaper: Offers convenience and a more discreet, underwear-like fit for active users.

Breakup by Distribution Channel:

  • Pharmacies: Accounts for the largest share, supported by easy reach, wide consumer acceptance, and personalized consultations.
  • Convenience Stores: Provides accessible, everyday purchase options for consumers.
  • Online Stores: Growing steadily due to privacy, convenience, and expanding e-commerce reach.
  • Others: Includes additional retail and distribution channels serving the market.

Breakup by Region:

  • United States: Accounts for the largest market share, supported by a large geriatric population and advanced healthcare infrastructure.
  • Canada: Reflects steady demand supported by a growing aging population and expanding distribution networks.

Key Challenges and Growth Opportunities in the North America Adult Diaper Market

The North America adult diaper market faces challenges including the technical complexity of developing eco-friendly and biodegradable formulations that match the comfort and performance of conventional products, along with the need for continued investment in expanding accessible distribution networks.

Despite these challenges, the market offers considerable growth opportunities driven by continued growth of the geriatric population, rising healthcare spending and insurance coverage, and growing demand for premium, eco-friendly, and skin-friendly product innovations. Continued expansion of online distribution channels and partnerships with healthcare providers is expected to create substantial opportunities for long-term growth in the North America adult diaper market.

Competitive Landscape

The North America adult diaper market is competitive, with key players driving growth through product innovation, introducing sophisticated features such as enhanced absorbency, skin-friendly materials, and odor-control capabilities. Manufacturers are also launching eco-friendly and biodegradable products, expanding online distribution channels, and forming partnerships with healthcare providers and long-term care facilities to strengthen their market position across North America.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
US Deodorant Market 2026: Size, Share, Industry Overview and Forecast to 2034

US Deodorant Market 2026: Size, Share, Industry Overview and Forecast to 2034

IMARC Group has recently released a new research study titled “US Deodorant Market Report by Product Type (Sprays, Roll-On, Creams, and Others), Distribution Channel (Supermarkets and Hypermarkets, Convenience Stores, Pharmacies, Online Stores, and Others), Packaging Type (Metal, Plastic, and Others), and Region 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

US Deodorant Market Size & Share 2026-2034

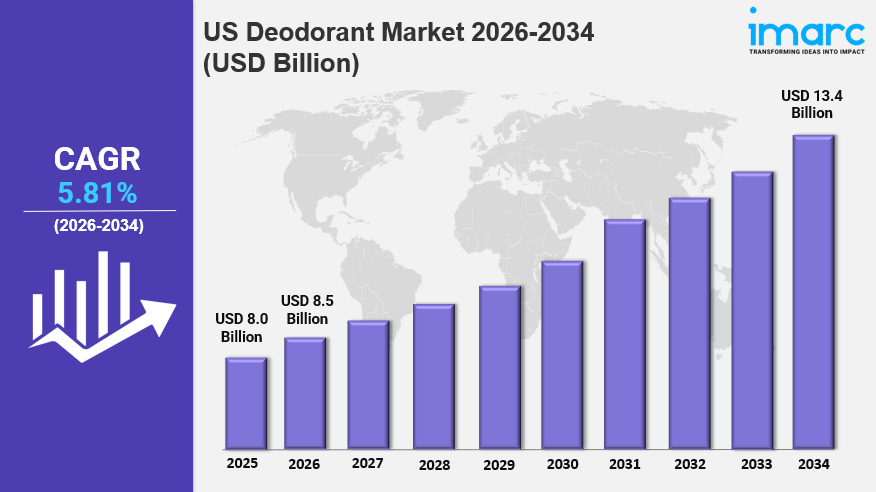
The US deodorant market size increased from USD 8.0 Billion in 2025 to USD 8.5 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 13.4 Billion by 2034, exhibiting a growth rate (CAGR) of 5.81% during 2026–2034. The escalating health and wellness trend among the masses, the introduction of gender-specific products, and growing demand for eco-friendly deodorants are driving consistent market growth.

Increasing participation in sports and allied activities, proliferation of e-commerce platforms, and recent advancements in skincare science are influencing market trends, promoting innovation in effective, skin-friendly, and long-lasting odor protection solutions across the United States.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 8.0 Billion
  • Market Size (2026): USD 8.5 Billion
  • Projected Market Size (2034): USD 13.4 Billion
  • Growth Rate: CAGR of 5.81% (2026-2034)

Explore Opportunities in the US Deodorant Market: Download the IMARC Sample Report: https://www.imarcgroup.com/us-deodorant-market/requestsample

Key Growth Drivers and Trends in the US Deodorant Market

Growth in the US deodorant market is being driven by the escalating health and wellness trend among the masses, as personal hygiene and cleanliness become an increasingly essential part of daily routines across teenagers, adults, and the geriatric population. Body odor is widely regarded as socially unacceptable, and rising awareness through educational campaigns by health organizations about the role of bacteria in causing odor is boosting the sale of deodorants, while consumers increasingly seek innovative formulations offering added benefits such as skin moisturizing properties or added vitamins.

One of the leading US deodorant market trends is the introduction of gender-specific products, as men and women have different requirements in terms of intensity, duration, odor protection, and fragrance type. Men-specific deodorants offer longer-lasting effects and stronger scents suited to active lifestyles, while women’s deodorants focus on milder fragrances and skin-sensitive formulations, opening new avenues for premium and specialized products supported by targeted marketing strategies.

Another key factor supporting market growth is the growing demand for eco-friendly deodorants, driven by heightened consumer emphasis on sustainability and reducing environmental pollution. This is complemented by the proliferation of e-commerce platforms and easy product availability across pharmacies and supermarkets, aggressive marketing and promotional campaigns using social media influencers and celebrity endorsements, and increasing humidity and hot weather conditions that support year-round product demand.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=12182&flag=C

US Deodorant Industry Segmentation Insights

Breakup by Product Type:

  • Sprays: Offers convenient, quick-drying application with uniform coverage for effective odor and sweat protection.
  • Roll-On: Provides targeted application and reduced wastage, with formulations suited for sensitive skin.
  • Creams: Contains moisturizing ingredients such as shea butter or coconut oil, packaged in compact, travel-friendly containers.
  • Others: Includes additional deodorant formats serving specialized consumer preferences.

Breakup by Distribution Channel:

  • Supermarkets and Hypermarkets: Leads the market, offering a broad range of brands along with competitive pricing and promotions.
  • Convenience Stores: Supports quick, accessible purchases through high-traffic and extended-hours locations.
  • Pharmacies: Offers in-person advice and product testers, particularly for sensitive-skin or specialized needs.
  • Online Stores: Reflects growing demand for a wider brand selection and easy price and ingredient comparison.
  • Others: Includes additional distribution channels serving the deodorant market.

Breakup by Packaging Type:

  • Metal: Offers durability and a premium aesthetic, with strong resistance to damage and temperature extremes.
  • Plastic: Dominates the market due to cost-effectiveness, light weight, and design versatility.
  • Others: Includes alternative packaging materials balancing sustainability and product stability.

Breakup by Region:

  • Northeast: Reflects strong demand driven by dense urban centers and higher disposable income for premium products.
  • Midwest: Supports high consumption tied to dense population, urban lifestyles, and lower cost of living.
  • South: Leads the market, driven by a warm climate and a major retail hub offering wide distribution.
  • West: Reflects growing preference for natural and organic deodorants amid a health-conscious, eco-focused population.

Key Challenges and Growth Opportunities in the US Deodorant Market

The US deodorant market faces challenges including intense brand competition among established multinational players, the need for continued reformulation to meet evolving clean-label and aluminum-free preferences, and the complexity of maintaining consistent product quality and shelf appeal across diverse retail channels.

Despite these challenges, the market offers considerable growth opportunities driven by continued innovation in natural and organic formulations, expanding e-commerce and direct-to-consumer channels, and growing demand for sustainable, biodegradable packaging. Continued investment in gender-specific and skin-friendly product development is expected to create substantial opportunities for long-term growth in the US deodorant market.

Competitive Landscape

The US deodorant market is highly competitive, fueled by rising health and wellness awareness, evolving consumer preferences, and continuous product innovation. Leading companies are focusing on natural and organic formulations, gender-specific products, and deodorants offering added skin benefits, while adopting sustainable practices such as biodegradable packaging and lower-carbon manufacturing. Players are also investing heavily in market research and building strong brand identities through targeted marketing campaigns and strategic retail partnerships to strengthen distribution and market presence.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
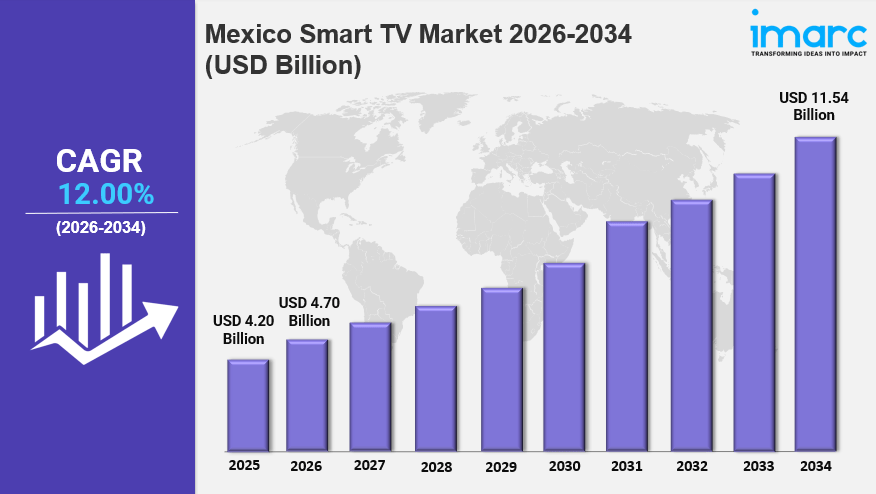
Mexico Smart TV Market is Projected To Reach USD 11.54 Billion By 2034 at CAGR of 12.00%

Mexico Smart TV Market is Projected To Reach USD 11.54 Billion By 2034 at CAGR of 12.00%

IMARC Group has recently released a new research study titled “Mexico Smart TV Market Size, Share, Trends and Forecast by Resolution Type, Technology, Screen Size, Screen Type, Platform, Application, and Distribution Channel, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Mexico Smart TV Market Size & Share 2026-2034

The Mexico smart TV market size increased from USD 4.20 Billion in 2025 to USD 4.70 Billion in 2026 and is projected to reach USD 11.54 Billion by 2034, growing at a CAGR of 12.00% during 2026-2034. Rising internet penetration, expanding OTT streaming consumption, and growing demand for connected home entertainment are driving consistent adoption.

Smart TV adoption in Mexico has risen sharply from 5.4% in 2015 to 50% in 2025, expanding the connected-viewing base and encouraging households to upgrade from conventional televisions to internet-enabled models, strengthening the Mexico smart TV market share.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 4.20 Billion
  • Market Size (2026): USD 4.70 Billion
  • Projected Market Size (2034): USD 11.54 Billion
  • Growth Rate: CAGR of 12.00% (2026-2034)

Explore Opportunities in the Mexico Smart TV Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-smart-tv-market/requestsample

Key Growth Drivers and Trends in the Mexico Smart TV Market

Growth in the Mexico smart TV market is being driven by rising internet penetration, with around 110 million internet users, equal to 83.5% of the total population, by late 2025. Greater household connectivity increases access to streaming platforms, online content, and smart home applications, encouraging consumers to adopt internet-enabled televisions for on-demand entertainment as more households gain reliable high-speed connectivity.

One of the leading Mexico smart TV market trends is OTT platform integration and smart TV OS competition, as brands compete to offer smoother access to Netflix, YouTube, Roku, Prime Video, Disney+, and local content apps. Operating systems such as Roku TV, Google TV, Android TV, Tizen, and webOS are becoming important purchase factors, pushing manufacturers to strengthen software ecosystems, content partnerships, and user experience differentiation.

Another key factor supporting Mexico smart TV market growth is the expansion of ad-free premium viewing experiences, exemplified by Roku’s April 2026 launch of Howdy in Mexico, a new ad-free SVOD service offering unlimited access to a growing content library from partners such as Lionsgate, Sony, and TV Azteca. The launch of affordable ad-free streaming services encourages greater engagement with connected TV platforms and increases the value of smart TVs within households.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=6129&flag=C

Mexico Smart TV Industry Segmentation Insights

Breakup by Resolution Type:

  • 4K UHD TV: Leads the segment, driven by growing OTT content availability and consumer preference for sharper picture quality.
  • Full HD TV: Remains popular among cost-conscious consumers seeking reliable picture quality.
  • HD TV: Continues to serve entry-level and budget-focused segments of the market.
  • 8K TV: Represents an emerging premium segment as consumers seek cinema-like home viewing.

Breakup by Technology:

  • LED: Leads the segment, offering an accessible balance of affordability and picture quality.
  • LCD: Continues to serve budget-conscious consumer segments.
  • OLED: Gaining traction among premium buyers seeking superior contrast and color accuracy.
  • QLED: Appeals to consumers seeking enhanced brightness and color performance.

Breakup by Screen Size:

  • Below 32 Inches: Serves compact spaces and secondary-room installations.
  • 32 to 45 Inches: Leads the segment, offering a balance of affordability and screen size for households.
  • 46 to 55 Inches: Reflects growing preference for larger home entertainment displays.
  • 56 to 65 Inches: Gaining popularity among consumers upgrading to premium home theater setups.
  • Above 65 Inches: Represents the premium large-screen segment for immersive viewing experiences.

Breakup by Screen Type:

  • Flat: Leads the segment as the standard preference across most consumer segments.
  • Curved: Appeals to premium buyers seeking an immersive viewing experience.

Breakup by Platform:

  • Android: Leads the segment, offering broad app availability and familiar user interfaces.
  • Roku: Popular for its simple interface and expanding ad-free streaming offerings.
  • WebOS: Anchors LG’s smart TV experience with strong localization for Mexican viewers.
  • Tizen OS: Powers Samsung’s smart TV ecosystem with integrated smart home features.
  • iOS: Supports connectivity and casting integration for Apple device users.
  • My Home Screen: Provides a simplified interface option for select smart TV brands.
  • Others: Includes additional platform options serving the market.

Breakup by Application:

  • Residential: Leads at 87.4% share, driven by household OTT streaming, gaming, and connected entertainment demand.
  • Commercial: Growing through hotel and hospitality smart TV adoption, retail digital signage, and corporate conference displays.

Breakup by Distribution Channel:

  • Offline: Leads at 66.8% share, as consumers prefer in-store evaluation of screen size, picture quality, and after-sales support.
  • Online: Growing fastest at approximately 13.8% CAGR through e-commerce platforms and brand direct-to-consumer sales.

Key Challenges and Growth Opportunities in the Mexico Smart TV Market

The Mexico smart TV market faces challenges including informal gray-market sales and counterfeit TV risks that undercut authorized brands, along with consumer credit and affordability barriers that limit purchases of higher-priced 4K, OLED, and large-screen models.

Despite these challenges, the market offers considerable growth opportunities driven by the integration of AI and voice-controlled smart TVs, expansion of ad-free premium viewing experiences, and growing demand for OLED and MiniLED premium displays. Continued growth in commercial hospitality adoption and online distribution is expected to create substantial opportunities for long-term growth in the Mexico smart TV market.

Competitive Landscape

The Mexico smart TV market is moderately concentrated, with leading players such as Samsung, LG Electronics, Sony Group Corporation, TCL, and Hisense Group focusing on display technology, operating systems, AI-enabled features, and content ecosystem integration. Companies are strengthening partnerships with streaming platforms and FAST channels, while Chinese brands continue to gain market share through aggressive pricing and feature-rich offerings across Mexico.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302
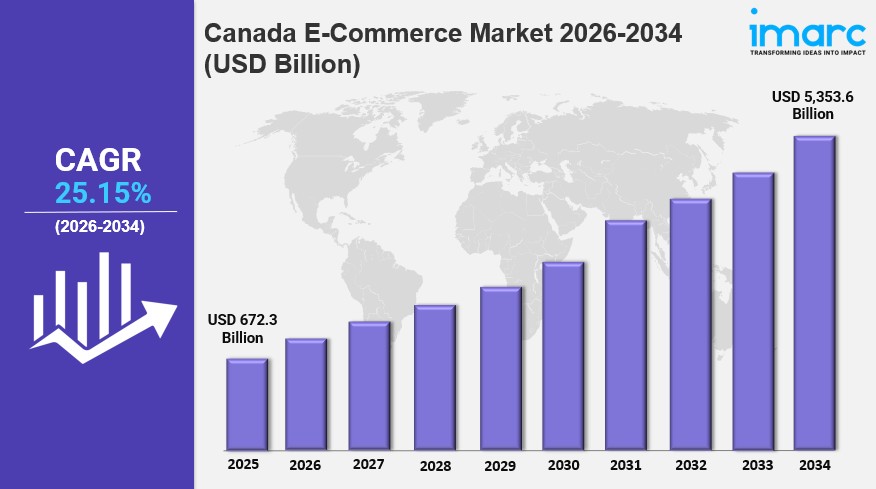
Canada E-Commerce Market Size is Expected to Reach USD 5,353.6 Billion by 2034 | CAGR 25.15%

Canada E-Commerce Market Size is Expected to Reach USD 5,353.6 Billion by 2034 | CAGR 25.15%

IMARC Group has recently released a new research study titled “Canada E-Commerce Market Size, Share, Trends and Forecast by Business Model, Mode of Payment, Service Type, Product Type, and Region, 2026-2034”, offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.

Canada E-Commerce Market Size & Share 2026-2034

The Canada e-commerce market size reached USD 672.3 Billion in 2025 and is projected to reach USD 5,353.6 Billion by 2034, expanding at a CAGR of 25.15% during 2026-2034. The growth of the e-commerce market is driven by rapid digital adoption, rising mobile commerce penetration, expanding broadband infrastructure, and evolving consumer preference for online retail.

Canada’s high internet penetration rate of 95% in 2025 provides a strong foundation for sustained e-commerce growth, while government digital infrastructure investment and innovation in digital payments further influence the Canada e-commerce market share throughout the forecast period.

Key Market Statistics at a Glance

  • Base Year: 2025
  • Historical Years: 2020-2025
  • Forecast Period: 2026-2034
  • Market Size (2025): USD 672.3 Billion
  • Projected Market Size (2034): USD 5,353.6 Billion
  • Growth Rate: CAGR of 25.15% (2026-2034)

Explore Opportunities in the Canada E-Commerce Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-e-commerce-market/requestsample

Key Growth Drivers and Trends in the Canada E-Commerce Market

Growth in the Canada e-commerce market is being driven by rising internet and mobile penetration, as the country’s internet penetration reached 95% in 2025, providing a vast addressable digital consumer base. Mobile commerce is projected to account for over 50% of all e-commerce transactions in Canada by 2025, with smartphone users reaching 35 million, and platforms investing in mobile-first experiences are capturing higher conversion rates and stronger customer retention.

One of the leading Canada e-commerce market trends is government digital infrastructure investment, as federal and provincial broadband initiatives, including the Universal Broadband Fund targeting USD 2.35 billion in investment, expand internet access in underserved rural and remote communities. Increased connectivity directly expands the e-commerce addressable market, unlocking new consumer segments outside major metropolitan areas such as Toronto, Vancouver, and Montreal.

Another key factor supporting Canada e-commerce market growth is innovation in digital payments, as Canada’s Real-Time Rail (RTR) system under Payments Canada’s modernization program, set to launch in late 2026, will introduce instant account-to-account payment rails. By 2025, digital payments account for approximately 86% of total payment volume, with digital wallets including Apple Pay, Google Pay, and Interac e-Transfer reducing transaction friction and increasing checkout conversion among mobile-native consumers.

Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=37397&flag=C

Canada E-Commerce Industry Segmentation Insights

Breakup by Business Model:

  • B2C: Leads the market at 68.4% in 2025, driven by marketplace platforms and direct-to-consumer storefronts offering convenience, competitive pricing, and broad product assortments.
  • B2B: Growing rapidly at 21.7% share as enterprise procurement digitalization accelerates online sourcing for office supplies, industrial equipment, and business services.
  • C2C: Holds a 6.3% share, operating through platforms like eBay Canada, Facebook Marketplace, and Kijiji.
  • Others: Includes government e-procurement, nonprofit digital fundraising, and hybrid models, holding a 3.6% share.

Breakup by Mode of Payment:

  • Payment Cards: Represents a widely used payment method supported by strong card issuance and merchant acceptance networks.
  • Online Banking: Supports direct bank-to-merchant transactions favored for security and convenience.
  • E-Wallets: Growing in popularity through digital wallets such as Apple Pay, Google Pay, and Interac e-Transfer.
  • Cash-On-Delivery: Continues to serve consumers preferring payment upon receipt of goods.
  • Others: Includes emerging payment methods such as buy-now-pay-later and digital currencies.

Breakup by Service Type:

  • E-Tailing: Leads the market at 52.6% in 2025 through fashion, electronics, home goods, and grocery categories.
  • Financial: Holds an 18.4% share, including digital banking, insurance, and investment platforms.
  • Travel and Leisure: Represents 14.3% share, benefiting from growing online booking adoption across airlines, hotels, and experience providers.
  • Digital Content: Accounts for 10.2% share and grows at approximately 28.2% CAGR through streaming, gaming, e-learning, and SaaS subscriptions.
  • Others: Includes government services, healthcare telemedicine, and niche digital platforms at 4.5% share.

Breakup by Product Type:

  • Groceries: Represents a growing category supported by expanding online grocery delivery and subscription services.
  • Clothing and Accessories: Benefits from strong fashion e-tailing demand and competitive online discounting.
  • Mobiles and Electronics: Driven by consumer demand for the latest devices and competitive online pricing.
  • Health and Personal Care: Growing steadily through expanding online pharmacy and wellness product offerings.
  • Others: Includes home goods, furniture, and additional product categories sold through online channels.

Breakup by Region:

  • Ontario: Represents the leading regional market at 39.4% in 2025, anchored by dense urban population, high household incomes, and advanced logistics infrastructure.
  • Quebec: Holds a 23.8% share, supported by French-language platform investments, growing mobile commerce, and provincial e-commerce support programs.
  • British Columbia: Represents 15.6% share, driven by tech-forward consumer demographics in Vancouver and expanding cross-border trade with Asia-Pacific markets.
  • Alberta: Holds a 13.4% share, supported by high per-capita income and strong enterprise B2B platform adoption.
  • Others: Includes Saskatchewan, Manitoba, Nova Scotia, New Brunswick, and the Northern Territories, contributing 7.8% share through rural e-commerce and government digital services.

Key Challenges and Growth Opportunities in the Canada E-Commerce Market

The Canada e-commerce market faces challenges including cybersecurity and data privacy concerns under PIPEDA regulations, high last-mile logistics costs in suburban and rural regions, and regulatory complexity such as Quebec’s Bill 96 mandating French-language parity across digital touchpoints.

Despite these challenges, the market offers considerable growth opportunities driven by mobile commerce expansion, AI-driven personalization, cross-border e-commerce growth, and rural broadband rollout. Social commerce integration and same-day and micro-fulfillment expansion are expected to create substantial opportunities for long-term growth in the Canada e-commerce market.

Competitive Landscape

The Canada e-commerce market is moderately concentrated, with the top five players holding approximately 40% combined market share in 2025. Companies including Amazon.com, Inc., Costco Wholesale Corporation, Walmart Inc., The Home Depot, Inc., and Canadian Tire compete on fulfillment speed, platform breadth, payment convenience, AI-powered personalization, and customer loyalty programs, while investing in logistics automation and retail media networks to differentiate their offerings.

Author IMARC Group

IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.

Contact Us:

IMARC Group

Email: sales@imarcgroup.com

United States: +1-201-971-6302